HFCL (HFCL): Q2 FY27 results analysis (quarter ended 30 Sep 2026)
All figures consolidated, ₹ crore unless stated. Results released during market hours on 19 Oct 2026 [2]. EBITDA here excludes other income. YoY/QoQ %, margins and ratios are my calculations from reported numbers.
| Metric | Q2 FY27 | YoY | QoQ |
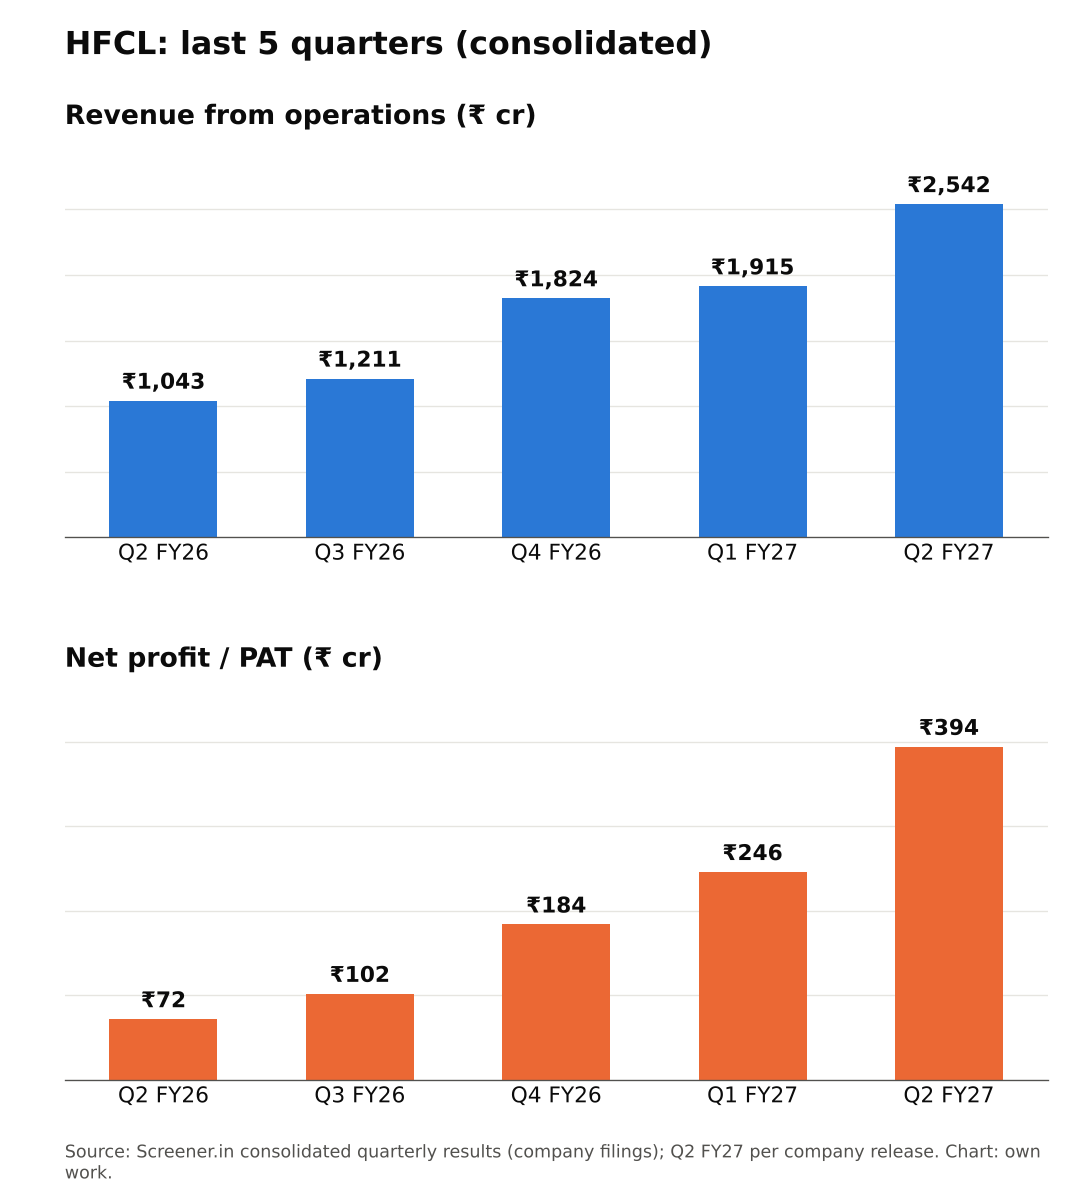
| Revenue from ops | 2,541.8 | +143.7% | +32.7% |
| EBITDA (ex-OI) | 630 | +231.6% | +52.2% |
| EBITDA margin | 24.8% | 18.2% | 21.6% |
| PBT | 538.6 | +408% | +62.5% |
| PAT | 394.2 | +448.1% | +60.5% |
| PAT margin | 15.5% | 6.9% | 12.8% |
| Other income / PBT | 5.0% | 12.3% | 9.3% |
Sources: [1][2][3]
Source note: the company reports EBITDA of ₹658 cr (25.89%), which includes other income (~₹27 cr) [2][3]. Headlines quoting "25.9% margin" use that figure.
Quality of earnings
Growth is operational. Other income is just 5% of PBT, down from 12% a year ago [3]. The tax rate is ~26.8% (₹144 cr) [2], so there is no tax cushion. Finance cost was flat at ₹65 cr; D&A rose to ₹54 cr from ₹36 cr as new capacity came on [3].
MD Mahendra Nahata said there were "no one-time gains" [5]. One negative item is in the numbers: the EPC segment lost ~₹121 cr because BharatNet milestone bills were delayed [5]. So the product business earned more than the consolidated margin suggests (my reading).
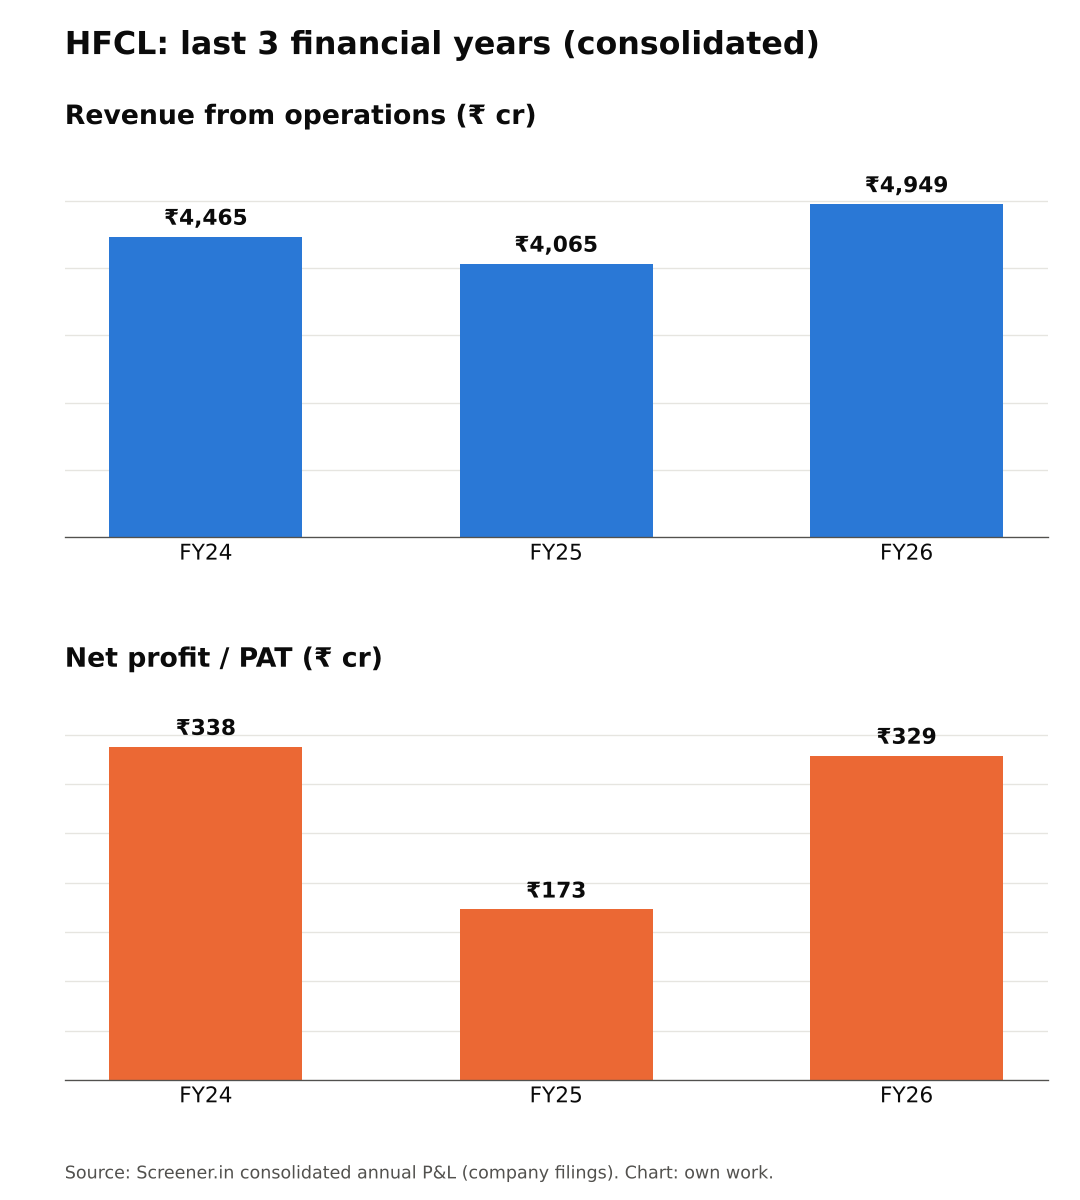
Base effect: FY25 and Q1 FY26 were weak (Q1 FY26 was a loss) [3]. Q2 FY26 PAT of ₹72 cr is a low base, so the +448% YoY looks dramatic. The +60% QoQ is the cleaner read.
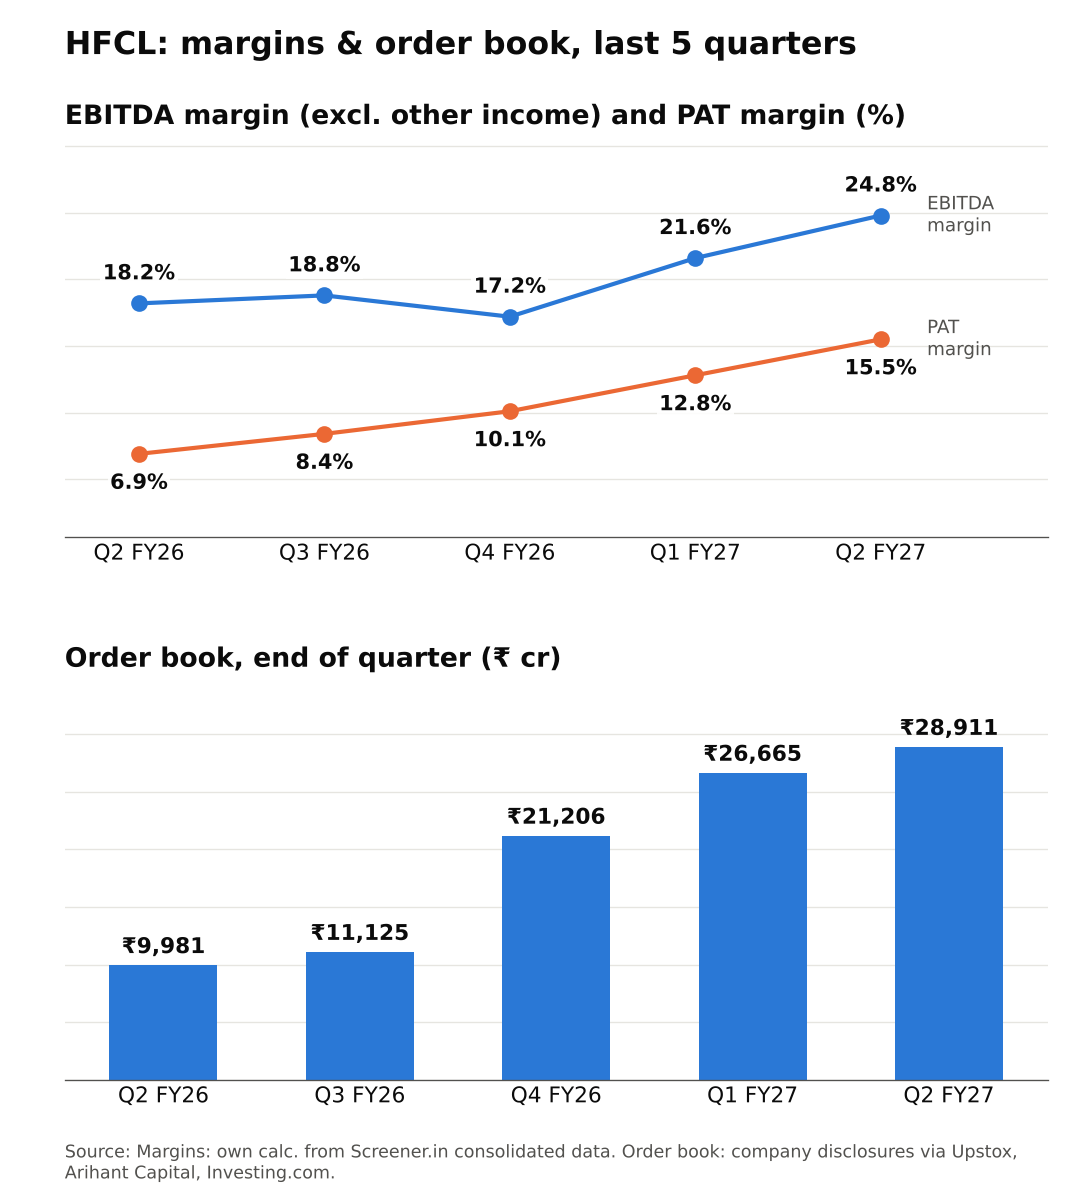
Margins (Chart 3)
EBITDA margin (ex-OI) over five quarters: 18.2% → 18.8% → 17.2% → 21.6% → 24.8% [3]. Management credits product mix: data-centre fibre for hyperscalers is priced above telecom fibre, plus connectivity products [5]. Fibre prices have "more or less stabilised" after a ~20% rise [5].
Guidance: what changed
- Revenue: FY27 growth guidance raised to at least 80% [4][5]. It was 20–25% (₹6,000–6,250 cr) at Q4 [7], then 40% after Q1 [4]. On FY26 revenue of ₹4,949 cr, 80% means ~₹8,900 cr. H1 is ₹4,457 cr, so H2 only needs to match H1 (my calculation).
- ₹10,000 cr target: now possibly FY28, earlier than the FY29 aim [4].
- EPC: At Q4, management said EPC would turn profitable from Q2 FY27 [7]. It now expects ₹75–100 cr more losses over two quarters and profit in Q1 FY28 [5]. Slipped.
- Capex: At Q4 it was ~₹600 cr for FY27 [7]. Now ~₹1,800 cr is planned for fibre, cable and preform. Preform (300→600 MT) is targeted for Oct 2028 [4][5].
- Defence: ₹500–600 cr in FY27 and ₹2,000+ cr in FY28 [4]. An analyst noted only ~₹80 cr was booked in H1 [5].
- Order book: ₹28,911 cr, up from ₹26,665 cr in Q1. 57% is exports, and ~70% of the OFC/DCI book is linked to hyperscalers [4].
Positives
- Third guidance upgrade this year; order book nearly 3x YoY [4][7]
- Margin expansion despite EPC losses [3][5]
- Low dependence on other income [3]
Concerns
- Customer concentration: hyperscaler and export orders dominate [4]
- EPC losses continue for two more quarters [5]
- Preform input costs are elevated, and germanium needs long-term sourcing [5]
- Borrowings of ₹1,840 cr against a capex step-up [4]
Things to track in Q3 FY27
- Sequential revenue growth, which management expects [5]
- EBITDA margin: can ~25% hold as fibre price hikes slow? [5]
- EPC losses vs the ₹75–100 cr indication
- Defence revenue run-rate vs the ₹500 cr+ target
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] IIFL, 19 Oct · [2] Equitybulls – company release, 19 Oct 2:14 PM · [3] Screener.in – consolidated · [4] Investing.com – Q2 slides · [5] Investing.com – Q2 call transcript · [6] Upstox, 19 Oct · [7] Arihant Capital – Q4 FY26 update · [8] Angel One – Q4 FY26 · [9] HDFC Sky – market holidays
Charts:
(1) last 5 quarters revenue & PAT [3];
(2) FY24–FY26 revenue & PAT [3];
(3) margins (own calc. from [3]) and order book [4][6][7][8].