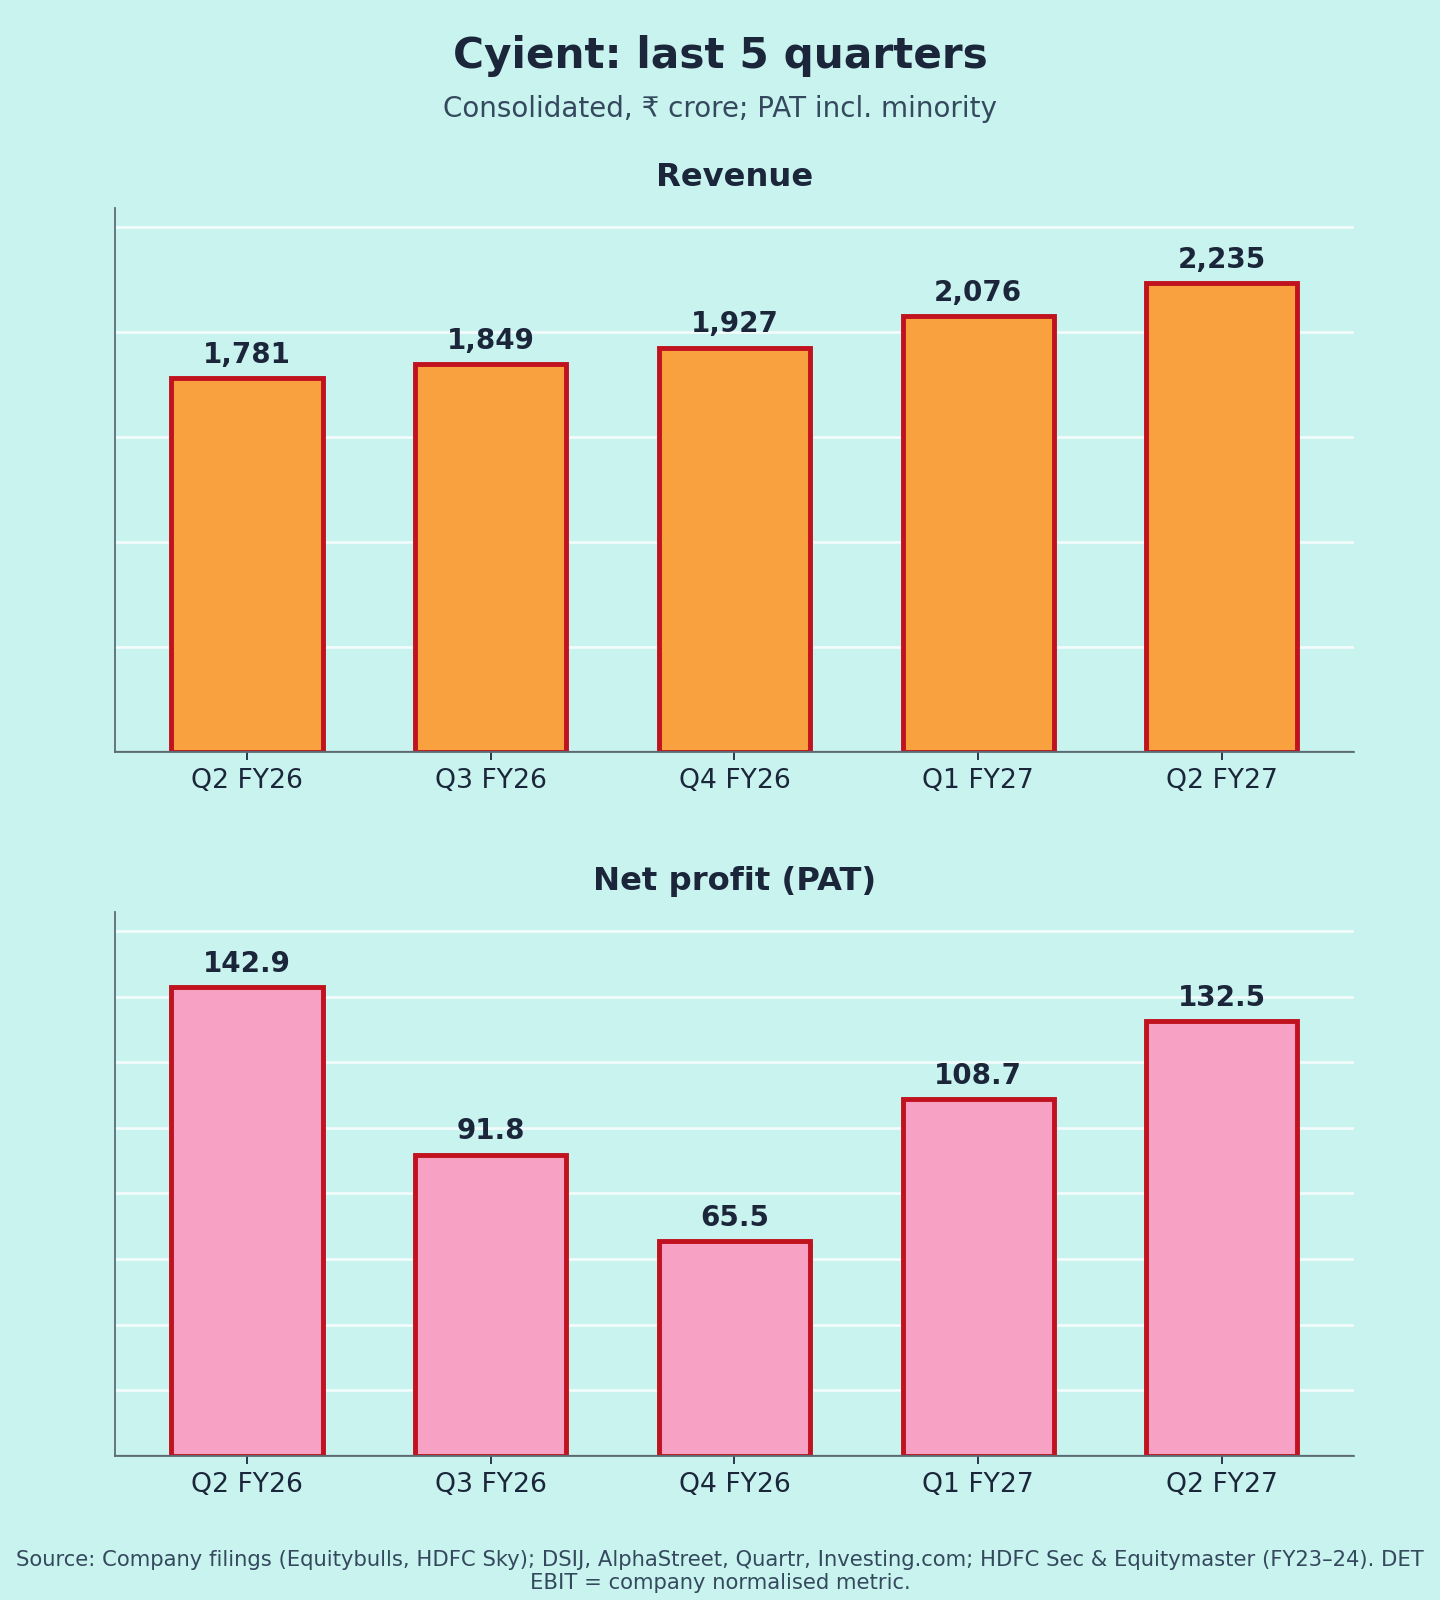
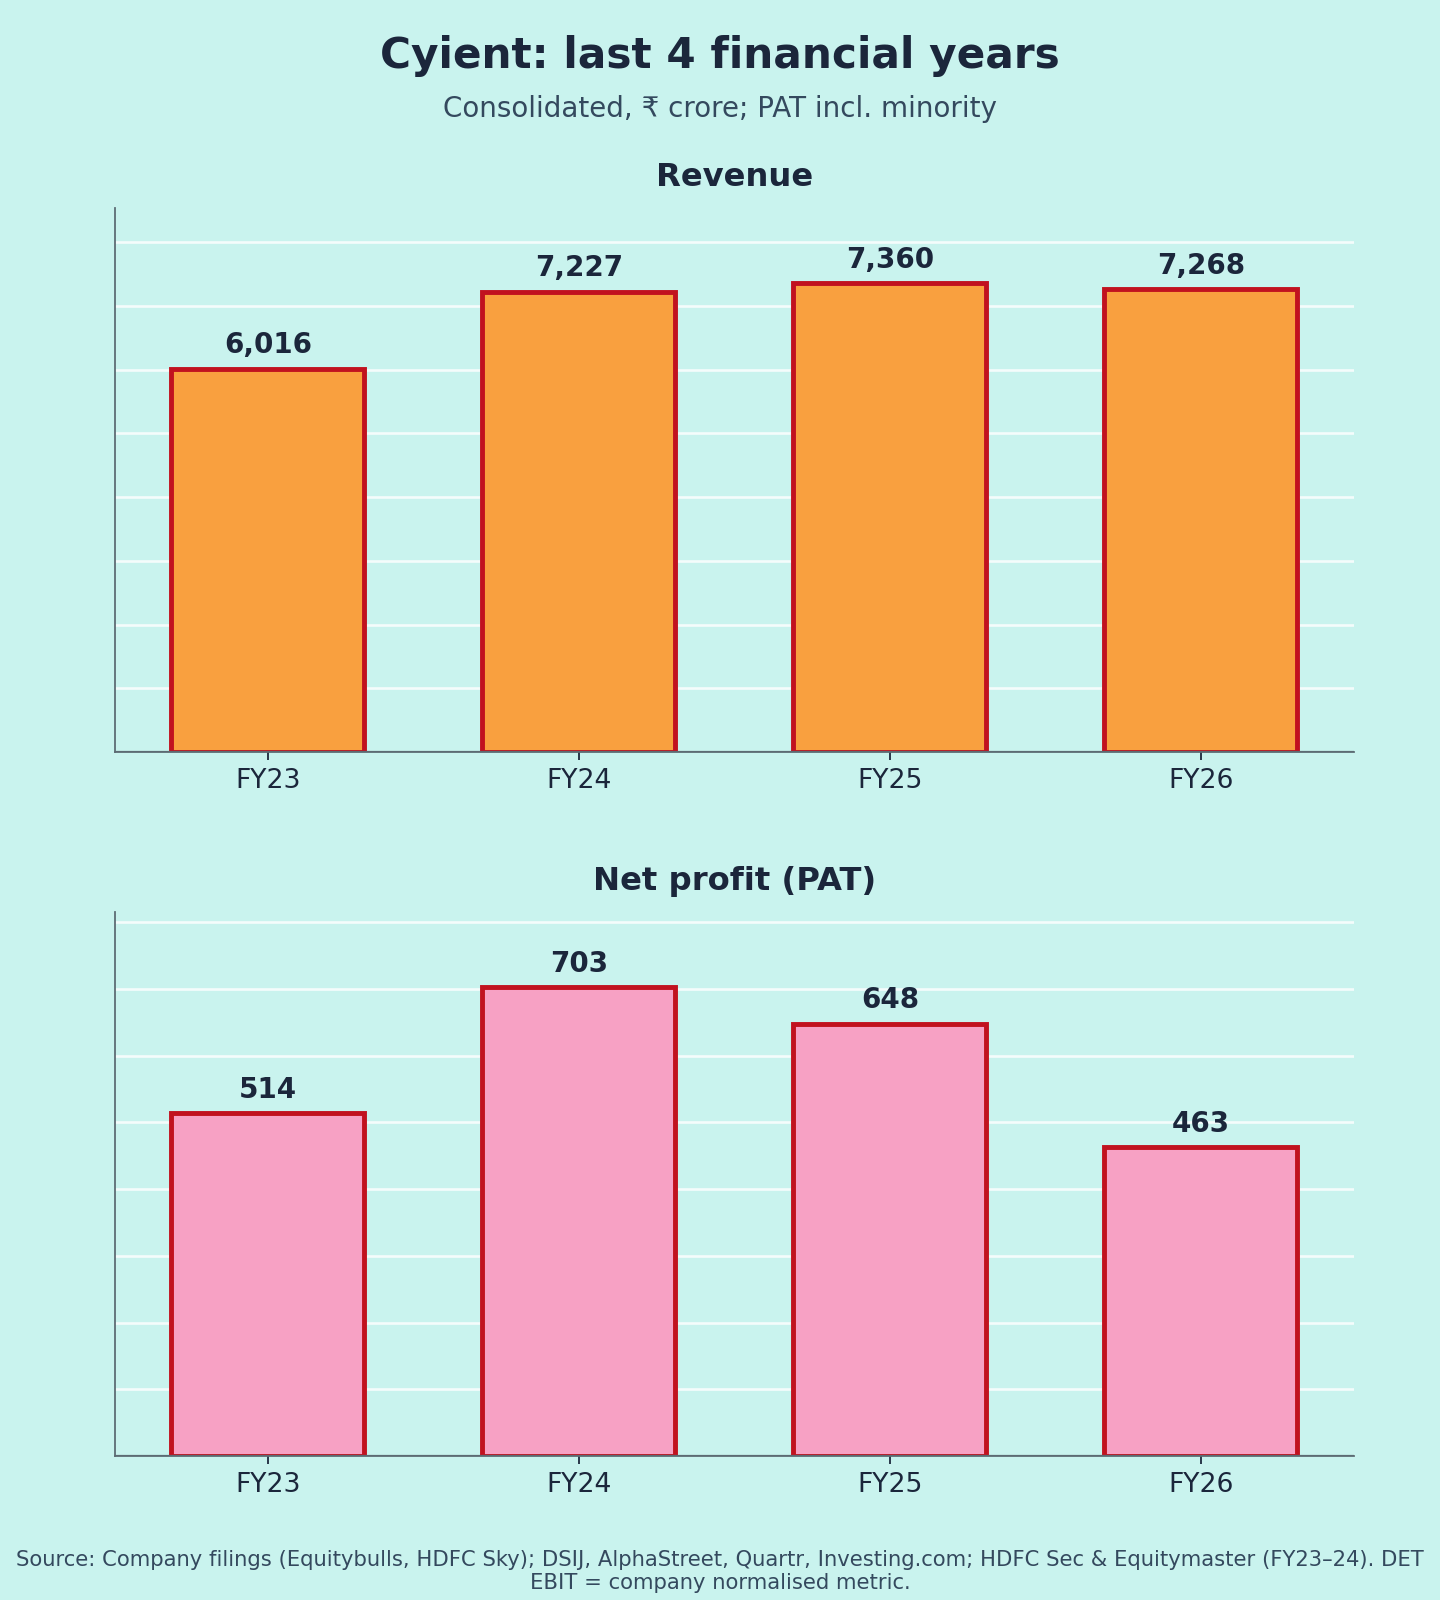
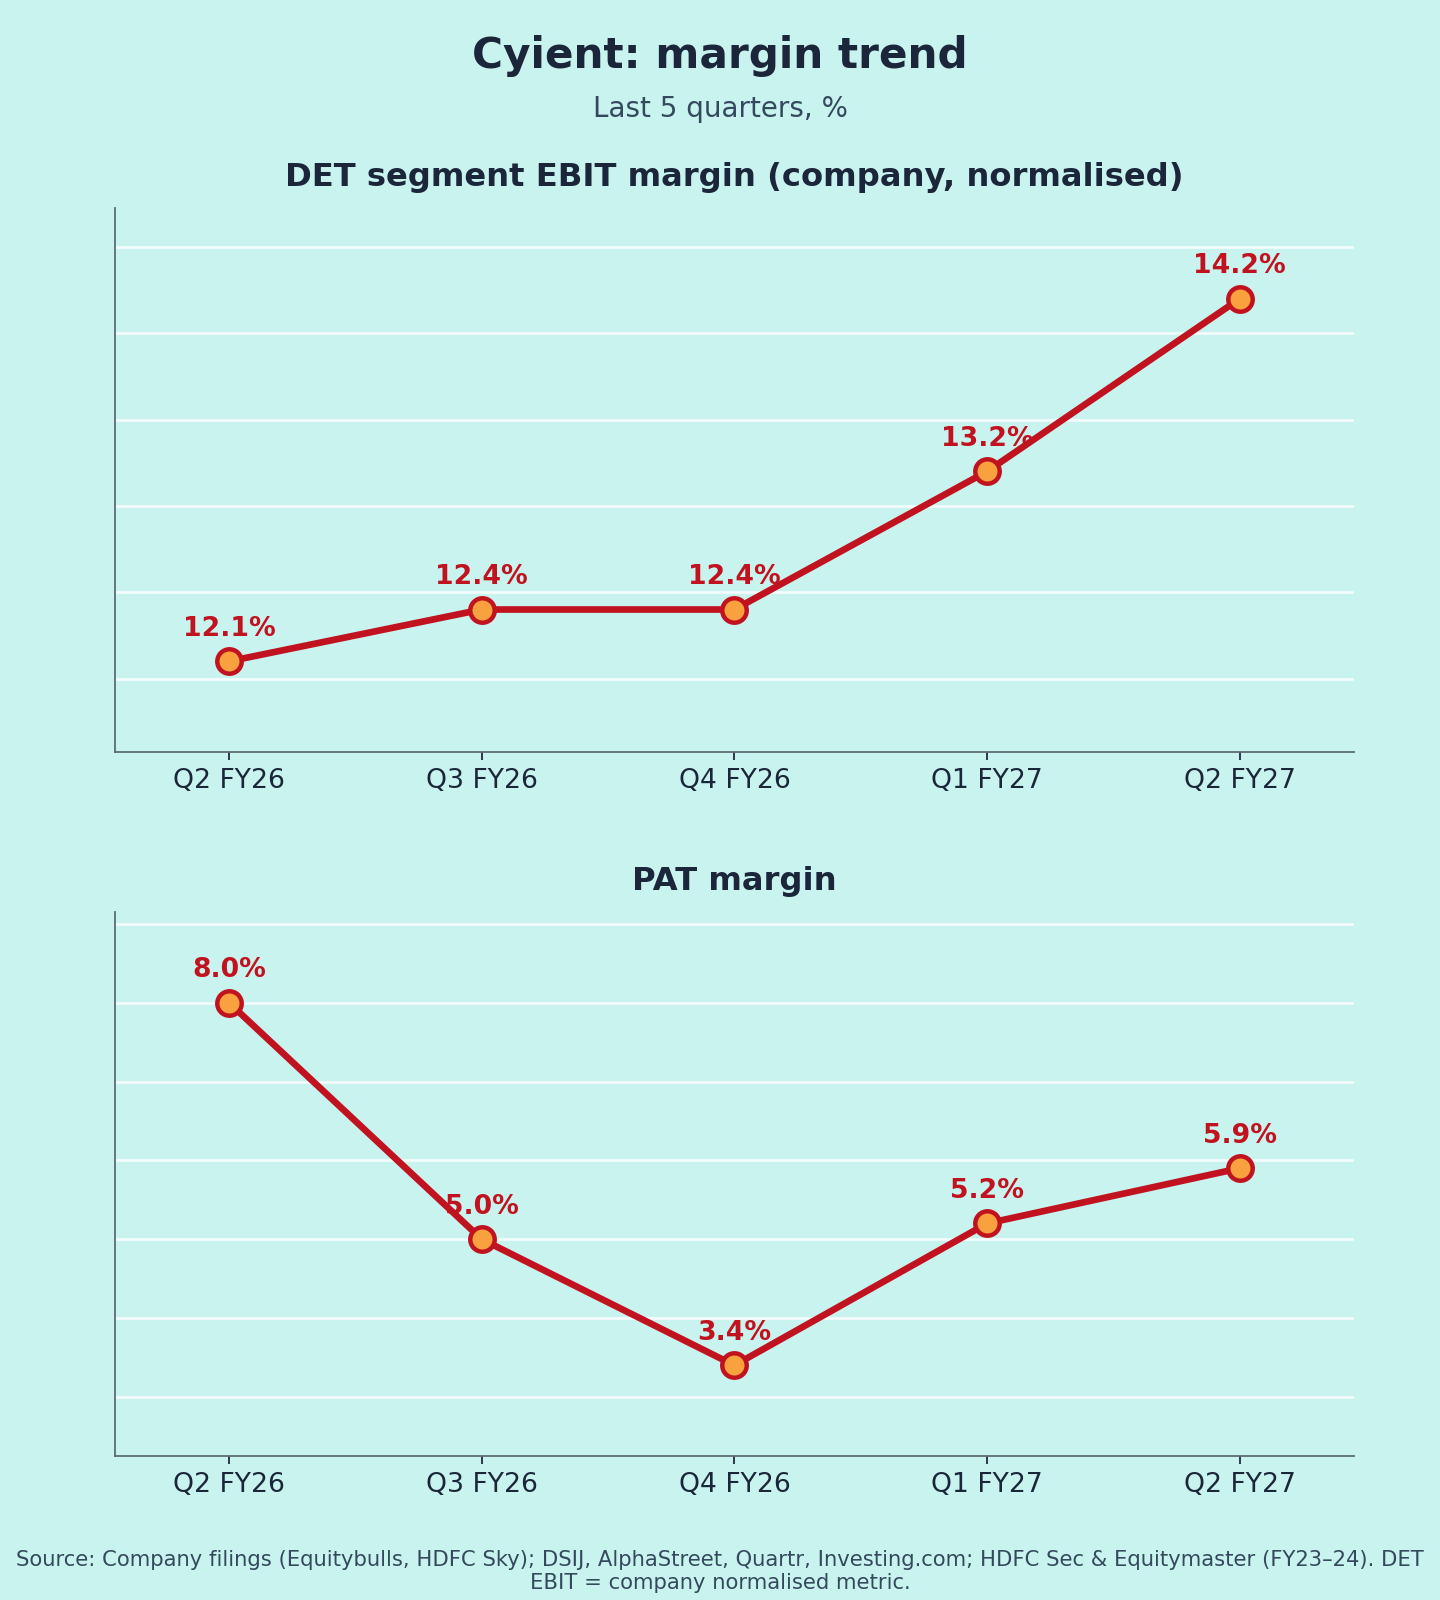
The post holds up on the numbers. I checked them against the call and filing coverage, and its own arithmetic reconciles. Where it goes wrong is the framing. It treats "PBT flat" as weak earnings quality, but operating profit grew about 37%. The real weakness is near-zero organic growth in constant currency, with the rupee doing most of the work.
Checks and corrections
Post's claim Verdict Detail
Organic DET +0.4% YoY Correct, but half the picture In rupees, organic DET grew 9.3% YoY to ₹1,572 cr. The ~8.9 pp gap is currency.
Revenue growth "mostly acquired" Incomplete Currency is a second big non-organic driver (table A)
PBT flat = earnings-quality problem Misleading Operating EBIT rose ~₹61 cr; other income and a one-off in last year's base took it back (table B)
TAO accretive to margins Contested Management said TAO added to margins and PAT. But another call summary quotes the CFO saying TAO's margin is much higher at EBITDA and very close to Cyient's at EBIT (after amortisation and interest).
15% DET margin "within reach" Optimistic The 80 bps gap is ~₹13 cr a quarter, and analysts asked specifically about H2 wage hikes eating into it
Group margin dragged by DLM and semis Correct, unquantified Semis EBIT was about −₹30 cr (−16.2%); DLM EBITDA margin 8.7%
Other income ~₹50 cr a year ago Corroborated Reuters reported Q2 FY26 "revenue" of ₹1,831 cr. That is total income: 1,831 − 1,781 revenue ≈ ₹50 cr other income.
The math
A. Where the ₹454 cr of revenue growth came from (₹ cr)
Component Calculation ₹ cr Share
DET base, Q2 FY26 1,664 ÷ 1.157 1,438
TAO Digital 1,664 − 1,572 92 20%
DET organic, in rupees 1,572 − 1,438 134 29%
— of which currency 1,438 × ~8.9% ~128 ~28%
— of which real organic 1,438 × 0.4% ~6 ~1%
DLM 393 − 311 82 18%
Semis + other (Kinetic) residual ~146 32%
Real constant-currency organic growth explains about 1% of the revenue increase. The rupee rate implied by DET is 1,664 cr ÷ $174.2m ≈ ₹95.5/$. That number matters if the rupee reverses.
B. PBT bridge, Q2 FY26 → Q2 FY27 (approximate)
Line Q2 FY26 Q2 FY27 Change
Group EBIT 1,781 × 9.37% ≈ 166.9 228.4 (10.2%) +61.5 (+37%)
Other income ~50 8.6 −41.4
Exceptional gain (per post) 20.7 0 −20.7
PBT 196.6 196.7 ≈0
The flat PBT is entirely below the operating line. Finance cost is inferred at roughly ₹40 cr in both years so the bridge closes; it isn't confirmed. Also, normalised EBIT may exclude some items.
C. Segment EBIT (₹ cr)
Segment EBIT Margin
DET 236.6 14.2%
Semis (by elimination) −30.0 −16.2%
DLM (implied) ~21.8 ~5.5%
Group 228.4 10.2%
Without semis, group EBIT margin would be (228.4 + 30) ÷ (2,235 − 185) ≈ 12.6%. Semis costs about 240 bps of group margin.
D. Other checks the post missed
Item Math So what
DLM one-off DLM's ₹34 cr PAT included an ₹18.2 cr earnout-reversal gain Check whether this sits in Cyient's consolidated PBT. If it does, underlying PBT is lower than 196.7.
Order intake vs revenue $158.4m intake ÷ $164.5m organic DET revenue 0.96x book-to-bill. A record Q2, but below 1x.
Other-income drop vs cash used ₹41.4 cr × 4 ÷ 7% yield Implies ~₹2,370 cr of cash gone, against a ₹720 cr buyback. Either TAO took ~₹1,650 cr or last year's other income had one-offs (e.g., FX gains).
TAO run-rate $9.6m × 12 = $115m Above the CFO's $100–110m next-12-month figure (bought at ~$80m). Model Q3 at $25–27.5m, not $28.8m.
Valuation ₹121.4 cr × 4 ÷ ~10.5 cr shares ≈ ₹46 EPS; ~₹1,110 ÷ 46 ~24x Q2 annualised. The stock is near the ₹1,125 buyback price. Shares are derived from DET EPS of ₹14.59; post-result price reports conflict, so use the live price.
My read
The post's bear case is right for the wrong reason. Profitability improved: DET EBIT was up 35% YoY. The issues are organic growth of 0.4% constant currency, a rupee tailwind of roughly 9% that could reverse, and a semis business losing ₹30 cr a quarter. The CFO's call that October–March revenue will be clearly higher than April–September is the claim to hold them to. Q3 will show it on organic constant-currency growth, ex-TAO. This is analysis, not a recommendation.
Sources:
- Mudraa: Cyient Q2 FY27 post
- GuruFocus: Q2 FY27 call highlights
- Yahoo Finance: Q2 FY27 call highlights
- Investing.com: Q2 FY27 call transcript
- Investing.com: Q2 FY27 slides
- InvestyWise: Q2 FY27 presentation
- Angel One: DET segment results
- Business Standard/Reuters: Q2 FY26 results
- JM Financial: Cyient DLM Q2 FY27
- Sahi: Q1 FY27 and margin-target deferral
- Sahi: CFO H2 outlook
- Anand Rathi: share price