Cyient (CYIENT): Q2 FY27 results analysis
(quarter ended 30 Sep 2026)
All figures consolidated, ₹ crore unless stated. Results released on 22 Oct 2026 [1]. PAT in the table is the owners' share. YoY/QoQ %, margins and ratios are my calculations from reported numbers.
| Metric | Q2 FY27 | YoY | QoQ |
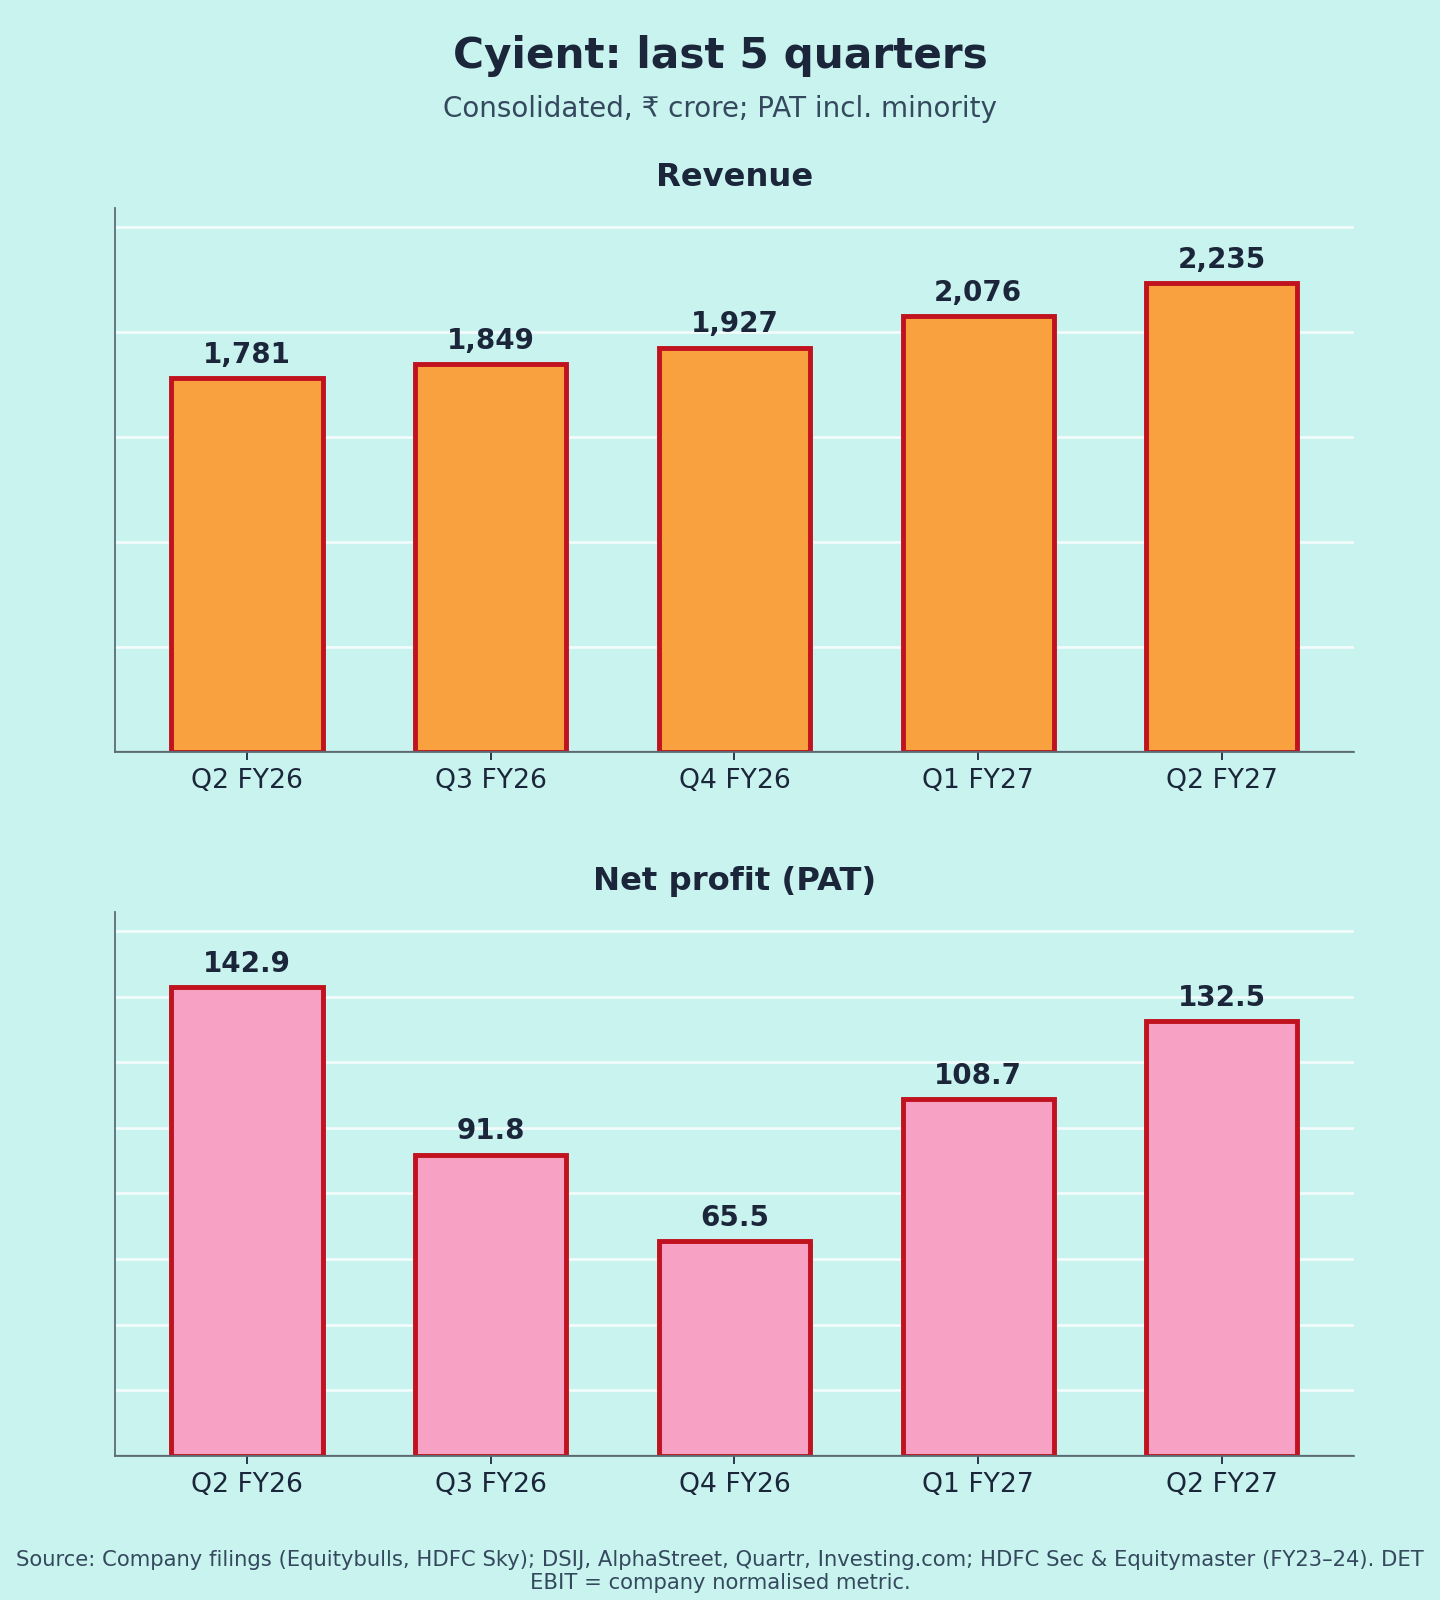
| Revenue from ops | 2,235 | +25.5% | +7.7% |
| EBITDA (ex-OI) | 312 | ||
| EBITDA margin | 14.0% | – | |
| Group EBIT margin | ~10.1% | ~9.4% | 9.0% |
| PBT | 196.7 | flat | +15.0% |
| PAT (owners) | 121.4 | −4.8% | +16.6% |
| PAT margin (owners) | 5.4% | 7.2% | 5.0% |
| Other income / PBT | 4.4% | 25.4% | 4.0% |
Sources: [1][2][3][4].
Source notes:
- Group EBIT is 10.09% per ScanX [3] and 10.2% (+83 bps YoY) per the investor presentation [4].
- Total PAT incl. minority is ₹132.5 cr. Some outlets headline "PAT +22%", which is the QoQ change on that line [5].
- Q3 FY26 PAT varies by source (₹91.8–99.5 cr) [6][7].
Quality of earnings
Revenue +25% looks strong, but PBT was flat (₹196.7 cr vs ₹196.6 cr) [1].
- Growth is mostly acquired. Organic DET revenue grew just 0.4% YoY in constant currency [8]. TAO Digital added $9.6m in its first month, and Kinetic another ~$11.9m [8].
- Other income collapsed to ₹8.6 cr from ~₹50 cr a year ago (my calculation from total income [1]). Cash went to the ₹720 cr buyback and acquisitions [9].
- Tax rate is high at ~33% (₹64 cr on ₹197 cr PBT) [1].
- Base flattered: Q2 FY26 included a ₹20.7 cr insurance-claim exceptional gain [10].
Profit missed the ₹154 cr estimate [3].
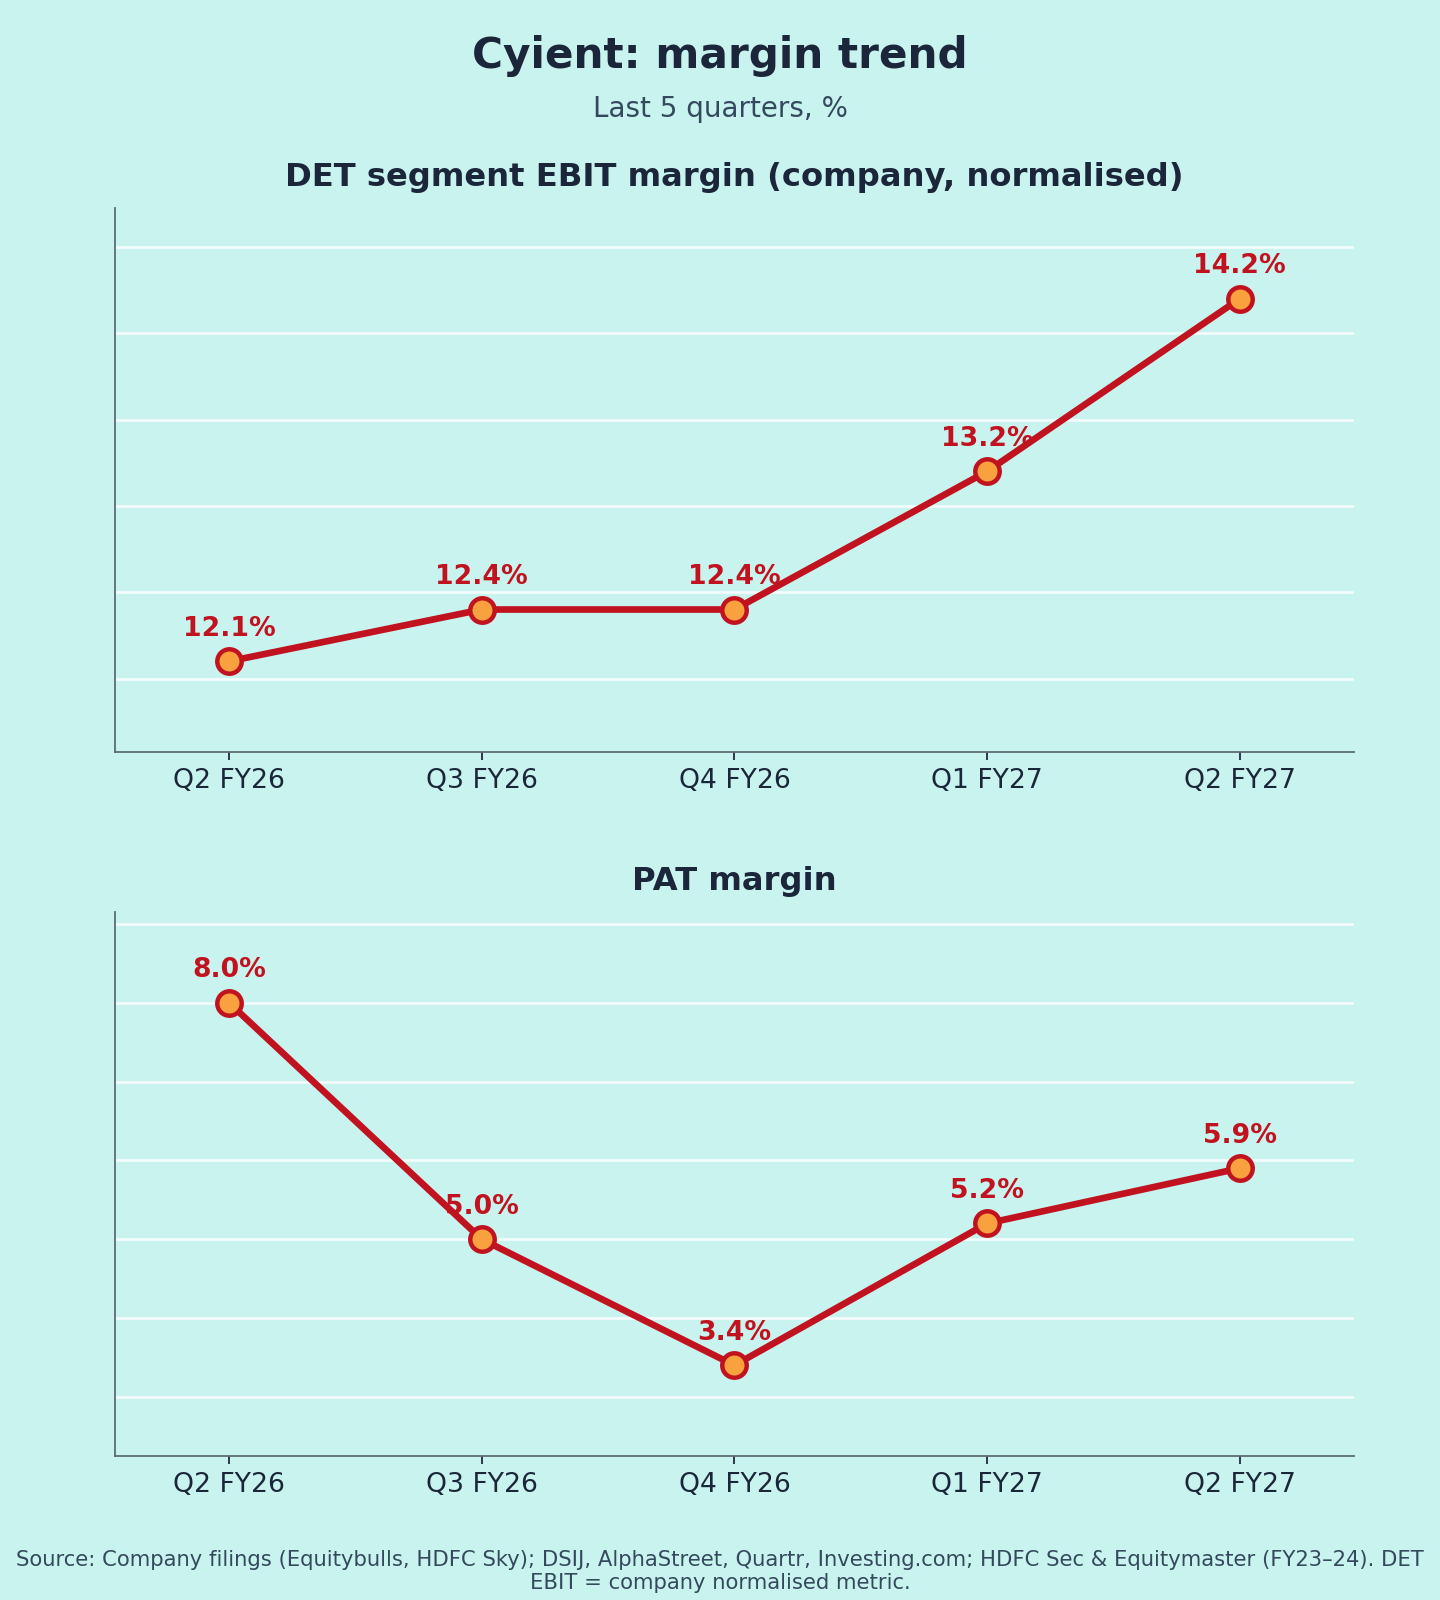
Margins (Chart 3)
DET (core services) EBIT margin: 12.1% → 12.4% → 12.4% → 13.2% → 14.2%, a 10-quarter high [8][11][12]. TAO Digital is accretive to margins [8]. Group margin is lower because of DLM and semiconductor R&D [4].
Guidance: what changed
- 15% DET EBIT margin target: reiterated for Q4 FY27 in January [11]. In July it was deferred to H1 FY28 because revenue ramped slower [12]. Q2's 14.2% puts it within reach, helped by TAO (my view).
- Order intake: highest-ever Q2 order intake; DET order intake +20.8% YoY [13][14].
- Capital moves: buyback completed, TAO closed [8]. Board approved buying the remaining 49% of Cyient Solutions and Systems [3].
Positives
- DET EBIT margin at a 10-quarter high [8]
- Record Q2 order intake [13]
- Semiconductor business growing [4]
Concerns
- Organic growth near zero [8]
- PBT flat despite 25% revenue growth [1]
- Integration risk with two acquisitions in a short span (my view)
- High tax rate and low other income [1]
Things to track in Q3 FY27
- Organic constant-currency growth in DET
- DET EBIT margin vs the 15% target (now H1 FY28)
- Full-quarter TAO contribution
- Order intake converting into revenue
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Equitybulls – Q2 FY27 filing detail · [2] Equitybulls – Q2 FY26 · [3] ScanX · [4] InvestyWise – presentation · [5] NewsBytes · [6] AlphaStreet – Q3 FY26 · [7] 5paisa – quarterly · [8] Investing.com – call transcript · [9] Angel One – Q4 FY26/buyback · [10] FilingReader – Q2 FY26 · [11] MOSL Q3 FY26 note (BS) · [12] Quartr – Q1 FY27 · [13] Kotak Neo · [14] InvestyWise – release · [15] DSIJ – Q4 FY26 · [16] HDFC Sky – Q2 FY26 · [17] HDFC Sec / Equitymaster
Charts:
(1) last 5 quarters revenue & total PAT [1][6][15][16];
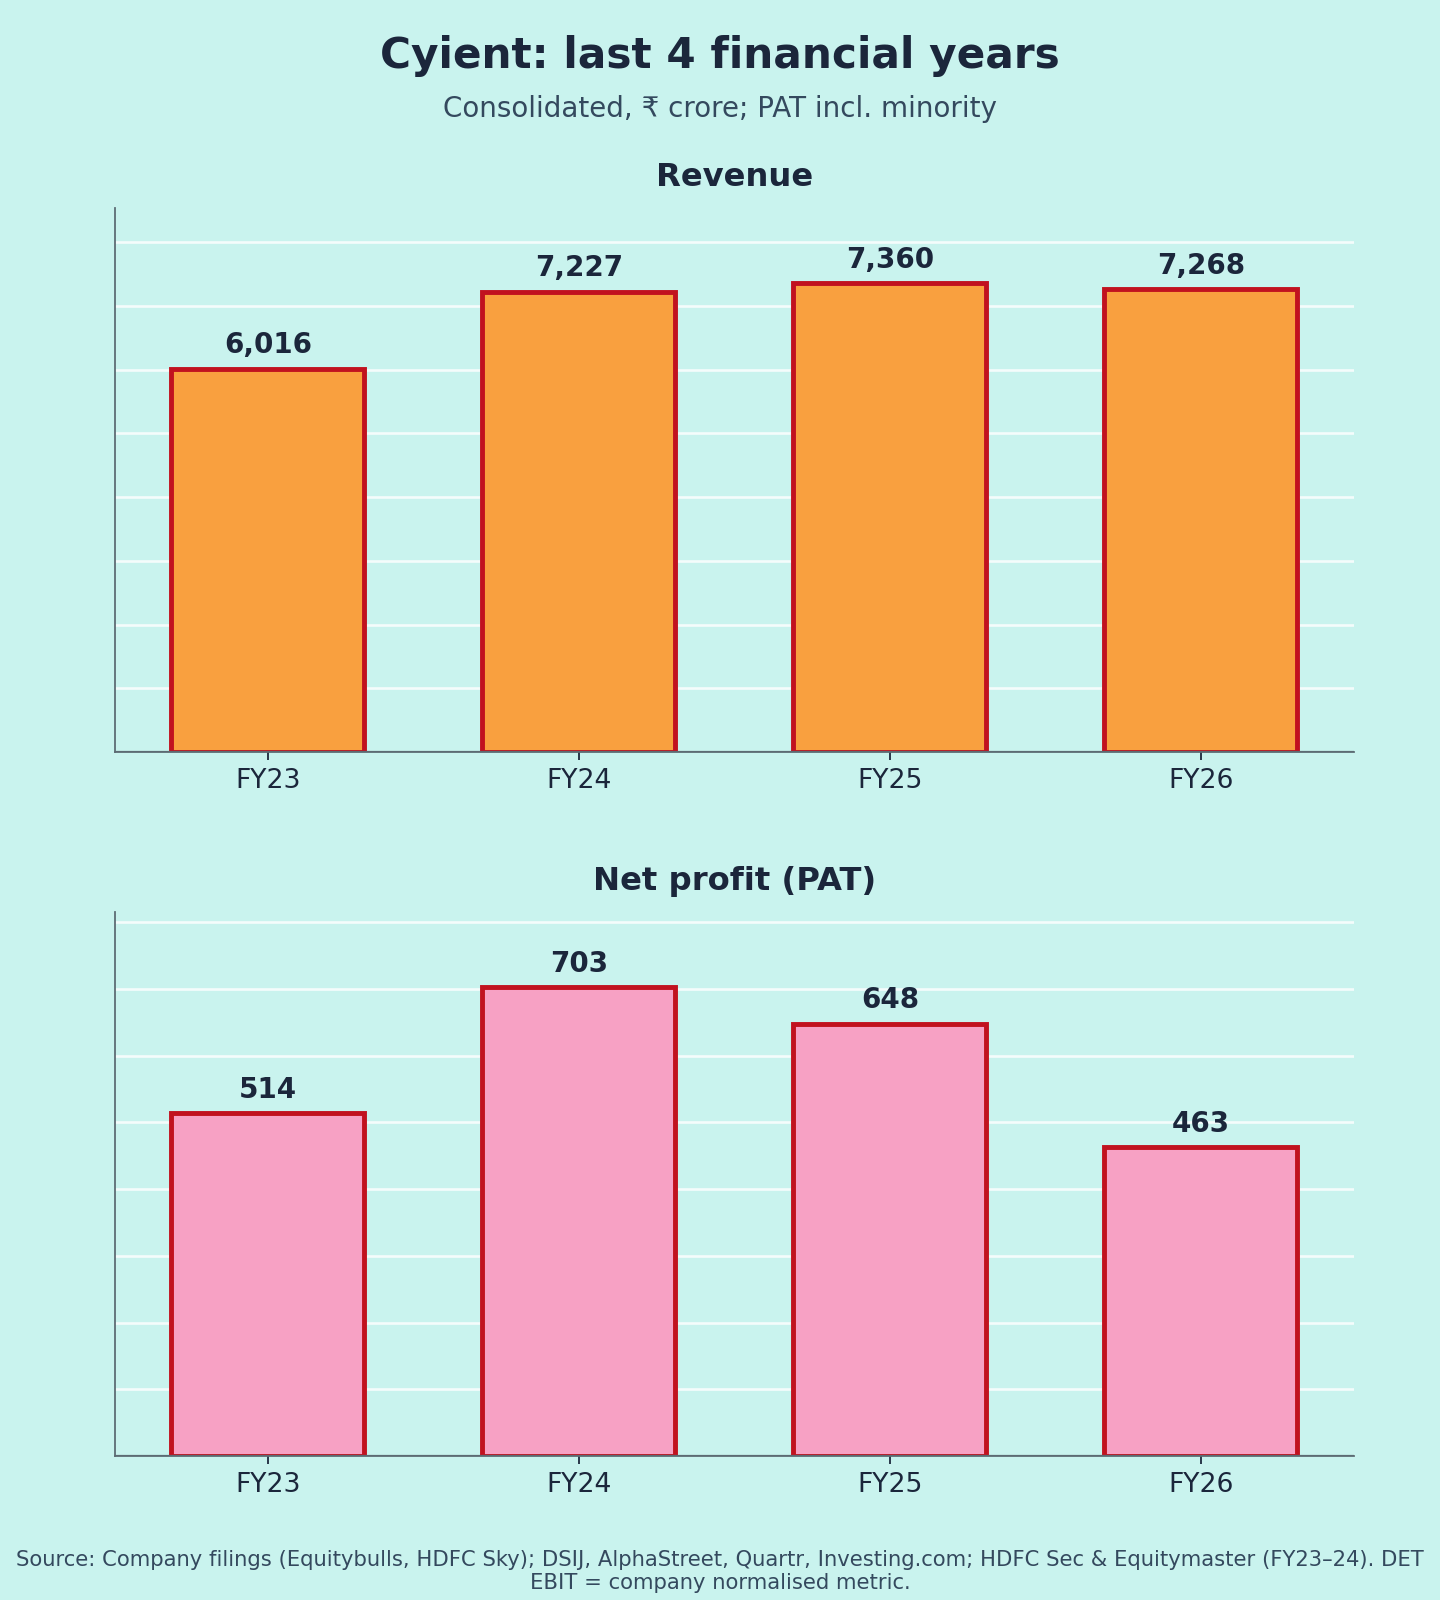
(2) FY23–FY26 revenue & PAT [15][17] (FY24 revenue = Equitymaster total revenue);
(3) DET EBIT margin [8][11][12] and total-PAT margin (own calc.).