TVS Motor Company — Q2 FY27 Results Analysis
Quarter ended 30 September 2026 | Results announced 28 October 2026
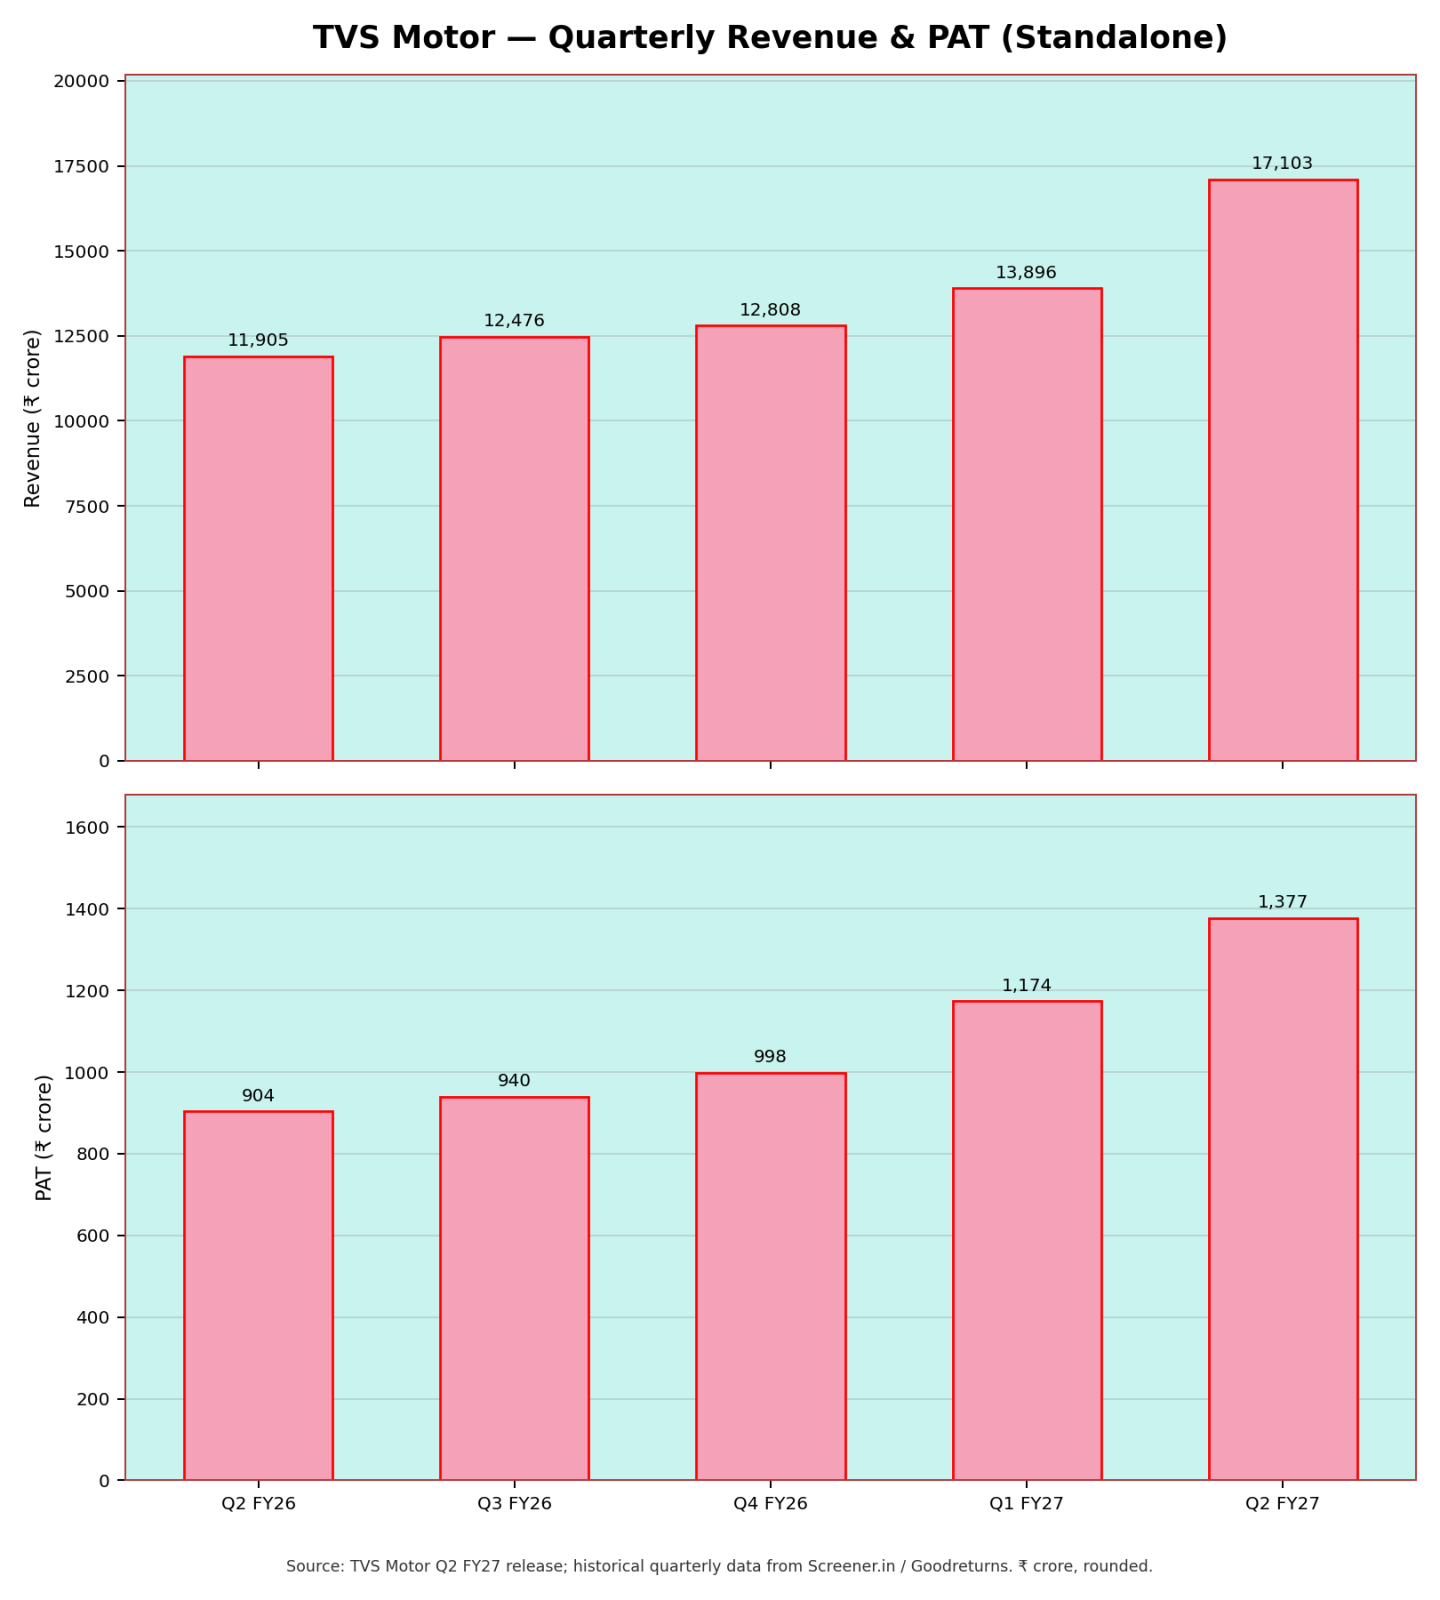
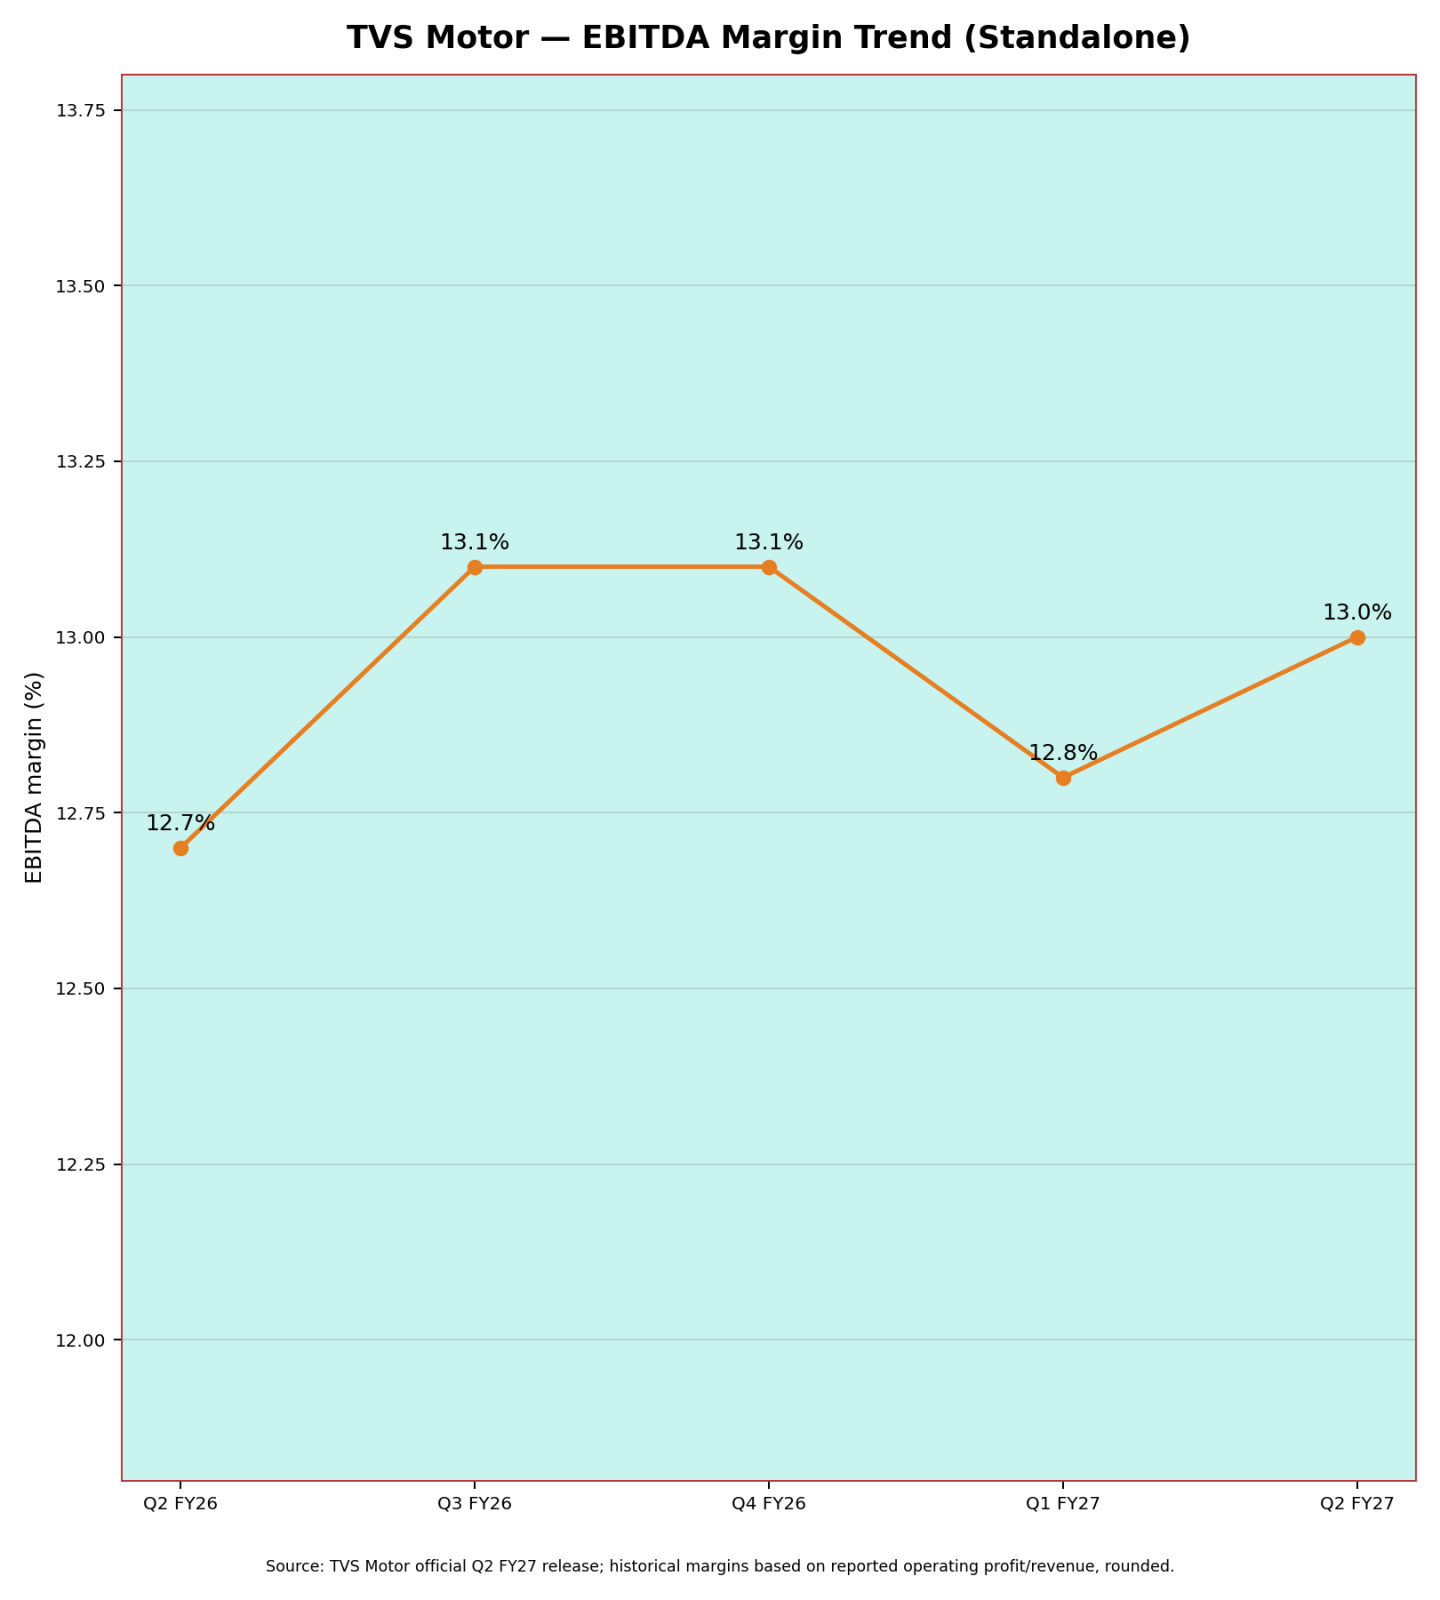
TVS Motor reported record quarterly revenue, operating profit and net profit. Revenue grew 44% year-on-year to ₹17,103 crore, while profit after tax (PAT) increased 52% to ₹1,377 crore. EBITDA margin improved to 13.0% from 12.7%. These headline figures are from the company's official results announcement.
1. Key financial numbers
Basis: standalone results. Amounts are in ₹ crore.
| Metric | Q2 FY27 | YoY change | QoQ change |
| Revenue | 17,103 | +43.7% | +23.1% |
| EBITDA | 2,219 | +47.2% | Not verified |
| EBITDA margin | 13.0% | +0.3 percentage points | Not verified |
| PAT | 1,377 | +52.4% | +17.3% |
| PBT | 1,865 | +52.4% | Not verified |
Source: Company press release and reported quarterly financial figures. QoQ comparisons use Q1 FY27.
2. What drove the results?
Facts: Total two- and three-wheeler sales reached 1.9 million units, up 27%. International business grew 35%, while two-wheeler EV sales increased 133% to 186,186 units. EBITDA grew faster than revenue, lifting the operating margin by 30 basis points.
Analysis: This looks like a strong operating quarter, not just a profit increase caused by other income. However, other income, tax and any exceptional items need to be checked against the detailed results statement before drawing a firm conclusion about the quality of the entire PAT increase. The company’s strong year-on-year growth also needs to be viewed alongside the possibility of a higher industry base after the GST-related changes last year.
3. Management outlook
Management expects the two-wheeler and three-wheeler industries to grow at a single-digit rate in the second half, partly because the comparison base becomes tougher. EV momentum is expected to continue. The company plans to balance selective price increases, material-cost reduction and product mix to protect margins. It also expressed confidence in continuing to outperform the industry.
4. Positives, concerns and what to watch
Positives
- Record revenue and PAT, with profit growing faster than sales.
- Strong export, EV and three-wheeler growth.
- Better operating margin despite rising material costs.
Concerns
- Commodity-cost increases could limit future margin improvement.
- Industry growth may slow in H2 as the comparison base rises.
- EV growth needs to translate into sustainable profitability, not just higher volumes.
Track next quarter
- Whether EBITDA margin stays near 13%.
- Domestic demand, exports and EV sales growth.
- Commodity costs versus price increases.
- Actual results versus management’s single-digit industry-growth outlook.
Conclusion — Opinion: TVS Motor delivered a strong quarter, with broad-based volume growth and improved operating profitability. The key test now is whether it can maintain margins and outperform the industry when overall market growth moderates.
Primary sources: Official Q2 FY27 results release · Official investor relations page · Q2 FY27 earnings-call coverage.