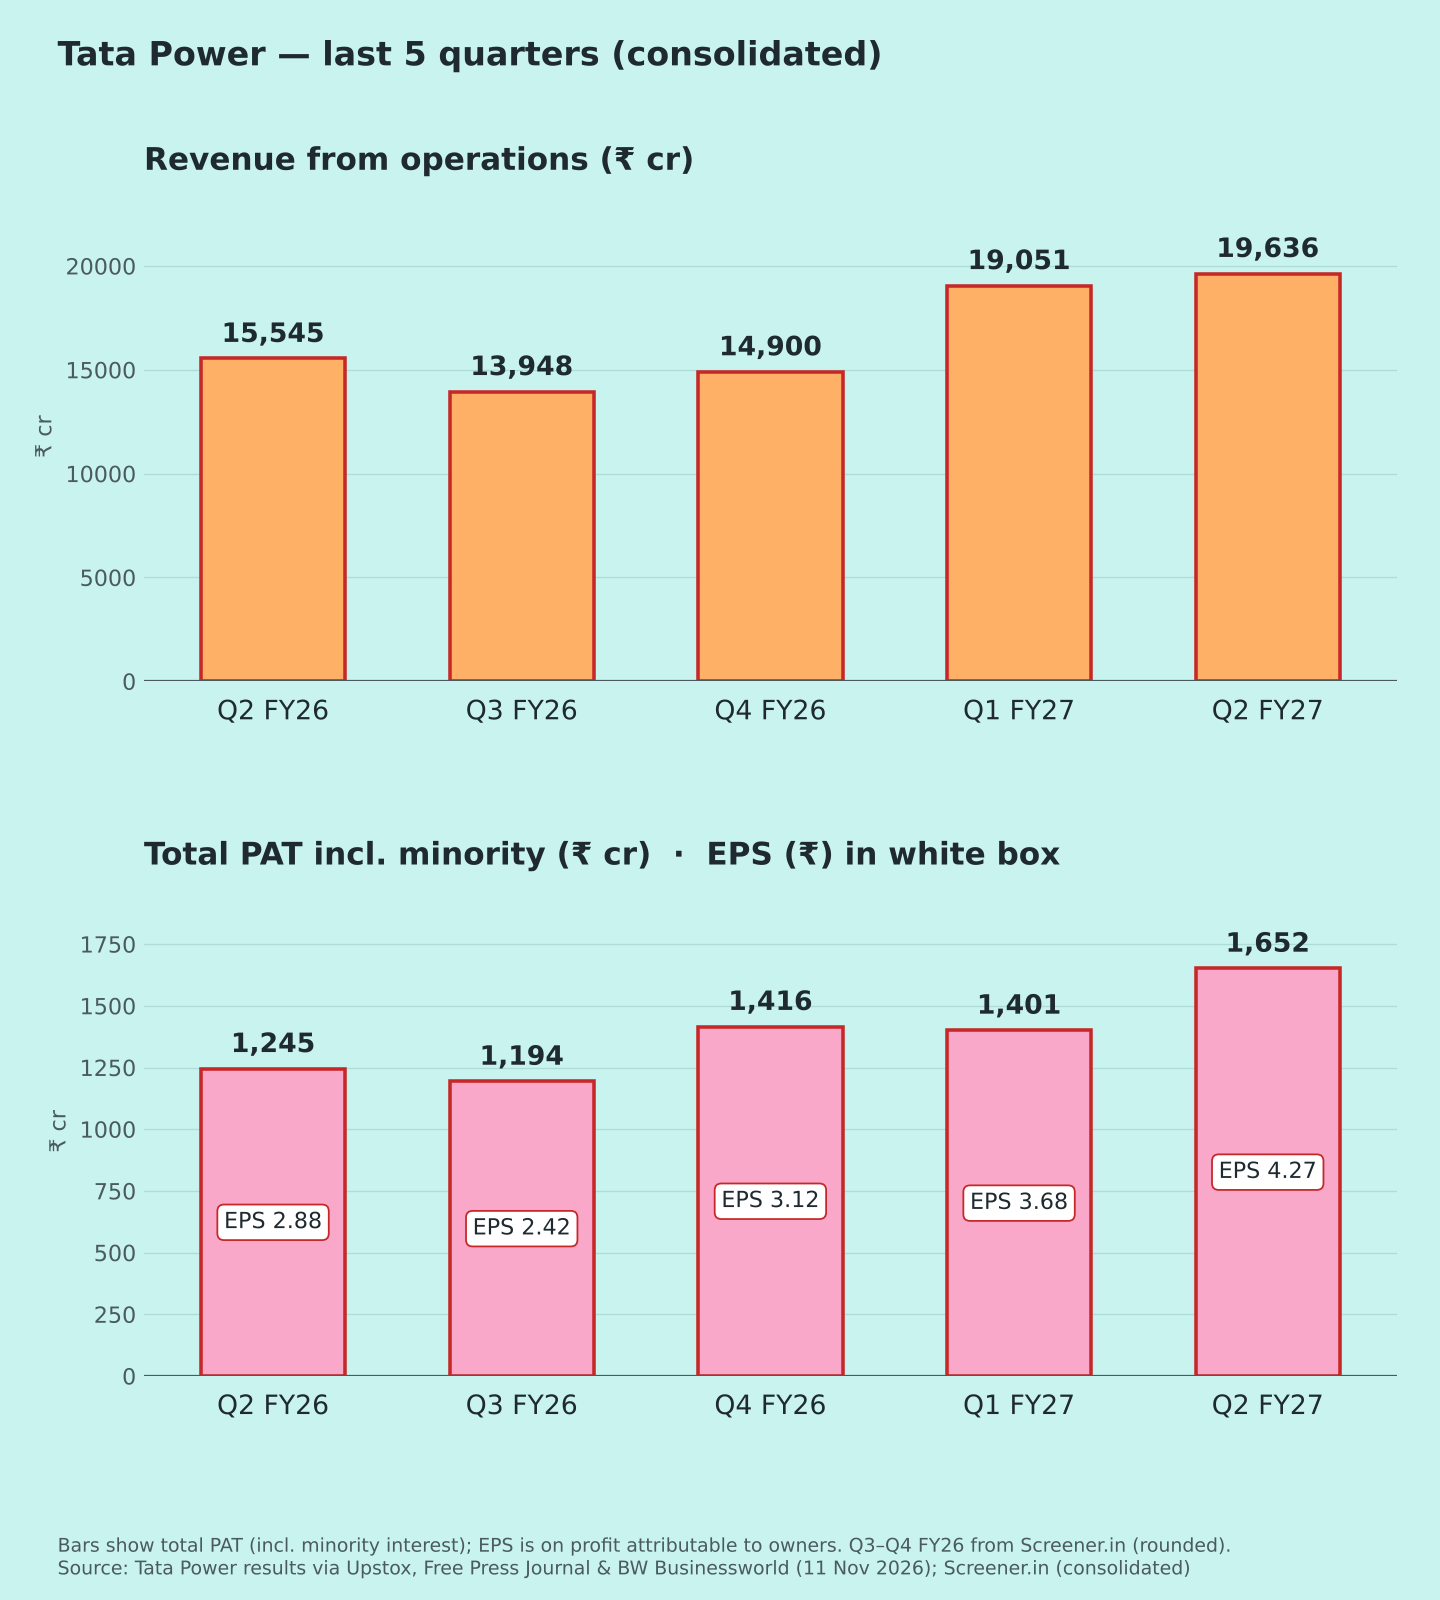
Consolidated figures, ₹ crore. Results announced 11 Nov 2026.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 19,635.9 | +26.3% | ≈+3.1% |
| EBITDA | 3,668 | ≈+11% | ≈−5% |
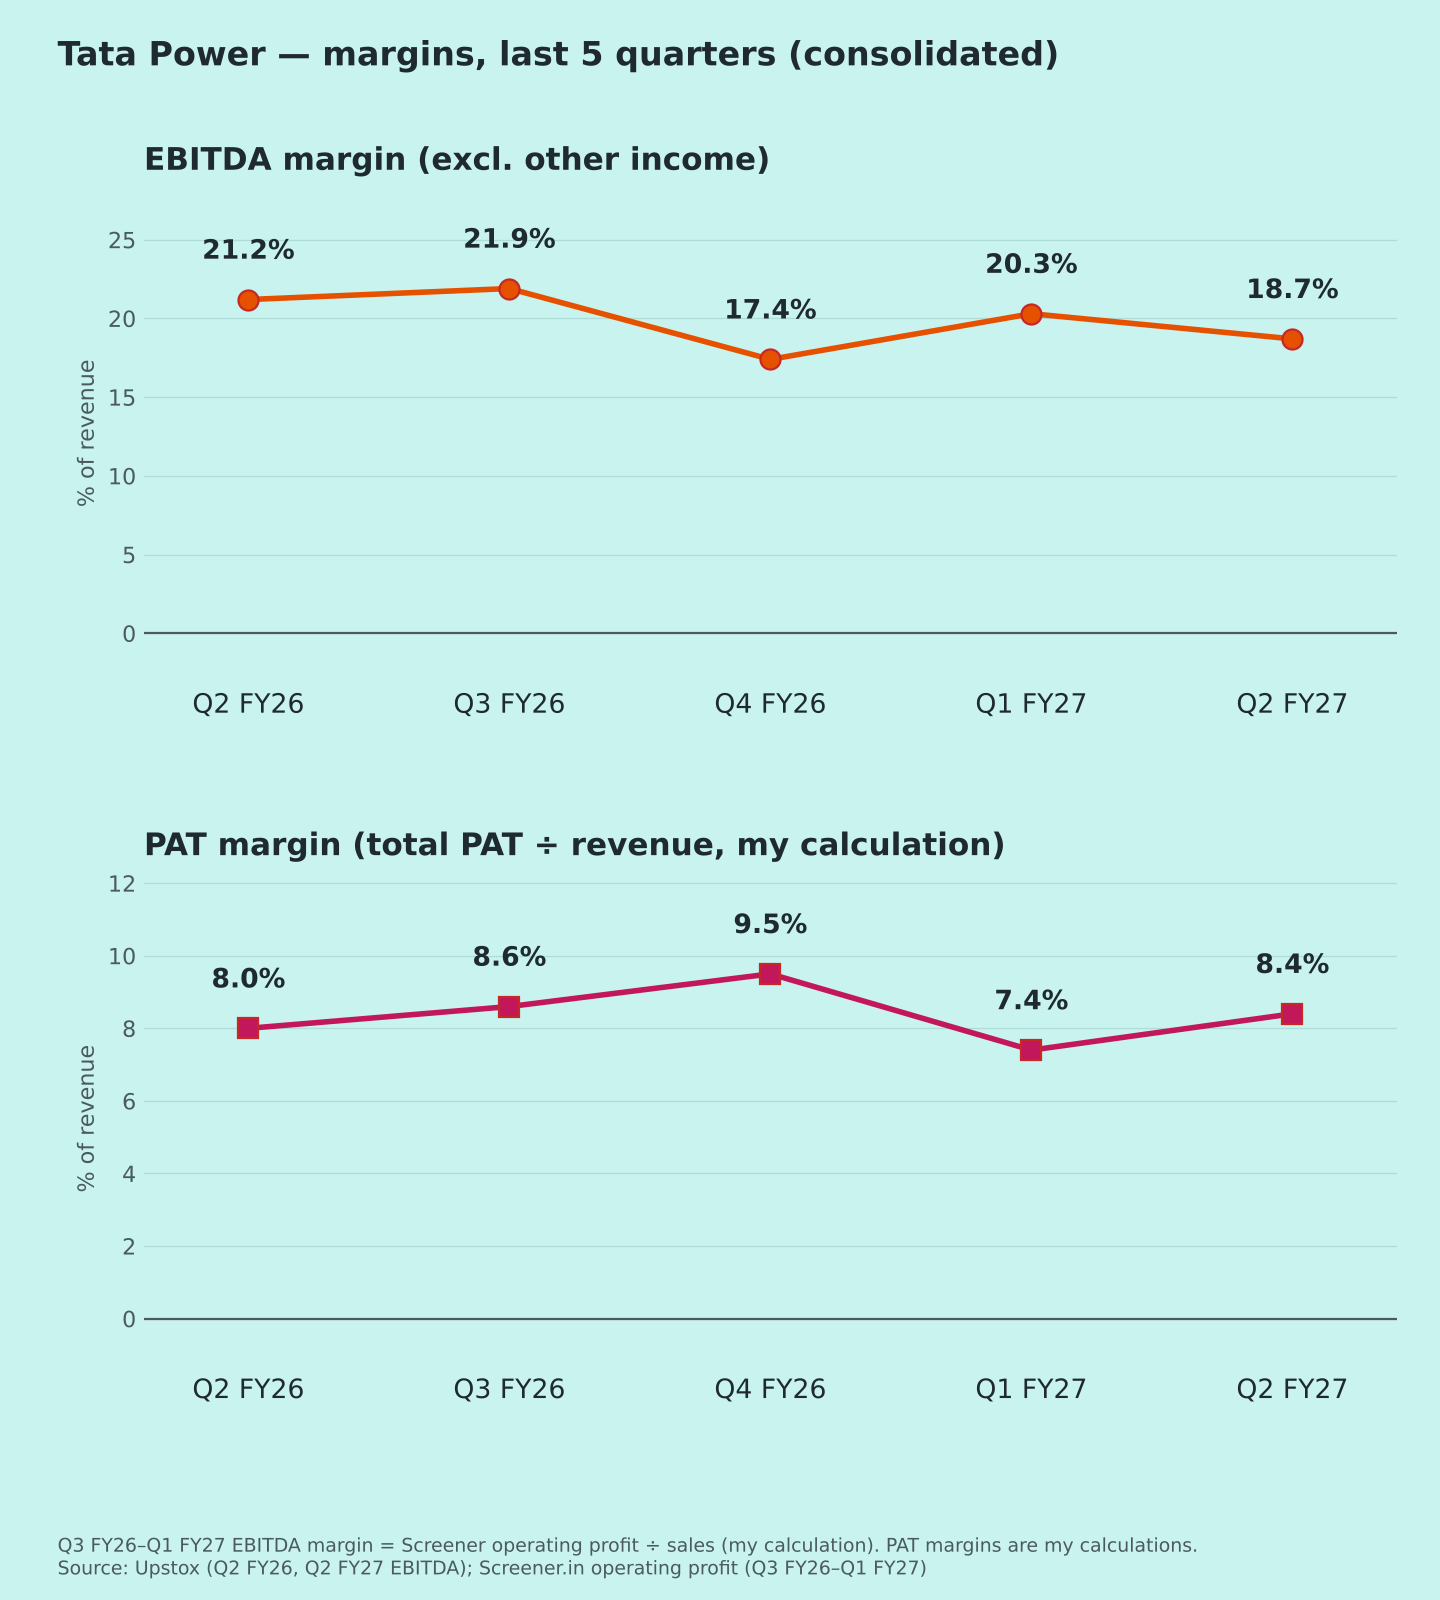
| EBITDA margin | 18.7% | 21.2% | ≈20.3% |
| Other income (≈) | ≈328 | ≈505 | — |
| PBT | 2,179.9 | ≈+30% | ≈+20% |
| PAT, total | 1,652.0 | +32.6% | ≈+17.9% |
| PAT to owners | 1,366.1 | +48.6% | ≈+16.2% |
| PAT margin (owners) | 7.0% | 5.9% | 6.2% |
| EPS (₹) | 4.27 | 2.88 | 3.68 |
Margin, other income and EPS rows show year-ago and last-quarter values. ≈ = my calculation; Q1 FY27 = H1 minus Q2; Q1 EBITDA from Screener. "—" = Q1 other income not available on the same basis.
Source note: Free Press Journal's headline uses total PAT ("+33% to ₹1,652 cr"); Upstox and others use owners' PAT ("+49% to ₹1,366 cr") [1][2][3]. Both are right; they measure different things.
Quality of earnings
- Operating profit was flat. Profit before regulatory items, JV/associate share, one-offs and tax was ₹1,323.7 cr vs ₹1,326.7 cr a year ago [2]. The PBT growth came from items below that line (my calculation).
- One-off: a net exceptional gain of ₹119.2 cr: a ₹317.4 cr gain from no longer treating Tata Projects as an associate, less ₹198.2 cr of impairments [2][3]. Without it, owners' PAT is roughly ₹1,250 cr, still about +36% (≈, my calculation, assuming no tax on the gain).
- Pass-through revenue: fuel cost jumped to ₹4,633 cr from ₹1,347 cr [2]. The Mundra plant has run under a government order since April [3], and thermal & hydro revenue rose 2.5x. That inflates revenue and lowers the margin %, though EBITDA still rose ~11% (my view).
- Why owners' PAT grew faster: the minority share fell to ₹286 cr from ₹326 cr (my calculation).
Margins (Chart 3)
EBITDA margin: 21.2% → 21.9% → 17.4% → 20.3% → 18.7% [1][4].
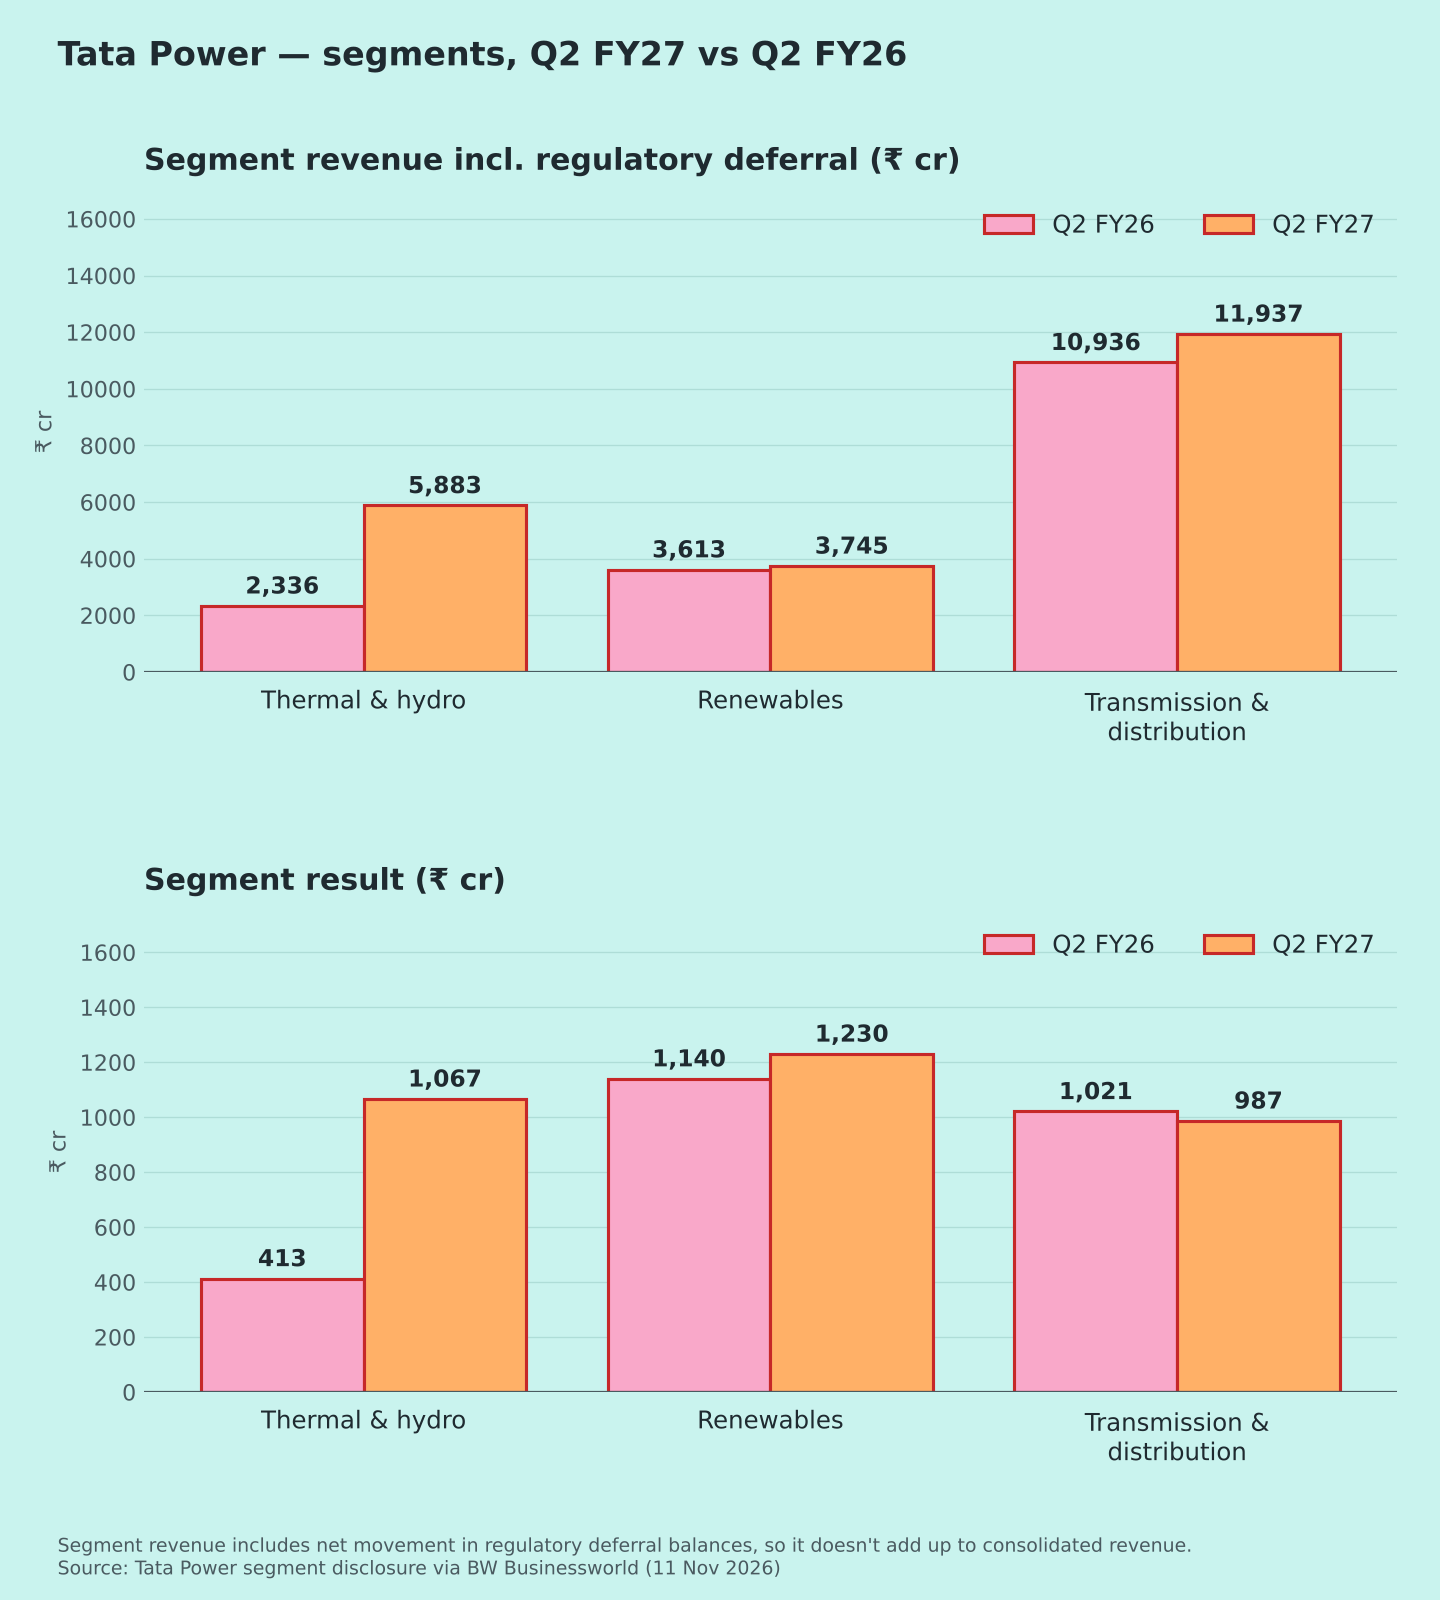
Segments (Chart 5) [3]
- Thermal & hydro: result ₹1,067 cr vs ₹413 cr.
- Renewables: ₹1,230 cr vs ₹1,140 cr (+8%).
- Transmission & distribution: ₹987 cr vs ₹1,021 cr (−3%).
Key risk: Singapore arbitration
An arbitration award of USD 490 mn plus interest stands against Tata Power. On 6 Nov a court sheriff served attachment notices on its shares in some Singapore subsidiaries. The company has appealed; no provision has been made, and the auditor drew attention to it [2][3].
Other: board approved the 1,800 MW Shirwata pumped-storage project (₹11,871 cr) [1]. H1 capex about ₹10,000 cr; debt-to-equity 1.62x vs 1.58x [1][3]. No numeric guidance in coverage.
Positives
- Owners' PAT +49% [1]
- Renewables profit growing [3]
Concerns
- Flat operating profit before regulatory items (my calculation)
- Arbitration exposure without provision [2]
- Rising debt [3]
Things to track in Q3 FY27
- Singapore appeal outcome (submissions due 23 Nov)
- Mundra operating order (extended to 31 Dec 2026) [3]
- EBITDA margin
- Renewables capacity additions
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Upstox – Q2 results · [2] Free Press Journal – Q2 results · [3] BW Businessworld – Q2 results & segments · [4] Screener.in – consolidated · [5] InvestyWise – results
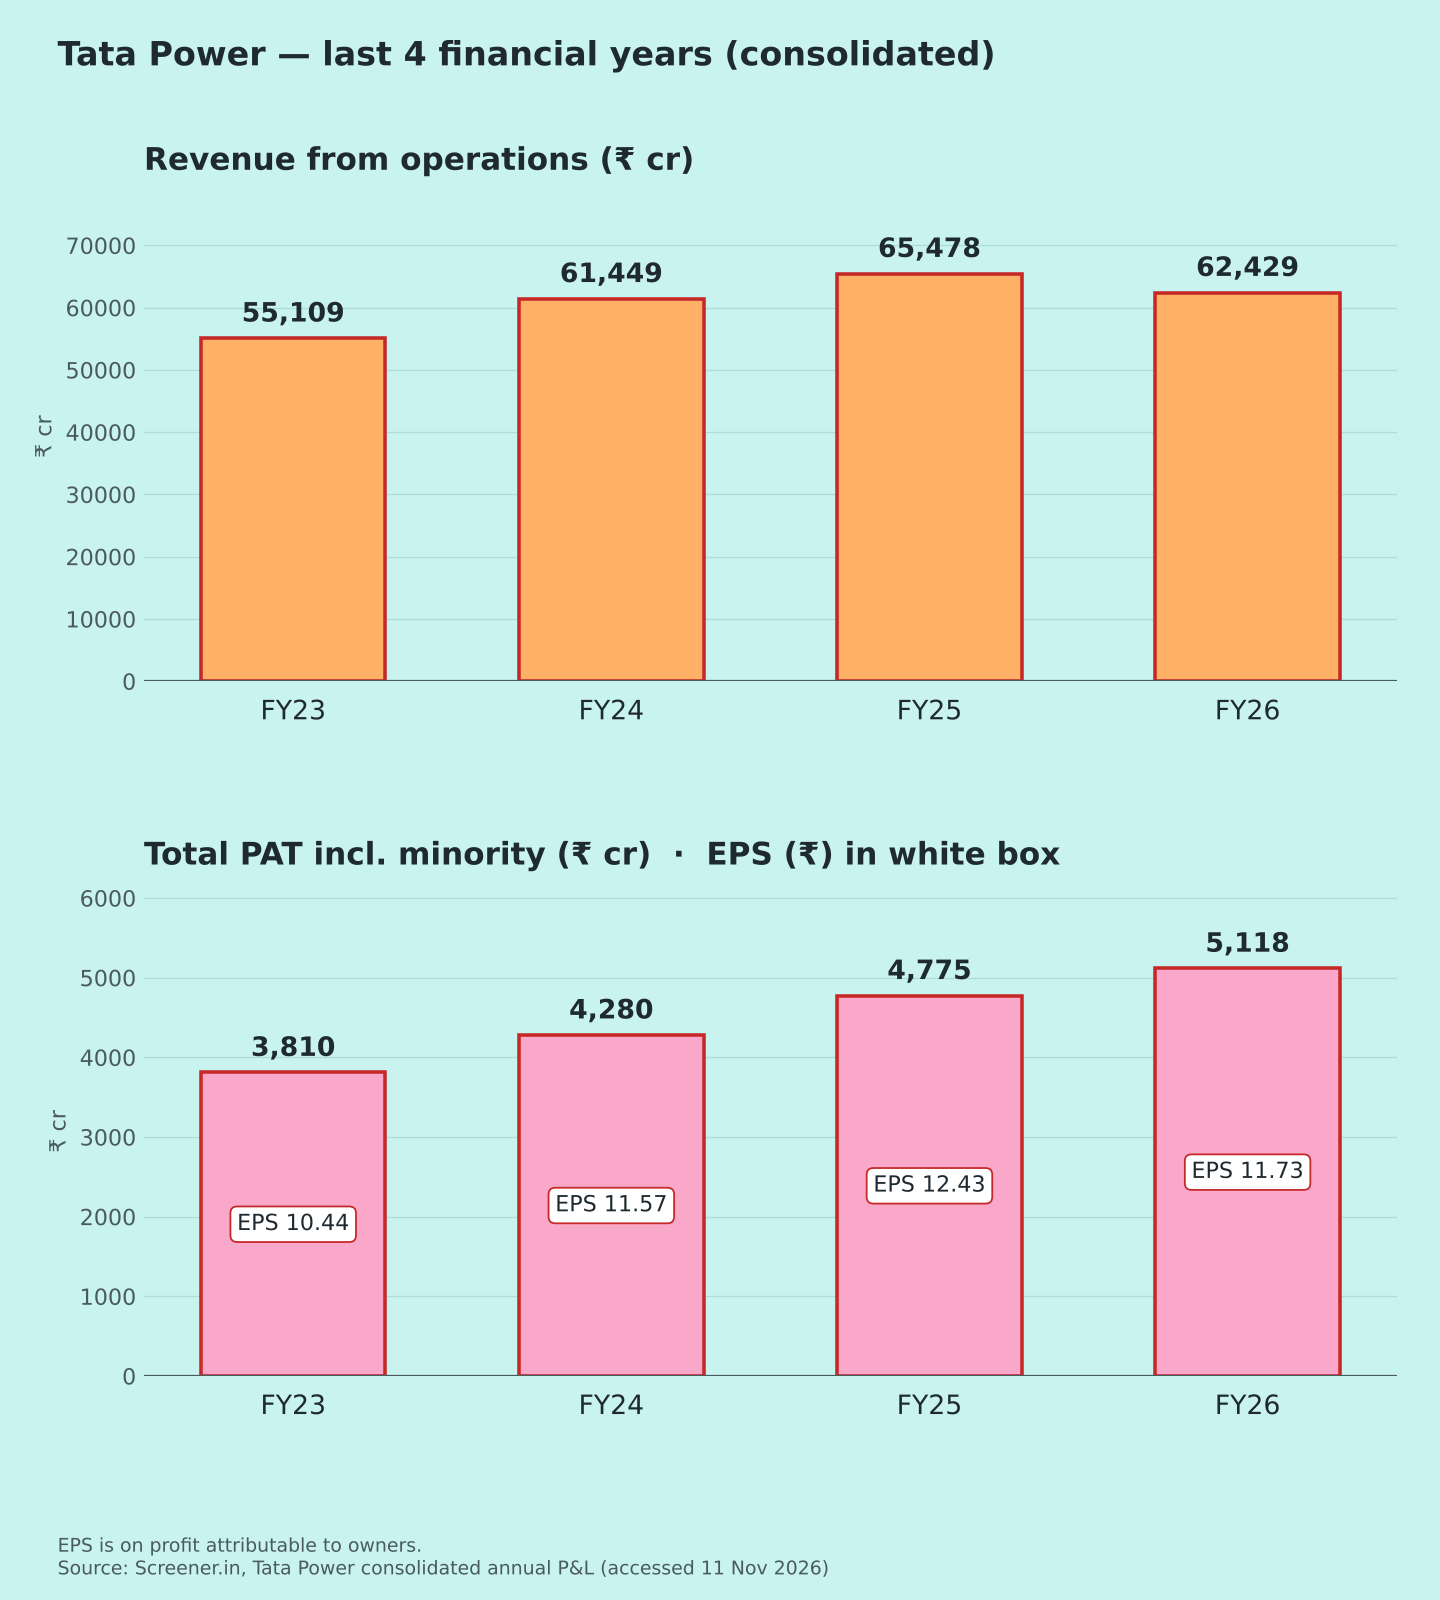
Charts: (1) 5 quarters revenue & total PAT with EPS (2) FY23–FY26 [4]; (3) margins [1][4]; (4) segments [3].