Tata Motors Passenger Vehicles Ltd (TMPV): Q2 FY27 results
Tata Motors Passenger Vehicles (TMPV) 1 reply Share on X Share on WhatsApp

Quality of earnings
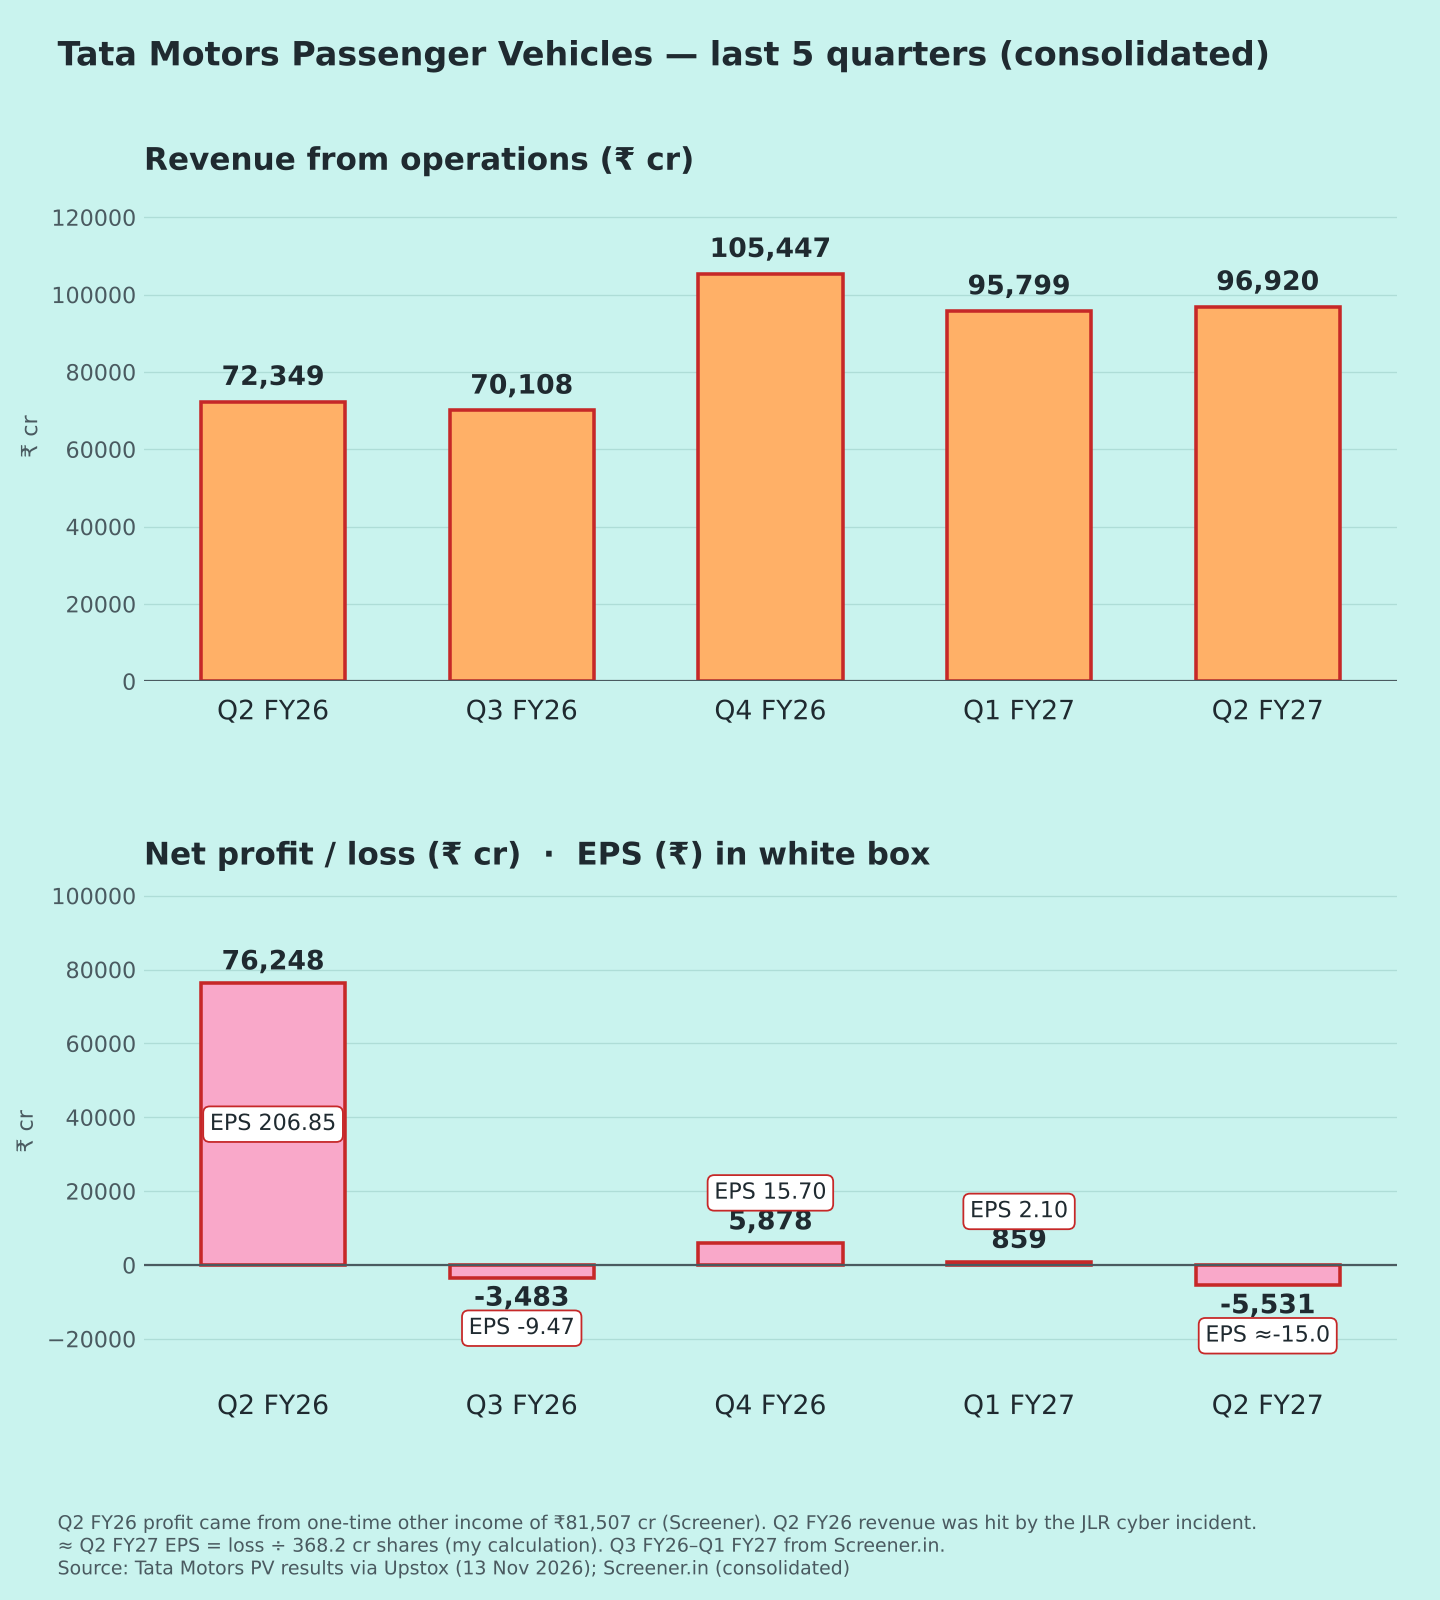
- The loss comes from one-off JLR charges. JLR booked £530 mn of exceptional items: restructuring, separation costs and write-downs of assets and products under development [2]. Before these, JLR made a small profit (£6 mn PBT vs a £485 mn loss a year ago).
- Year-ago figures are distorted both ways. Q2 FY26 revenue was hit by the JLR cyber attack, which flatters this year's 34% growth. Q2 FY26 profit (₹76,170 cr) came from a ₹81,507 cr one-time gain, most likely linked to the demerger (my view). Neither year is a clean comparison.
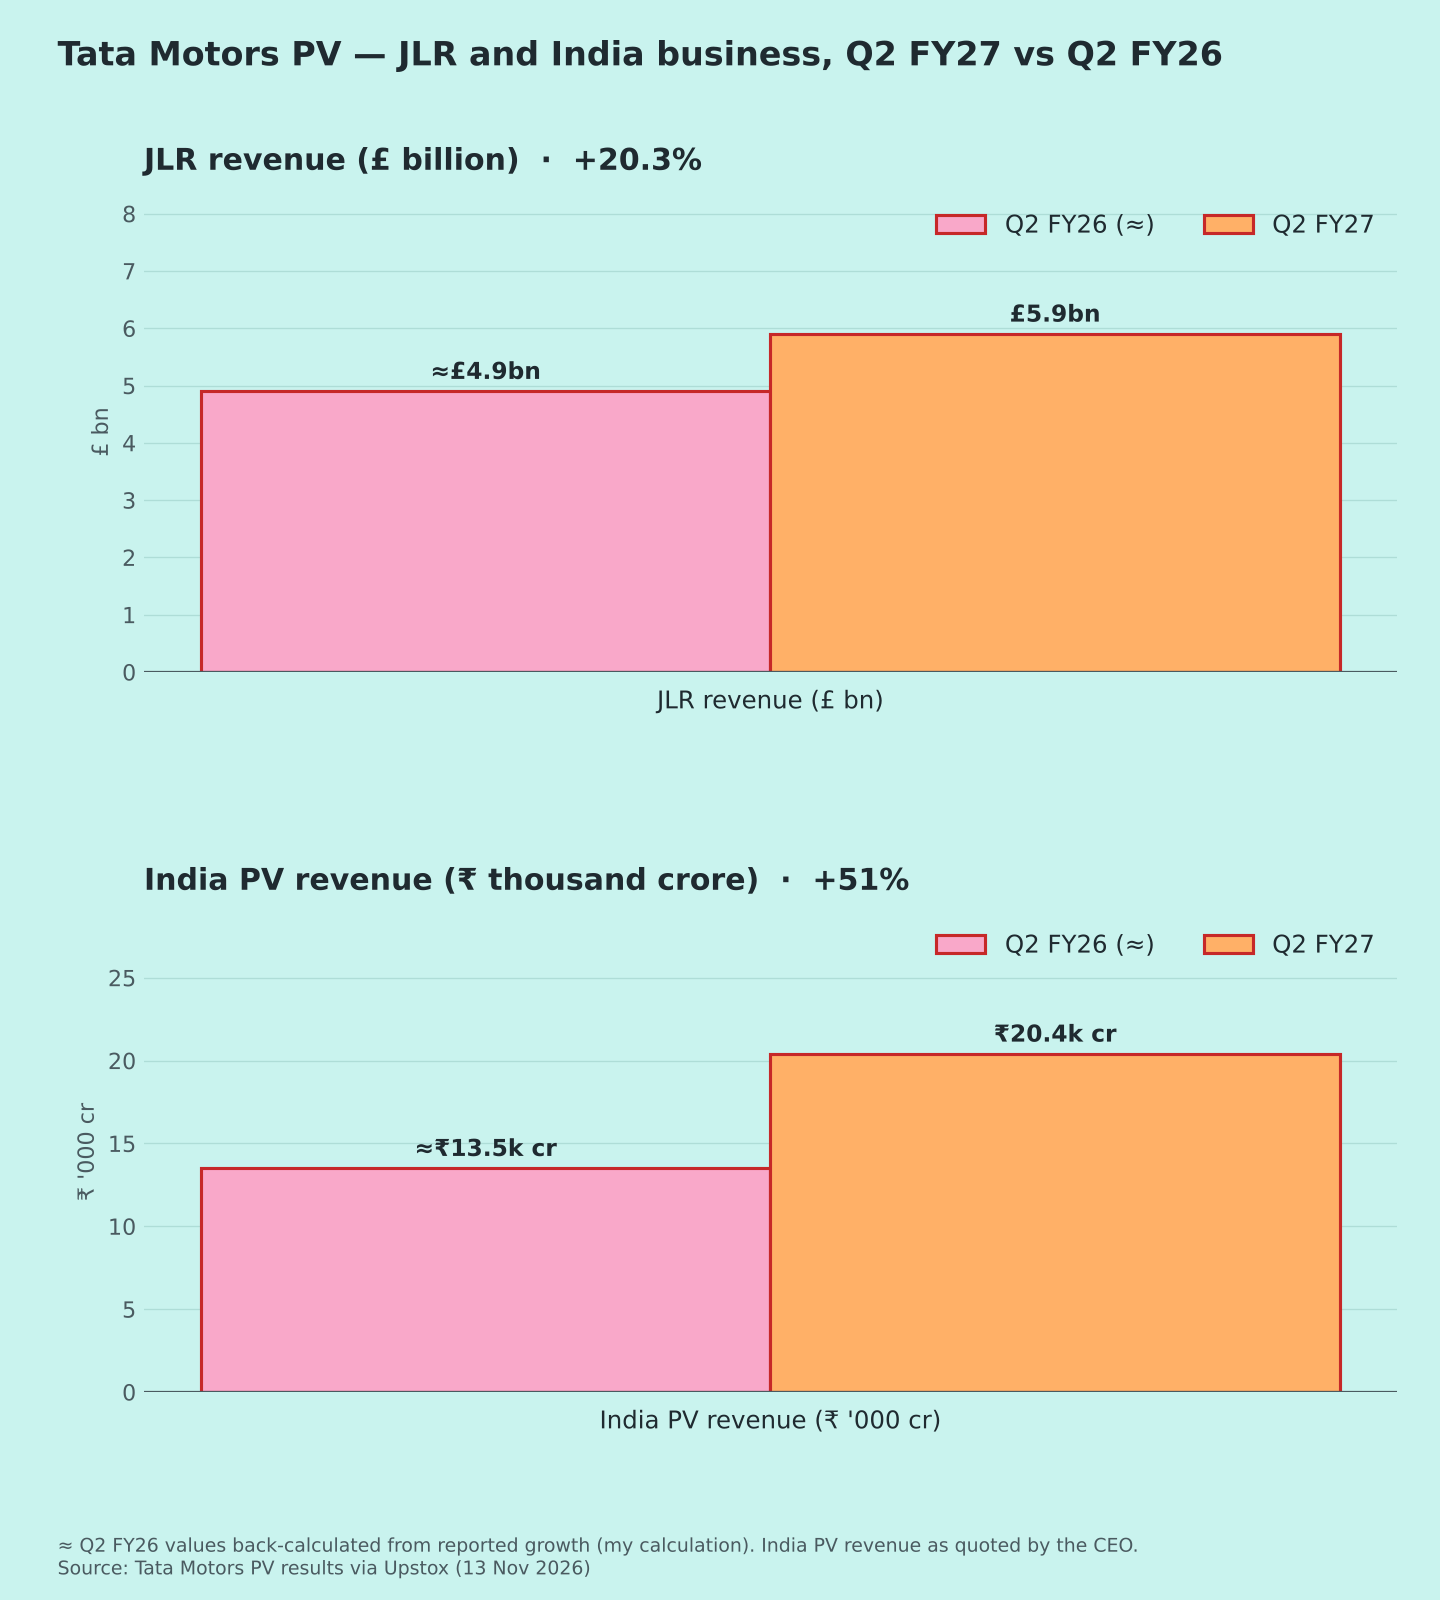
- India business growing fast: revenue ₹20,400 cr (+51%), volumes +40%, electric-vehicle volumes +90%.
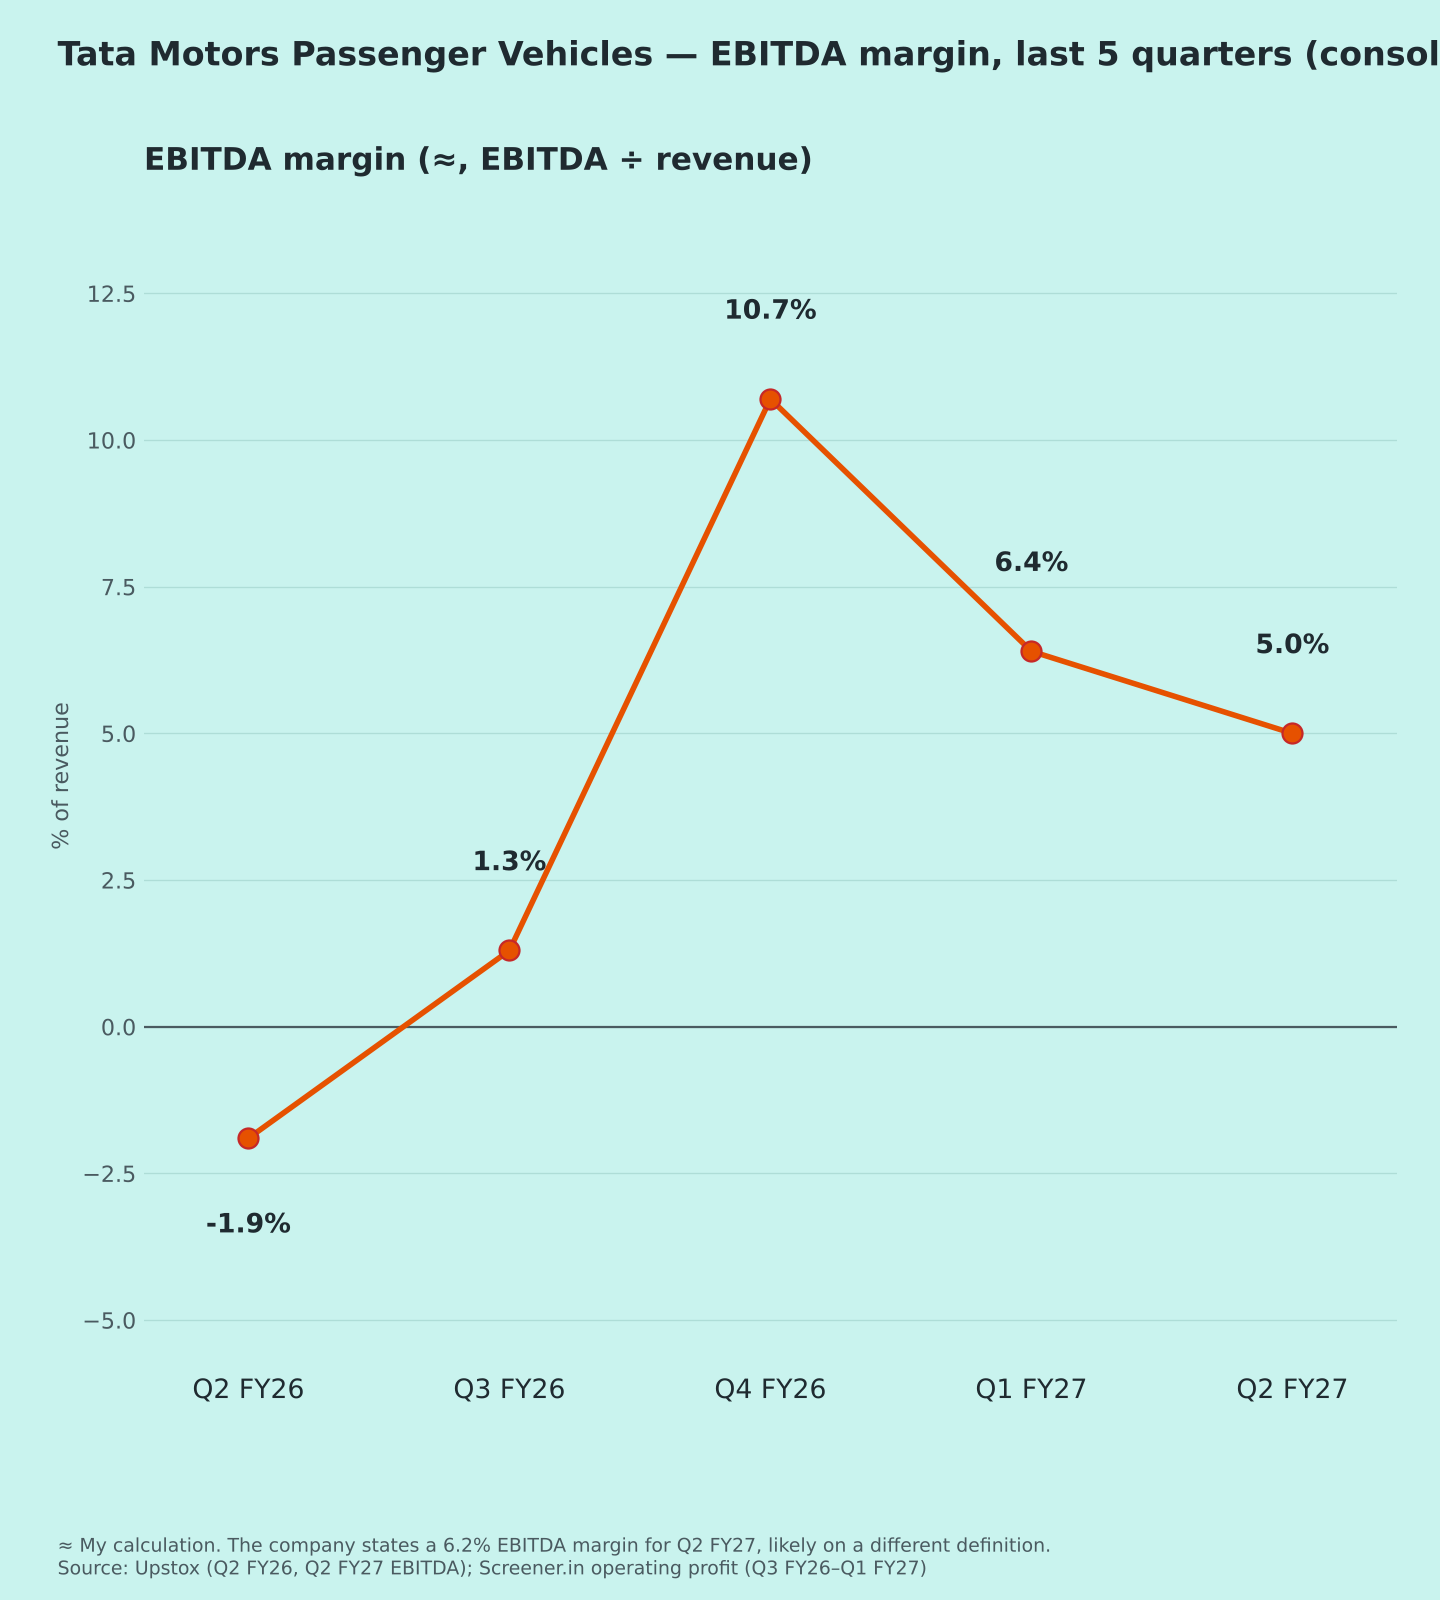
Margins (Chart 3)
EBITDA margin: ≈−1.9% → 1.3% → 10.7% → 6.4% → 5.0% (my calculation).
JLR guidance cut [2]
- FY27 JLR EBIT margin now 2–3%, with free cash outflow of about £1.25 bn, citing market challenges, geopolitics and exceptional costs. Earlier guidance wasn't in coverage.
- Q2 free cash outflow £540 mn; cash £1.8 bn.
Positives
- India PV revenue +51%, EV volumes +90%
- JLR revenue +20% (£5.9 bn)
Concerns
- £530 mn JLR exceptional charges
- JLR guidance reduced, cash outflow expected
Things to track in Q3 FY27
- JLR wholesales and margins
- Cash flow vs the −£1.25 bn guidance
- Further restructuring charges
- India PV and EV market share
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Posts are members’ own views and are not investment advice. Holdings shown are what each member disclosed when posting. Research notes are by SEBI-registered analysts under their own registration; Mudraa hosts them and does not endorse them.
To take part, Log in or Join. Members verify their email and phone and agree to the community rules.