Supreme Petrochem (SPLPETRO): Q2 FY27 results analysis
(quarter ended 30 Sep 2026)
All figures consolidated, ₹ crore unless stated. The board met at 5 PM on 23 Oct 2026, after market hours. YoY/QoQ %, margins and ratios are my calculations. The earnings call is on 27 Oct, so some lines below are flagged as estimates.
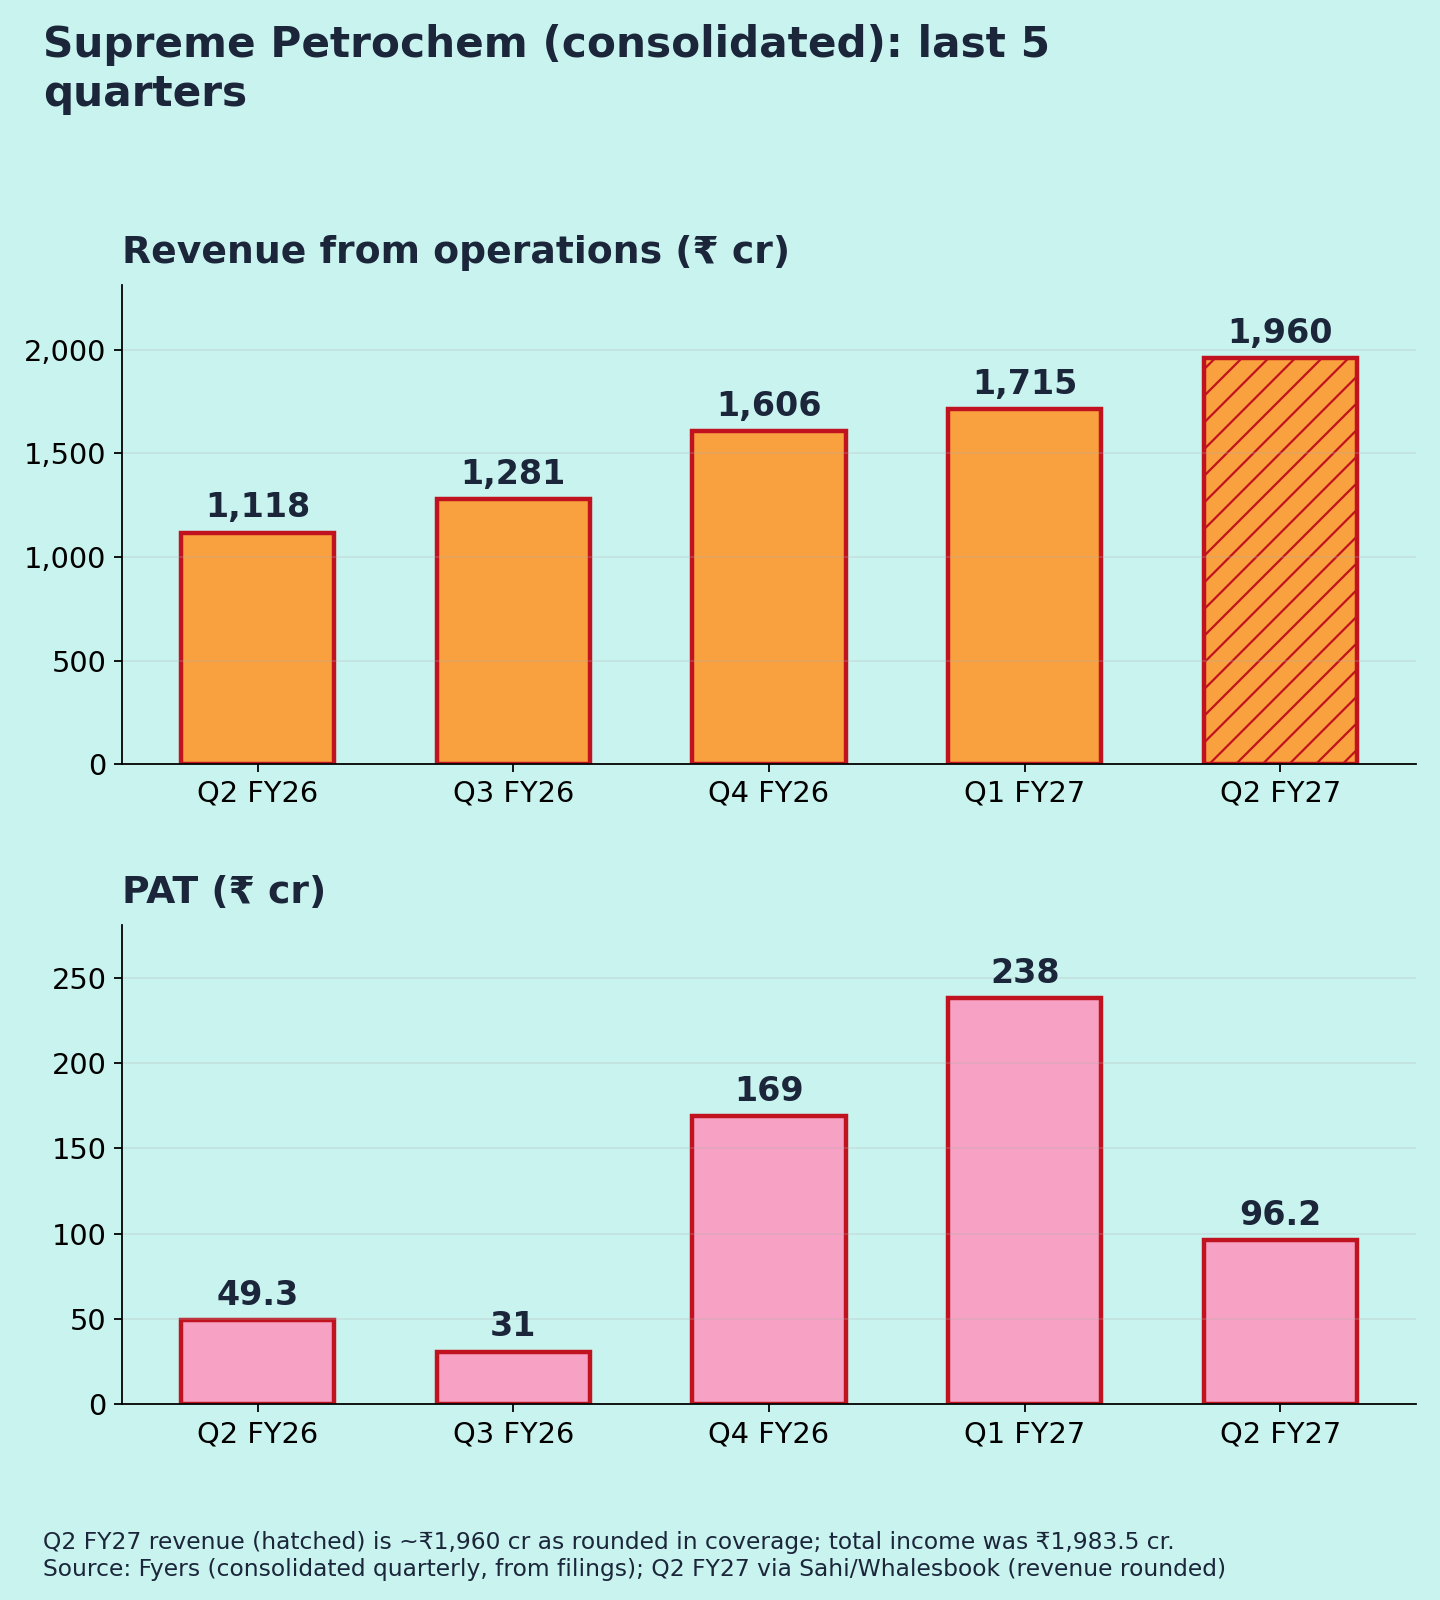
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops (rounded) | ~1,960 | ~+75% | ~+14% |
| Total income | 1,983.5 | +76.1% | +14.5% |
| EBITDA (ex-OI) – estimate | ~137 | ~+76% | ~−59% |
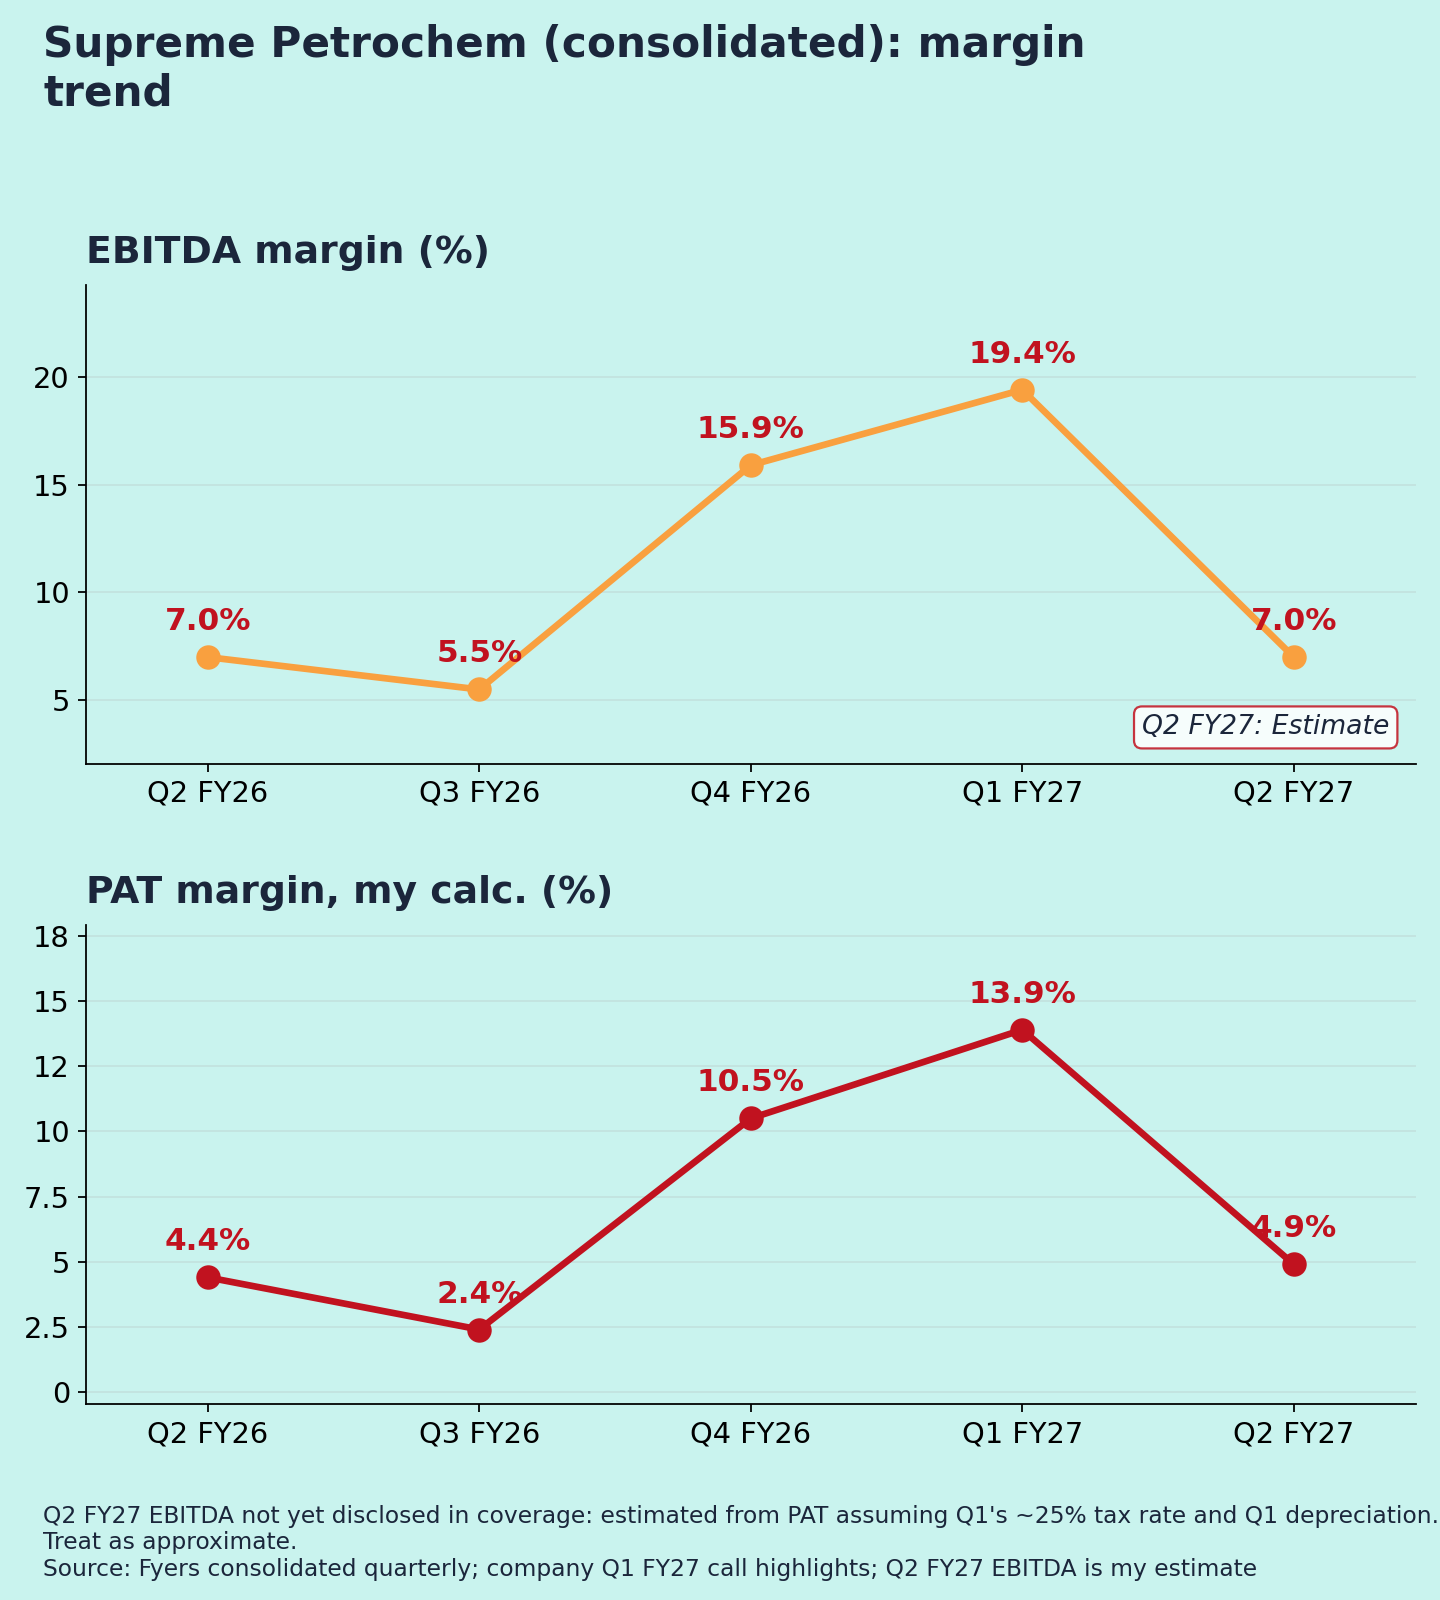
| EBITDA margin – estimate | ~7.0% | 7.0% | 19.4% |
| PAT | 96.2 | +95.2% | −59.5% |
| PAT margin | 4.9% | 4.4% | 13.9% |
| Other income / PBT – estimate | ~18% | 14% | 5% |
For margin and ratio rows, the YoY and QoQ columns show the prior-period value. The estimates assume Q1's ~25% tax rate and Q1-level depreciation and interest.
Quality of earnings
The YoY jump is flattered by a weak base. Q2 FY26 was hurt by weak OEM demand (cooling appliances), an extended monsoon and falling styrene prices [11].
The QoQ fall of ~60% in PAT is the real story. In Q1, a supply shock in West Asia widened the gap between styrene monomer (the raw material) and the company's products [6]. Management itself called the Q1 margin an aberration driven by unusually strong global spreads [6]. That boost has largely faded (my reading).
Revenue growth looks price-led. In Q1, revenue rose 22% even though volumes fell 24.5% [5]. Q2 volumes will only be known after the call.
The balance sheet stays debt-free, and an interim dividend of ₹2.50 was declared [1].
Margins (Chart 3)
EBITDA margin over five quarters: 7.0% → 5.5% → 15.9% → 19.4% → ~7% (estimate) [4]. The company's earnings swing with spreads more than with volumes (interpretation).
Guidance: what changed
- Margins: no numeric guidance. After Q1, management cautioned that the margin level was not sustainable [6].
- Capex: about ₹900 cr, funded internally, with capacities online by March 2029 [5]. This includes a ₹325 cr, 80,000 TPA polystyrene line approved in July [12].
- Call on 27 Oct: expect detail on volumes, exports and spreads [3].
Positives
- Debt-free; dividend maintained [1]
- PAT still about double the year-ago level [1]
- Capacity expansion funded internally [5]
Concerns
- Earnings depend heavily on global styrene spreads [6]
- Q1 volumes fell sharply [5]; Q2 volume data is not yet out
- Limited disclosure until the call (my view)
Things to track in Q3 FY27
- Actual Q2 EBITDA, volumes and spreads from the 27 Oct call
- Export recovery once West Asia shipping normalises
- Domestic demand from appliance OEMs
- Capex progress on the new lines
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Whalesbook, 23 Oct 2026 · [2] Sahi – Q2 revenue · [3] Multibagg – board/call schedule · [4] Fyers – consolidated quarterly · [5] FilingReader – Q1 FY27 · [6] Multibagg – Q1 FY27 call · [7] Valorem – Q1 FY27 call highlights · [8] Stockanalysis – annual · [9] Business Standard – FY24 · [10] Business Standard – FY25 · [11] Alphastreet – Q2 FY26 · [12] Sahi – Q1 FY27 capex
Charts:
(1) last 5 quarters revenue & PAT
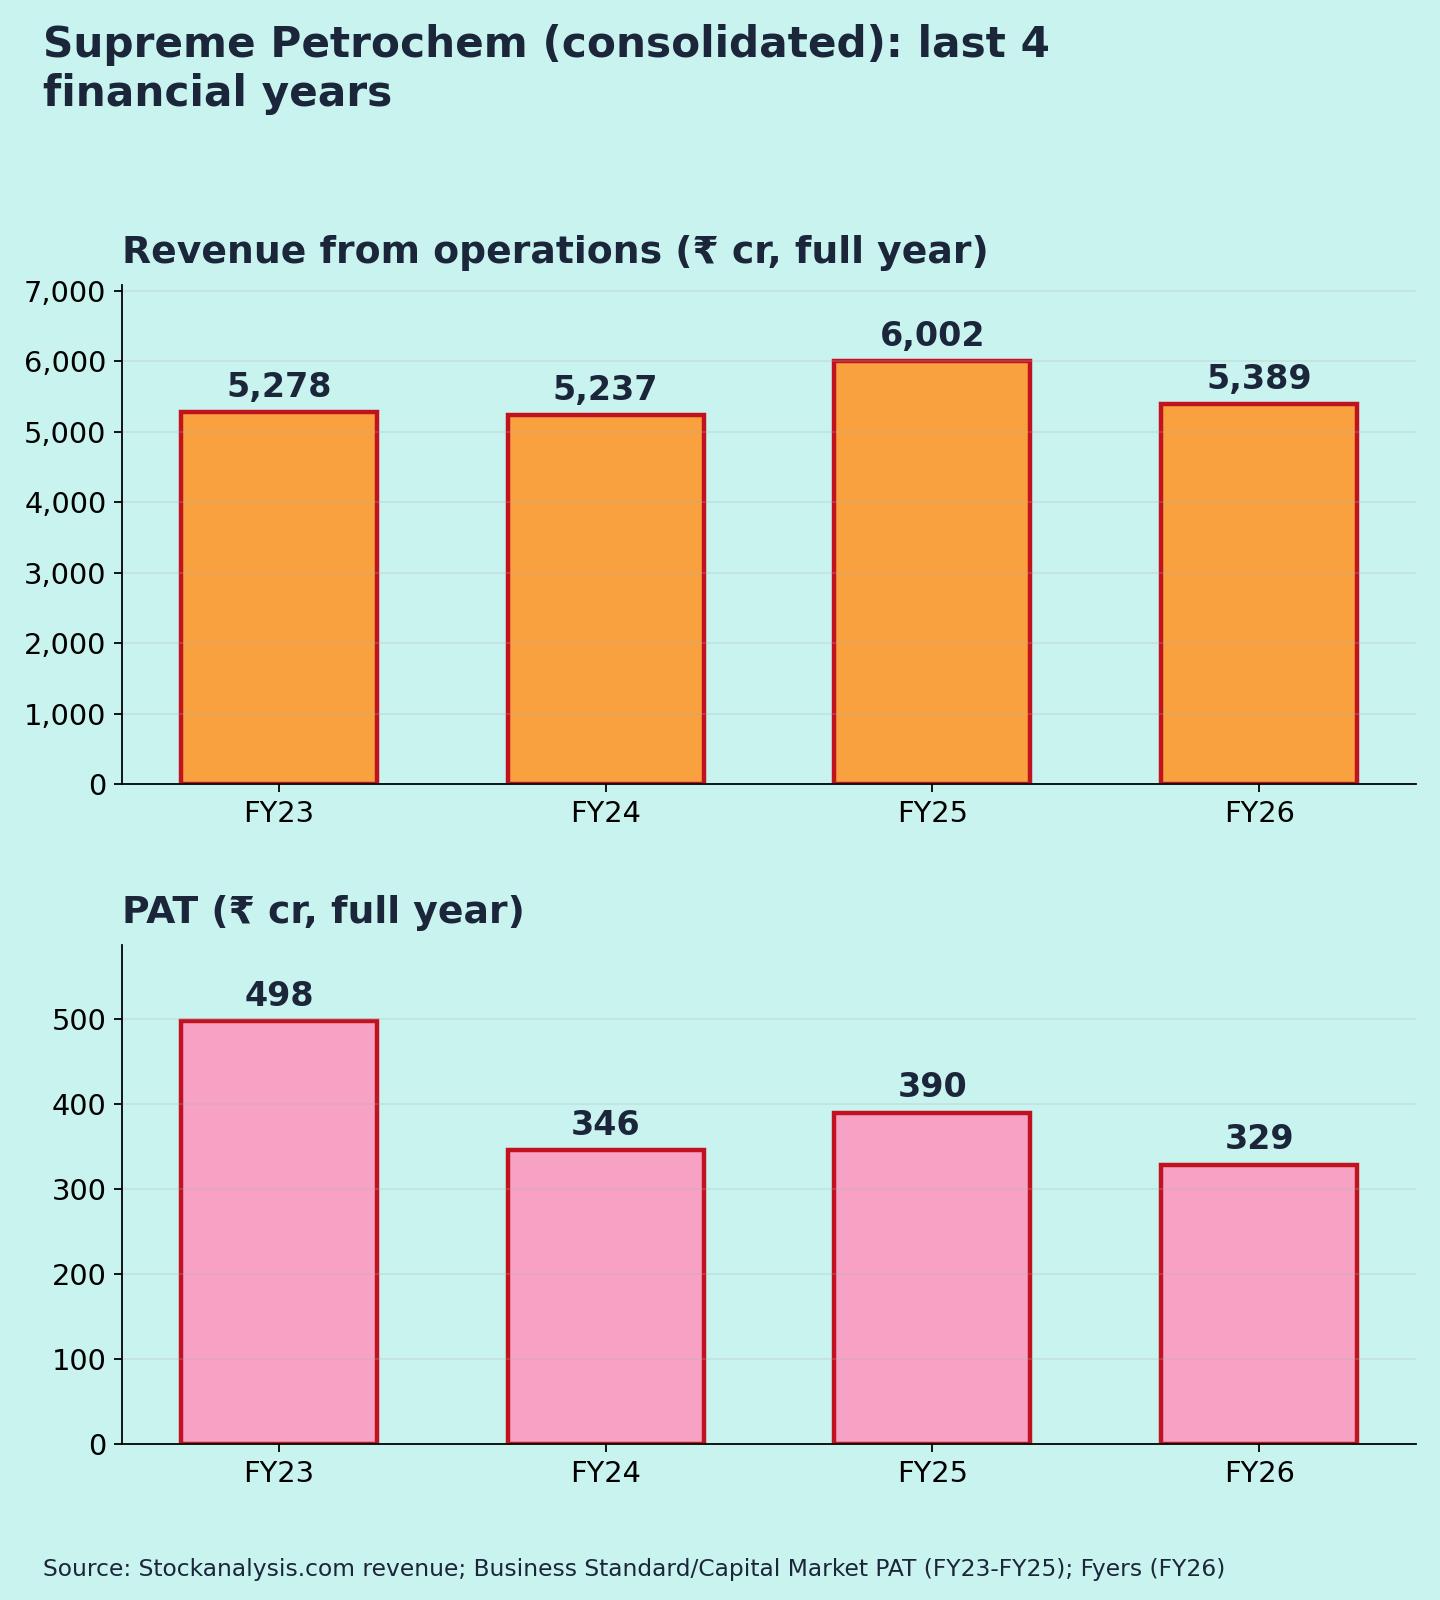
(2) FY23–FY26 revenue & PAT
(3) EBITDA margin (Q2 FY27 estimated) and PAT margin (own calc.).