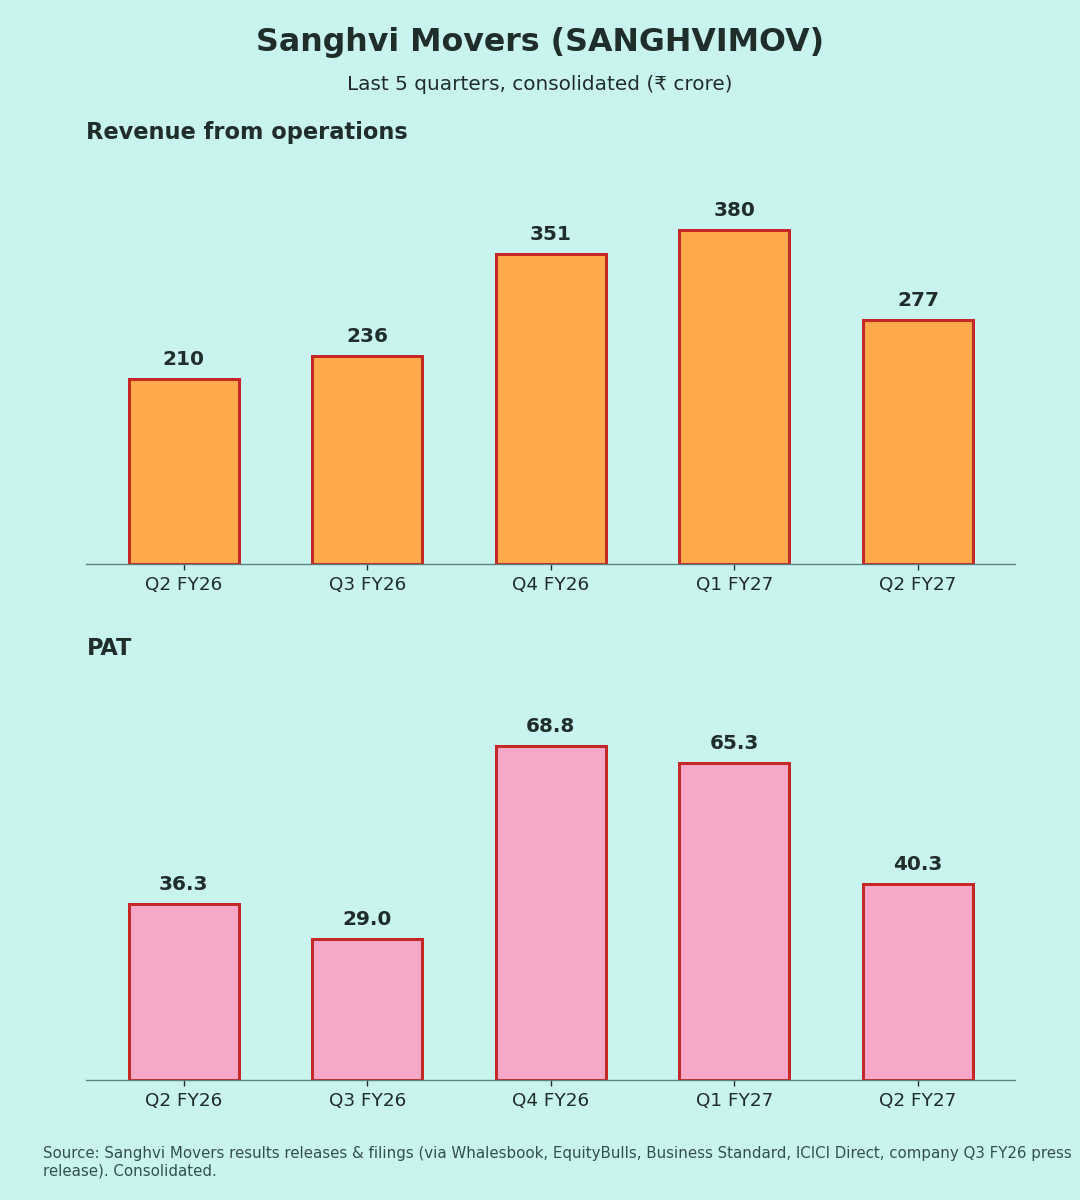
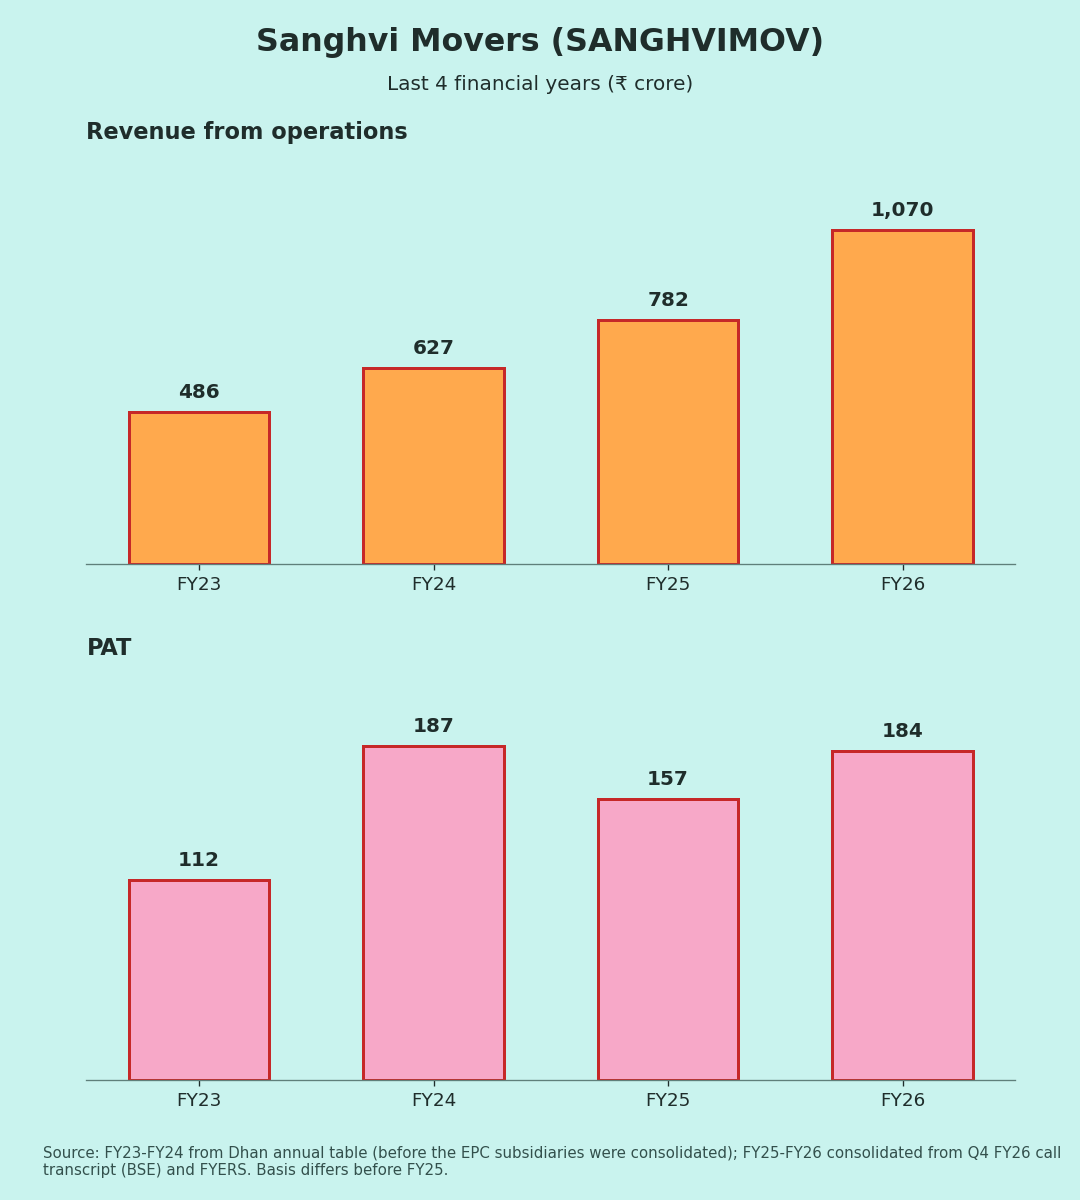
Consolidated figures, ₹ crore. At the time of writing, coverage of the filing gives revenue and PAT only. EBITDA, other income and the segment split should come with the investor presentation due on 3 Nov. I will not guess them, readers, please add once it is out. YoY/QoQ % and margins are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 277.0 | +32.0% | −27.0% |
| EBITDA / margin | not yet available | 38.6% a year ago | 33.0% last quarter |
| PAT | 40.3 | +11.2% | −38.2% |
| PAT margin | 14.6% | 17.3% | 17.2% |
| H1 FY27 revenue | 656.6 | +36.0% | – |
| H1 FY27 PAT | 105.6 | +22.0% | – |
Last Year EBITDA margin excludes other income (company's 42% includes it)
Seasonality first
Q2 is the monsoon quarter, when heavy-lift work slows. A year ago, Q2 revenue also fell 23% QoQ [5]. So the −27% QoQ fits the usual pattern; YoY is the fairer comparison.
Quality of earnings
Revenue grew 32% but PAT grew only 11%. Profit grew at about a third of the pace of sales.
Possible reasons (interpretation, not yet confirmed for Q2):
- Mix: More revenue from wind EPC, where management targets 10–12% EBITDA margins, against over 50% in Indian crane rental [8].
- Interest and depreciation: Quarterly interest rose from ₹7 cr (Q2 FY26) to ₹13 cr (Q1 FY27), and depreciation from ₹31 cr to ₹39 cr, as the fleet expanded [4].
Base effect: Q2 FY26 PAT had grown 24% YoY [5], so this is not a weak base.
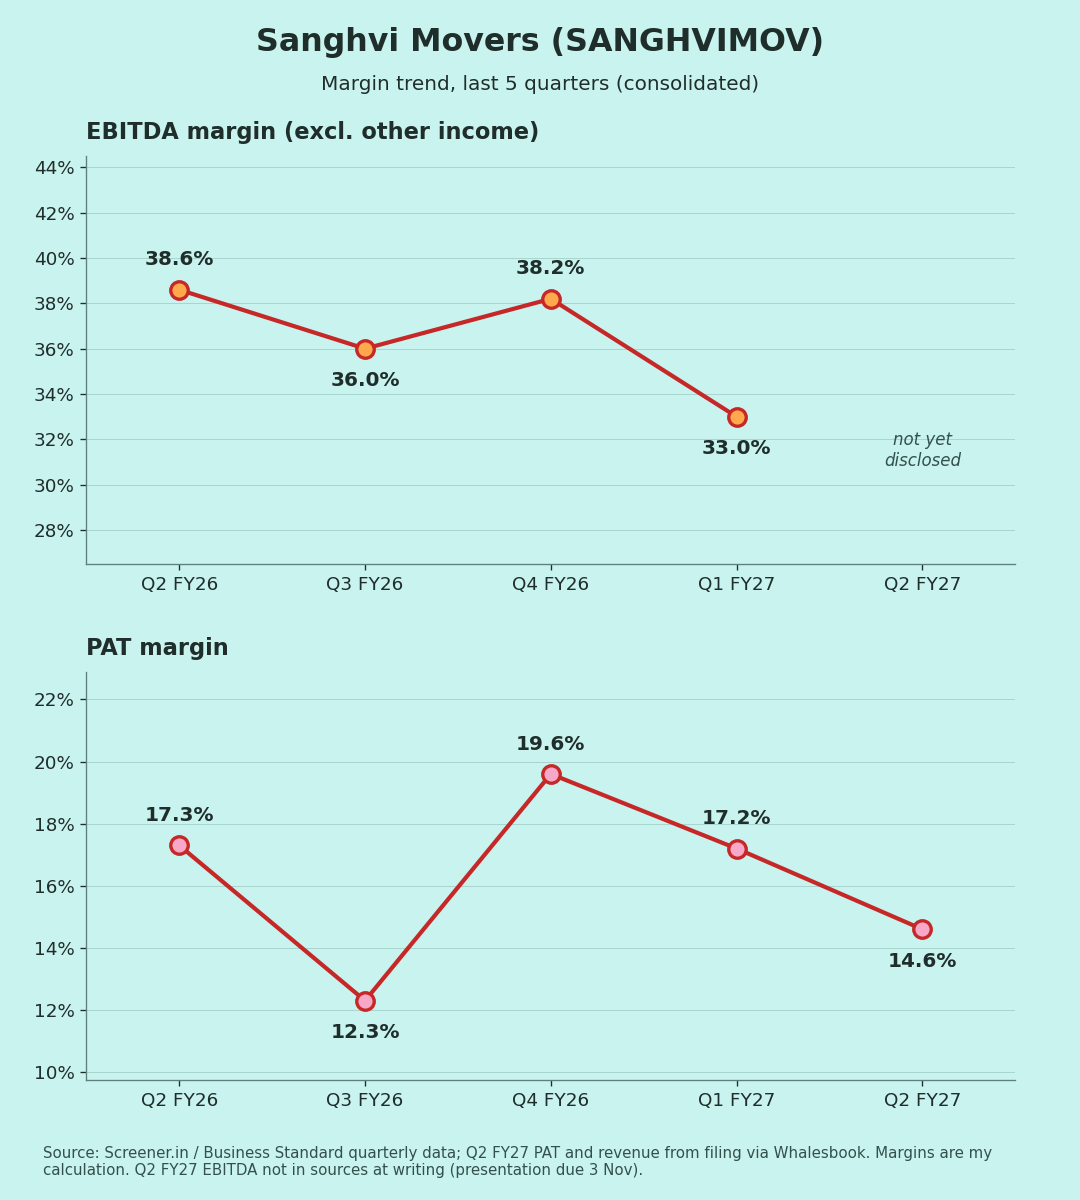
Margins (Chart 3)
EBITDA margin (ex-other income) over the last four reported quarters: 38.6% → 36.0% → 38.2% → 33.0% [3][4]. PAT margin over five quarters: 17.3% → 12.3% → 19.6% → 17.2% → 14.6% [1][6]. Q3 FY26 included an ₹8.4 cr exceptional loss [10].
Guidance: what changed
- First formal guidance: In November 2025, management said it does not guide on EBITDA margin [8]. With Q1 FY27 (July), it guided FY27 total income of ₹1,400–1,500 cr and EBITDA of ₹525–575 cr [9]. A change in disclosure.
- Progress: H1 revenue of ₹657 cr is 44–47% of that range. H2 needs roughly ₹745–845 cr (my calculation; guidance is total income, so approximate).
- Crane rental: On the Q4 FY26 call, management expected about 30% growth in the crane business [7].
- Order book: ₹1,860 cr as of Q3 FY26 [10]; no Q2 update in coverage yet.
Positives
- Revenue +32% YoY; H1 revenue +36%
- PAT up 11% YoY despite the monsoon quarter
- An independent director (Aditya Bhartia) added to the board
Concerns
- Profit growth well behind revenue growth [1]
- Rising interest and depreciation as the fleet grows [4]
- H2 has to deliver over half of the FY27 guidance (my calculation)
- No EBITDA or segment data yet (my view)
Things to track in Q3 FY27
- EBITDA run-rate vs the ₹525–575 cr FY27 guidance
- Revenue split: crane rental vs wind EPC vs project EPC
- Order book and crane utilisation
- Interest cost as borrowing funds the fleet
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Whalesbook – Q2 FY27 filing, 2 Nov 2026 · [2] Upstox – results live blog, 2 Nov · [3] Business Standard – Q1 FY27 data · [4] Screener.in – consolidated · [5] Company – Q2 FY26 press release · [6] Company – Q3 FY26 press release · [7] BSE – Q4 FY26 call transcript · [8] BSE – Q2 FY26 call transcript · [9] Zerodha/Reuters – FY27 guidance · [10] FinancePulse – Q3 FY26 call · [11] MarketScreener – events calendar · [12] FYERS – FY25/FY26 P&L · [13] Dhan – annual figures · [14] Multibagg – FY26 mix · [15] Sahi – Q1 FY26 PAT base
Charts: (1) last 5 quarters revenue & PAT [1][3][4][6]; (2) FY23–FY26 revenue & PAT: FY23–FY24 from [13], before the EPC subsidiaries were consolidated, FY25–FY26 consolidated [7][12], so the basis differs before FY25; (3) EBITDA margin (Q2 FY27 not yet disclosed) and PAT margin (own calc.).