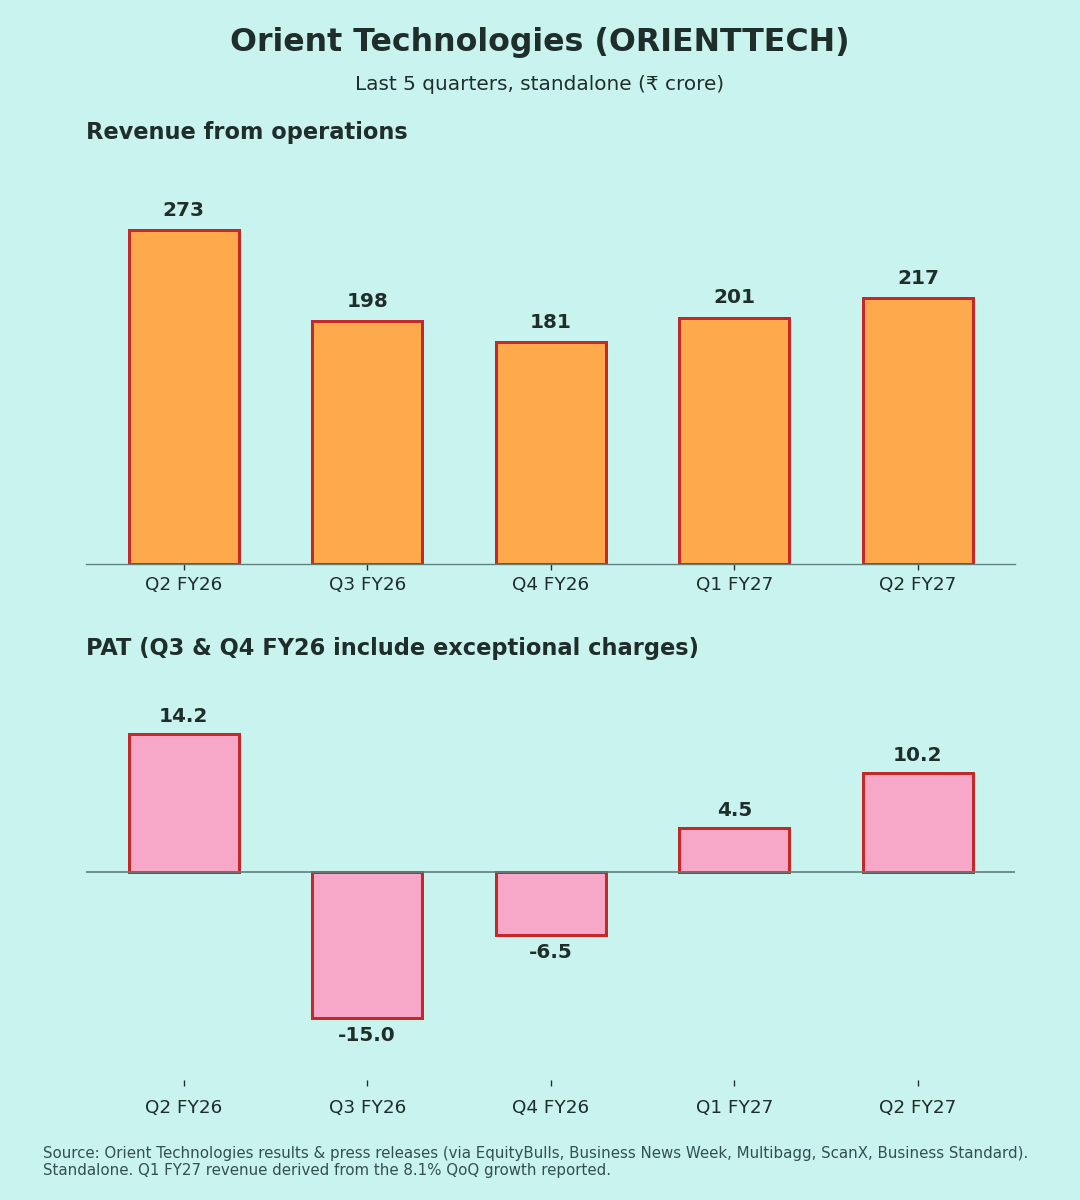
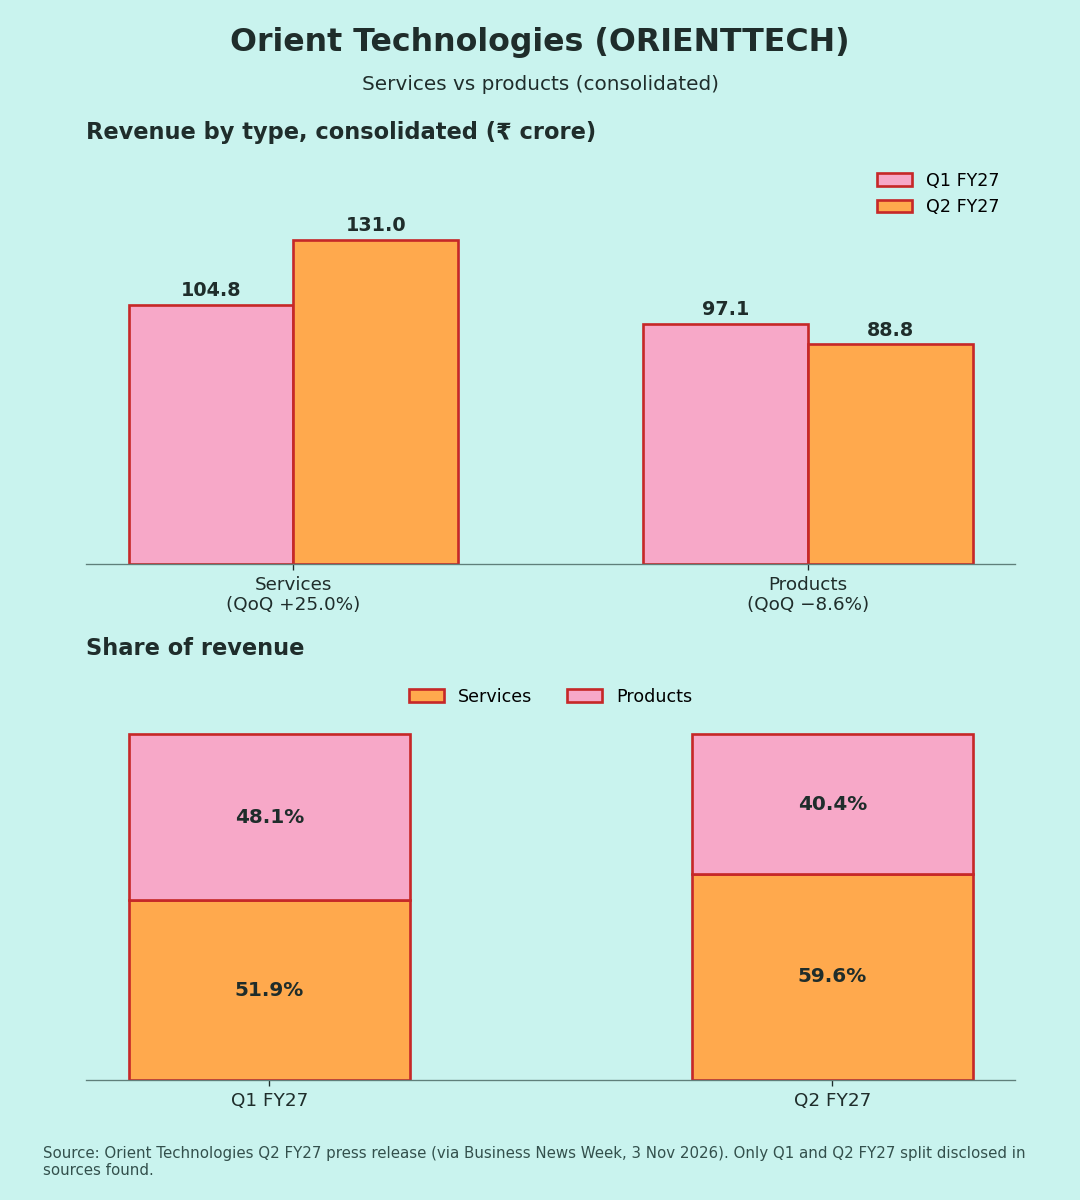
Standalone figures, ₹ crore. The services/products split is disclosed only on a consolidated basis, so that section uses consolidated numbers. Results were filed on 2 Nov 2026. YoY/QoQ %, margins and ratios are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 217.4 | −20.3% | +8.1% |
| EBITDA | 21.0 | −4.3% | +43.4% |
| EBITDA margin | 9.7% | 8.0% | 7.3% |
| PBT | 13.7 | −28.8% | +124.1% |
| PAT | 10.2 | −28.2% | +126.7% |
| PAT margin | 4.7% | 5.2% | 2.2% |
| Other income / PBT | 2.1% | n/a | 4.6% |
Margin and ratio rows show the year-ago and last-quarter values. Q1 FY27 revenue (₹201.1 cr) is derived from the reported 8.1% QoQ growth.
Read QoQ and YoY together
The company's release compares Q2 only with Q1, where everything is up sharply [2]. Against the same quarter last year, revenue is down 20% and PAT is down 28% [3][4]. Both views are true; new readers should look at both.
Quality of earnings
The QoQ recovery is operational. Other income is tiny (~₹0.3 cr), the tax rate is a normal ~25%, and there is no exceptional item this quarter [2] (my calculation).
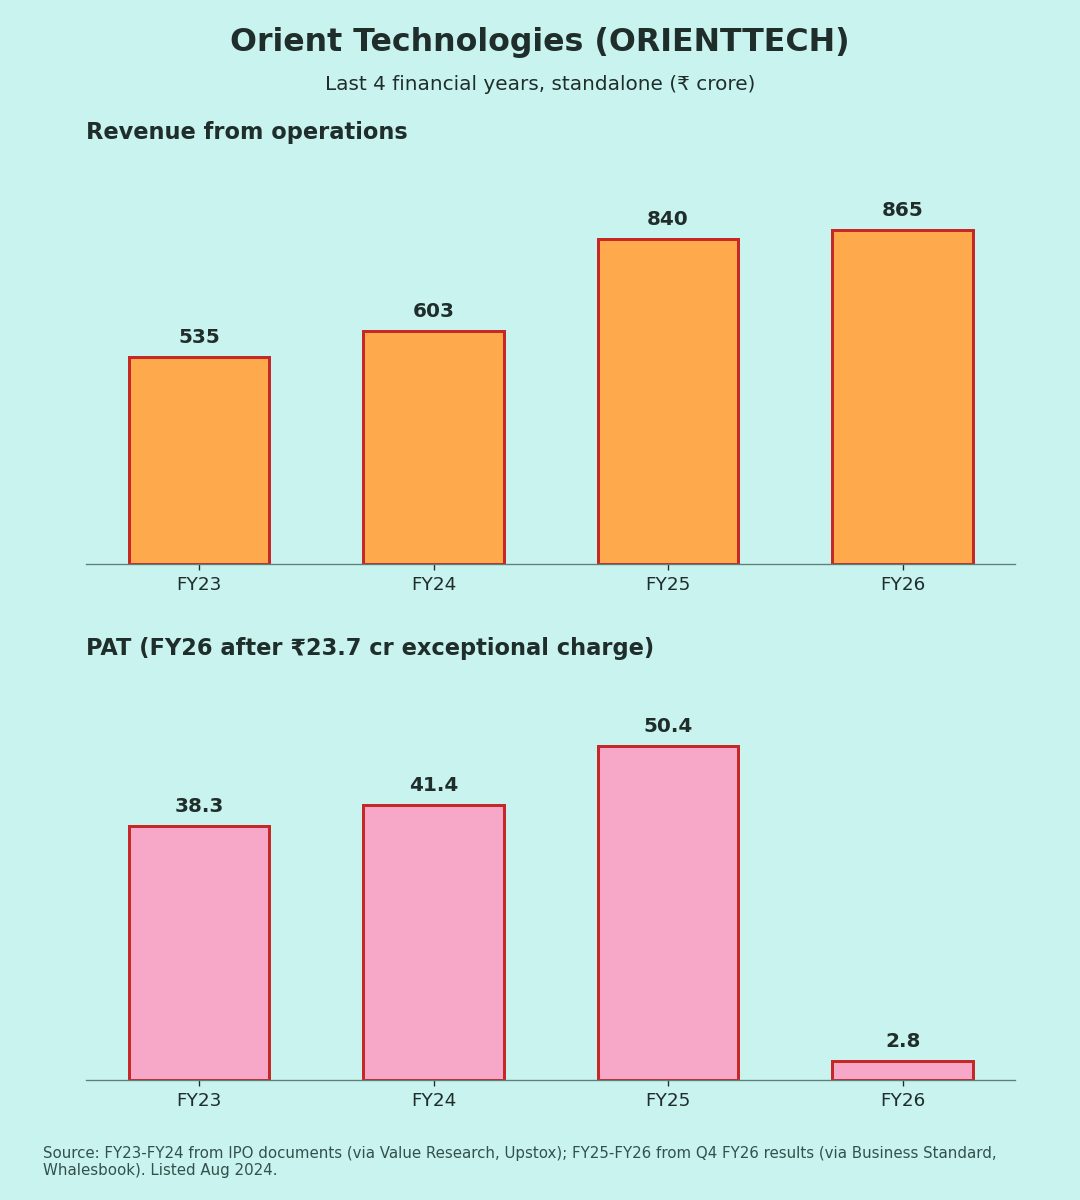
The YoY fall traces back to Q3 FY26, when the company lost a large hyperscaler cloud client [6]. That quarter and Q4 carried exceptional charges totalling ₹23.7 cr for FY26, mostly write-offs linked to that client [7]. So the Q2 FY26 base is the last "pre-loss" quarter, which makes YoY look harsh (interpretation).
One point to note: EBITDA fell only 4% YoY but PAT fell 28%. Depreciation plus interest took about ₹7.4 cr this quarter vs about ₹2.8 cr a year ago (my calculation from [2][4]). Quarterly interest rose to ₹1.8 cr in Q1 FY27 from ₹0.8 cr a year earlier [8].
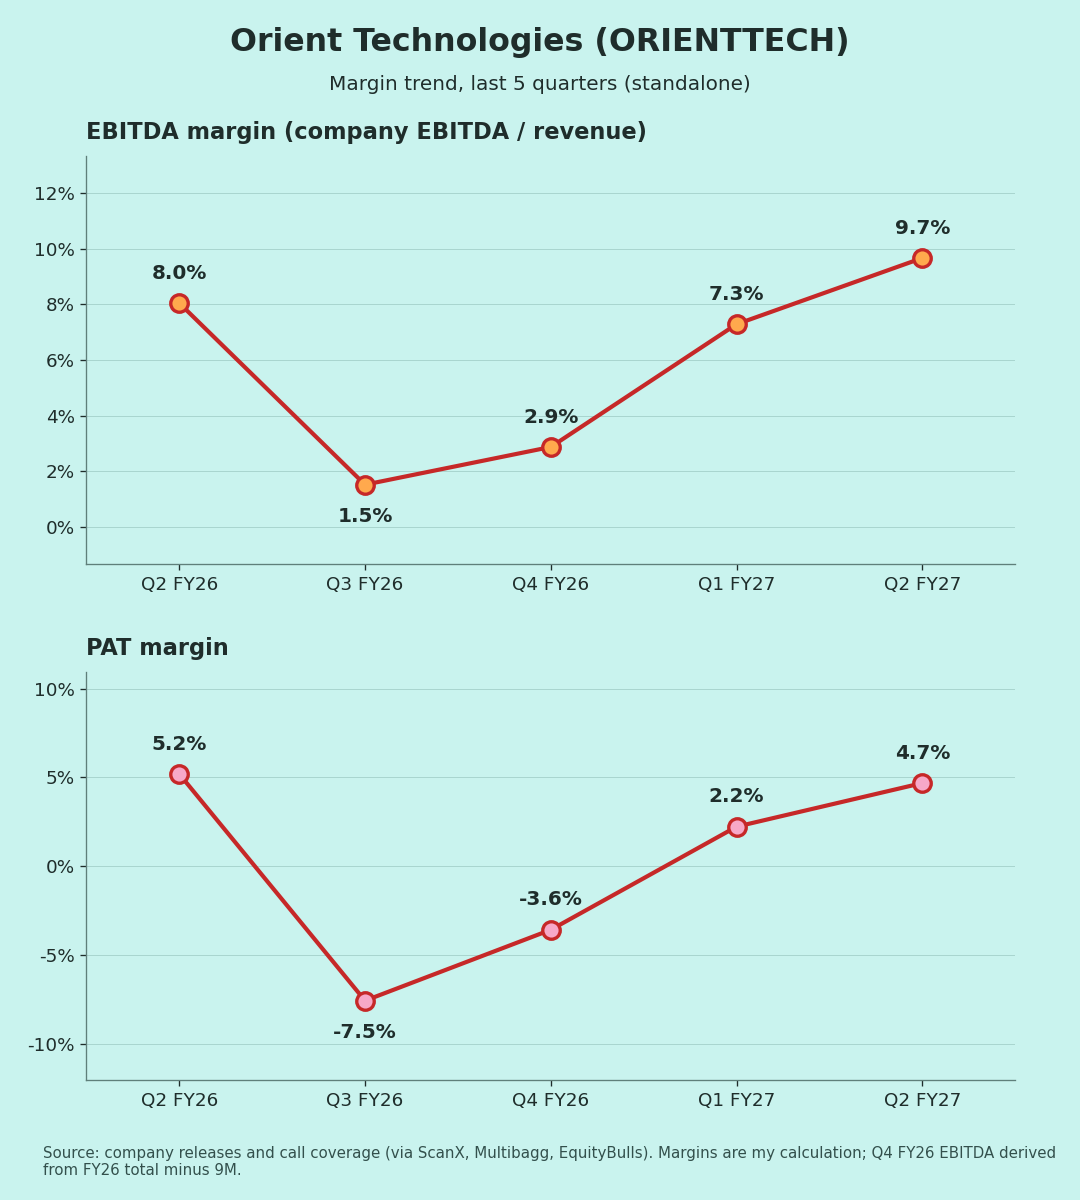
Margins (Chart 3)
EBITDA margin over five quarters: 8.0% → 1.5% → 2.9% → 7.3% → 9.7%. Q2 FY27 is the highest of the five. Management credits a richer mix: services rose 25% QoQ to ₹131.0 cr (60% of consolidated revenue), while products fell 8.6% to ₹88.8 cr [2].
Guidance: what changed
- FY26 outlook missed: In Nov 2025, management said it was confident of "strong double-digit" FY26 revenue growth [4]. FY26 ended at +3% [7].
- Margin: On the Q1 call, the CMD said the then ~7.6% EBITDA margin was sustainable [10]. Q2 came in above that.
- Order book: ₹375.43 cr in August, billable in FY27, mostly in Q3–Q4 [10]. Now ₹331.61 cr, billable by March 2027 [2]. My reading: billing happened, but the book did not grow.
- Annuity revenue: 23% of revenue in Q1; 51% in about three years [10]. No Q2 figure in the release.
Positives
- Second straight quarter of QoQ recovery [2]
- Services share up to 60% from 52% [2]
- Interim dividend of ₹2/share, record date 13 Nov [5]
Concerns
- Revenue still 20% below last year; H1 revenue −14%, H1 PAT −39% (my calculation)
- Order book smaller than in August [2][10]
- Rising depreciation and interest (my view)
- Client concentration risk, as the Q3 FY26 loss showed [6]
Things to track in Q3 FY27
- Order book conversion in the back-loaded H2
- Whether the EBITDA margin holds near 9–10%
- Products revenue: does the 8.6% QoQ fall reverse?
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] EquityBulls – Q2 FY27 press release, 2 Nov 2026 · [2] Business News Week – full release with segment split, 3 Nov · [3] Sahi – YoY revenue · [4] ScanX – Q2 FY26 results & outlook · [5] Multibagg – Q2 FY27, dividend, call · [6] CXO Digitalpulse – Q3 FY26 · [7] Whalesbook – FY26 results · [8] Screener.in – standalone · [9] ScanX – Q3 FY26 call · [10] Yahoo Finance – Q1 FY27 call highlights · [11] Business Standard – Q4 FY26 standalone · [12] Whalesbook – FY26 EBITDA · [13] Value Research – FY23–FY24
Charts:
(1) last 5 quarters revenue & PAT,
(2) FY23–FY26 revenue & PAT
(3) EBITDA and PAT margin