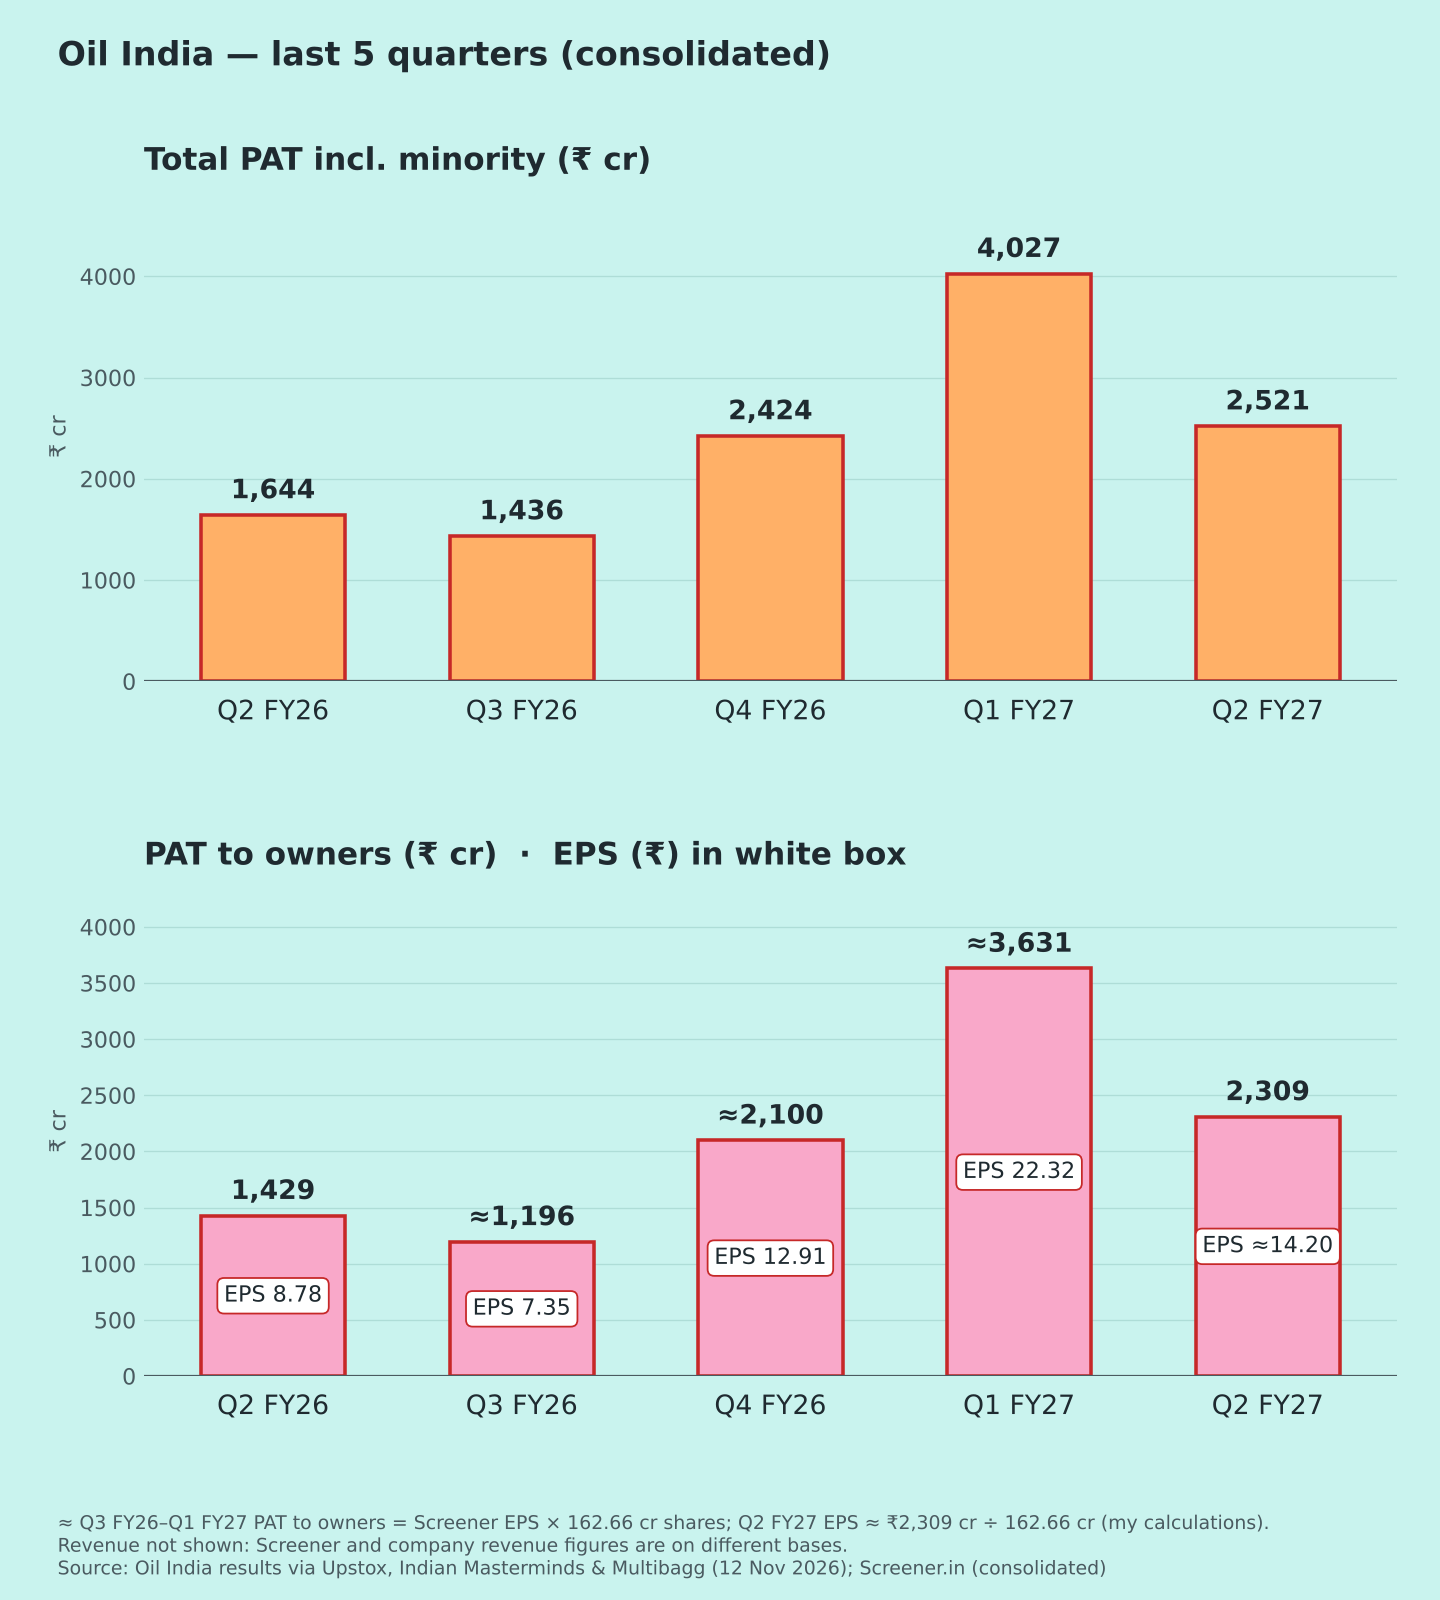
Consolidated figures, ₹ crore, unless marked standalone. Results announced 12 Nov 2026. Consolidated includes Numaligarh Refinery (NRL), which has minority shareholders, so there are two profit figures: total PAT ₹2,521 cr and PAT attributable to Oil India's owners ₹2,309 cr [1][2]. EPS is derived on the owners' figure. EBITDA excludes other income [1]. Other income, PBT and tax weren't in coverage and are left out.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 11,915 | +29.9% | ≈−7.5% |
| EBITDA | 3,971 | +72% | — |
| EBITDA margin | 33.3% | 25.1% | — |
| PAT, total | 2,521 | +53.3% | ≈−37% |
| PAT to owners | 2,309 | +61.6% | ≈−36% |
| PAT margin (total) | 21.2% | 17.9% | ≈31.3% |
| EPS (₹, ≈ derived) | ≈14.20 | 8.78 | 22.32 |
| Standalone PAT | 2,259 | +116% | ≈−21% |
Margin and EPS rows show year-ago and last-quarter values. ≈ derived: Q1 FY27 PAT = H1 minus Q2; Q1 revenue ₹12,886 cr from a preview [5];
Quality of earnings
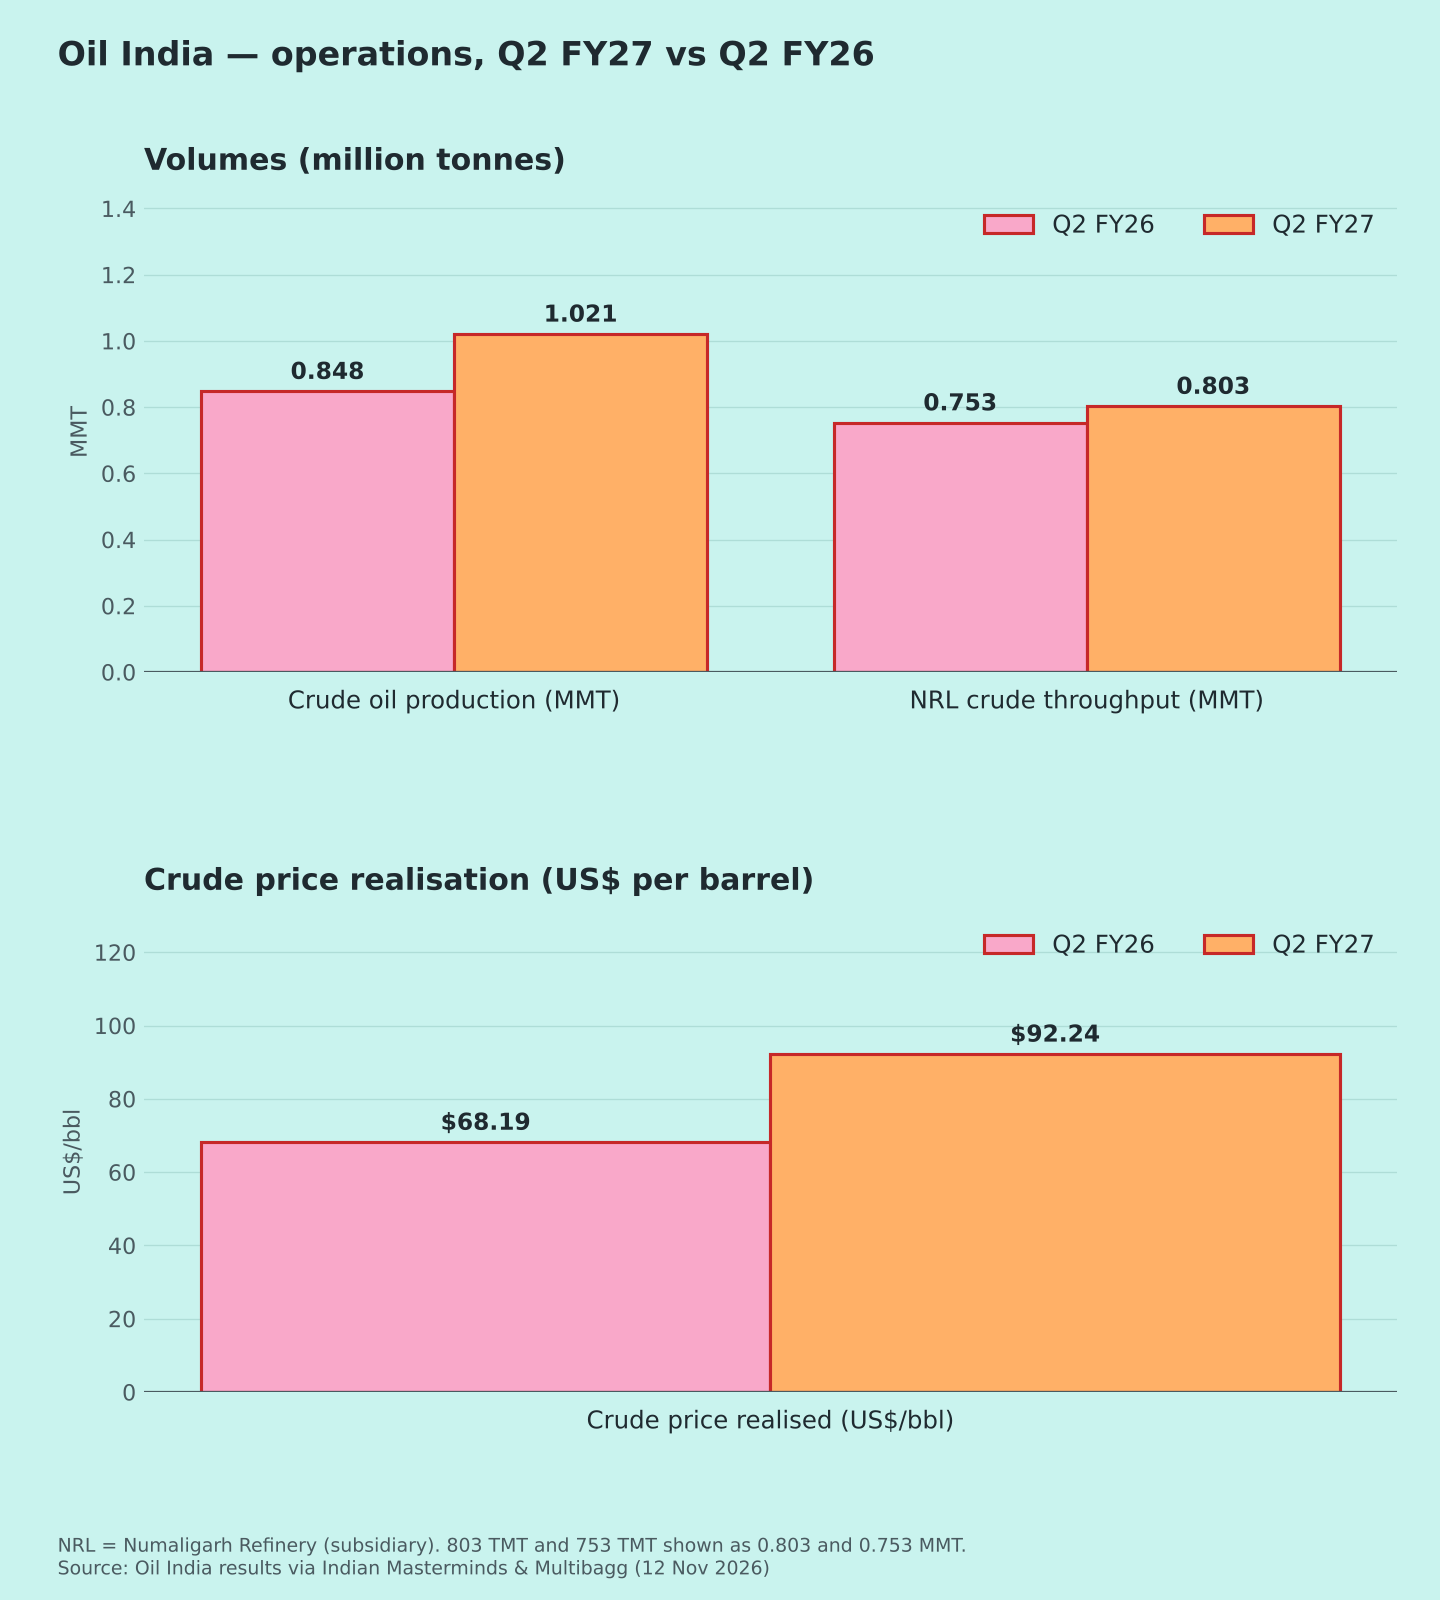
- Price and volume both helped. Crude realisation rose 35% to US$92.24/bbl from US$68.19, and crude output rose 20% to 1.021 million tonnes [2][3]. Most of the profit jump is from higher oil prices, which the company doesn't control (my view).
- Why consolidated grew slower than standalone: subsidiaries/JVs added about ₹262 cr this quarter vs ₹600 cr a year ago (my calculation). Coverage doesn't explain the drop; NRL's half-year refining margin was much higher (US$28.24/bbl vs US$7.73) [2].
- QoQ fall: Q1 was an unusually strong quarter (PAT ₹4,027 cr) [4]. Coverage doesn't break down the QoQ drop.
- Possible item to check: a separate disclosure mentions a royalty tax provision of ₹5,283.85 cr [6]. I haven't verified it; please check before posting.
Operations (Chart 5)
- Highest daily crude output in a decade on 29 Sep 2026 [2].
- 42 wells drilled in H1, the highest for a half-year [2].
- NRL processed 803 thousand tonnes of crude (753 a year ago) [2].
Dividend: interim dividend ₹7 per share [1][2]. Record and payment dates differ across reports; please confirm in the filing.
Positives
- Crude output up 20% [2]
- Standalone profit more than doubled [2]
Concerns
- Earnings depend on crude prices (my view)
- Unexplained fall in subsidiary contribution (my calculation)
Things to track in Q3 FY27
- Crude realisation vs US$90
- Production growth
- NRL refining margin
- The royalty provision disclosure
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Upstox – Q2 results · [2] Indian Masterminds – Q2 results · [3] Multibagg – Q2 profit · [4] Screener.in – consolidated · [5] Trade Brains – preview · [6] Multibagg – royalty provision (not verified)
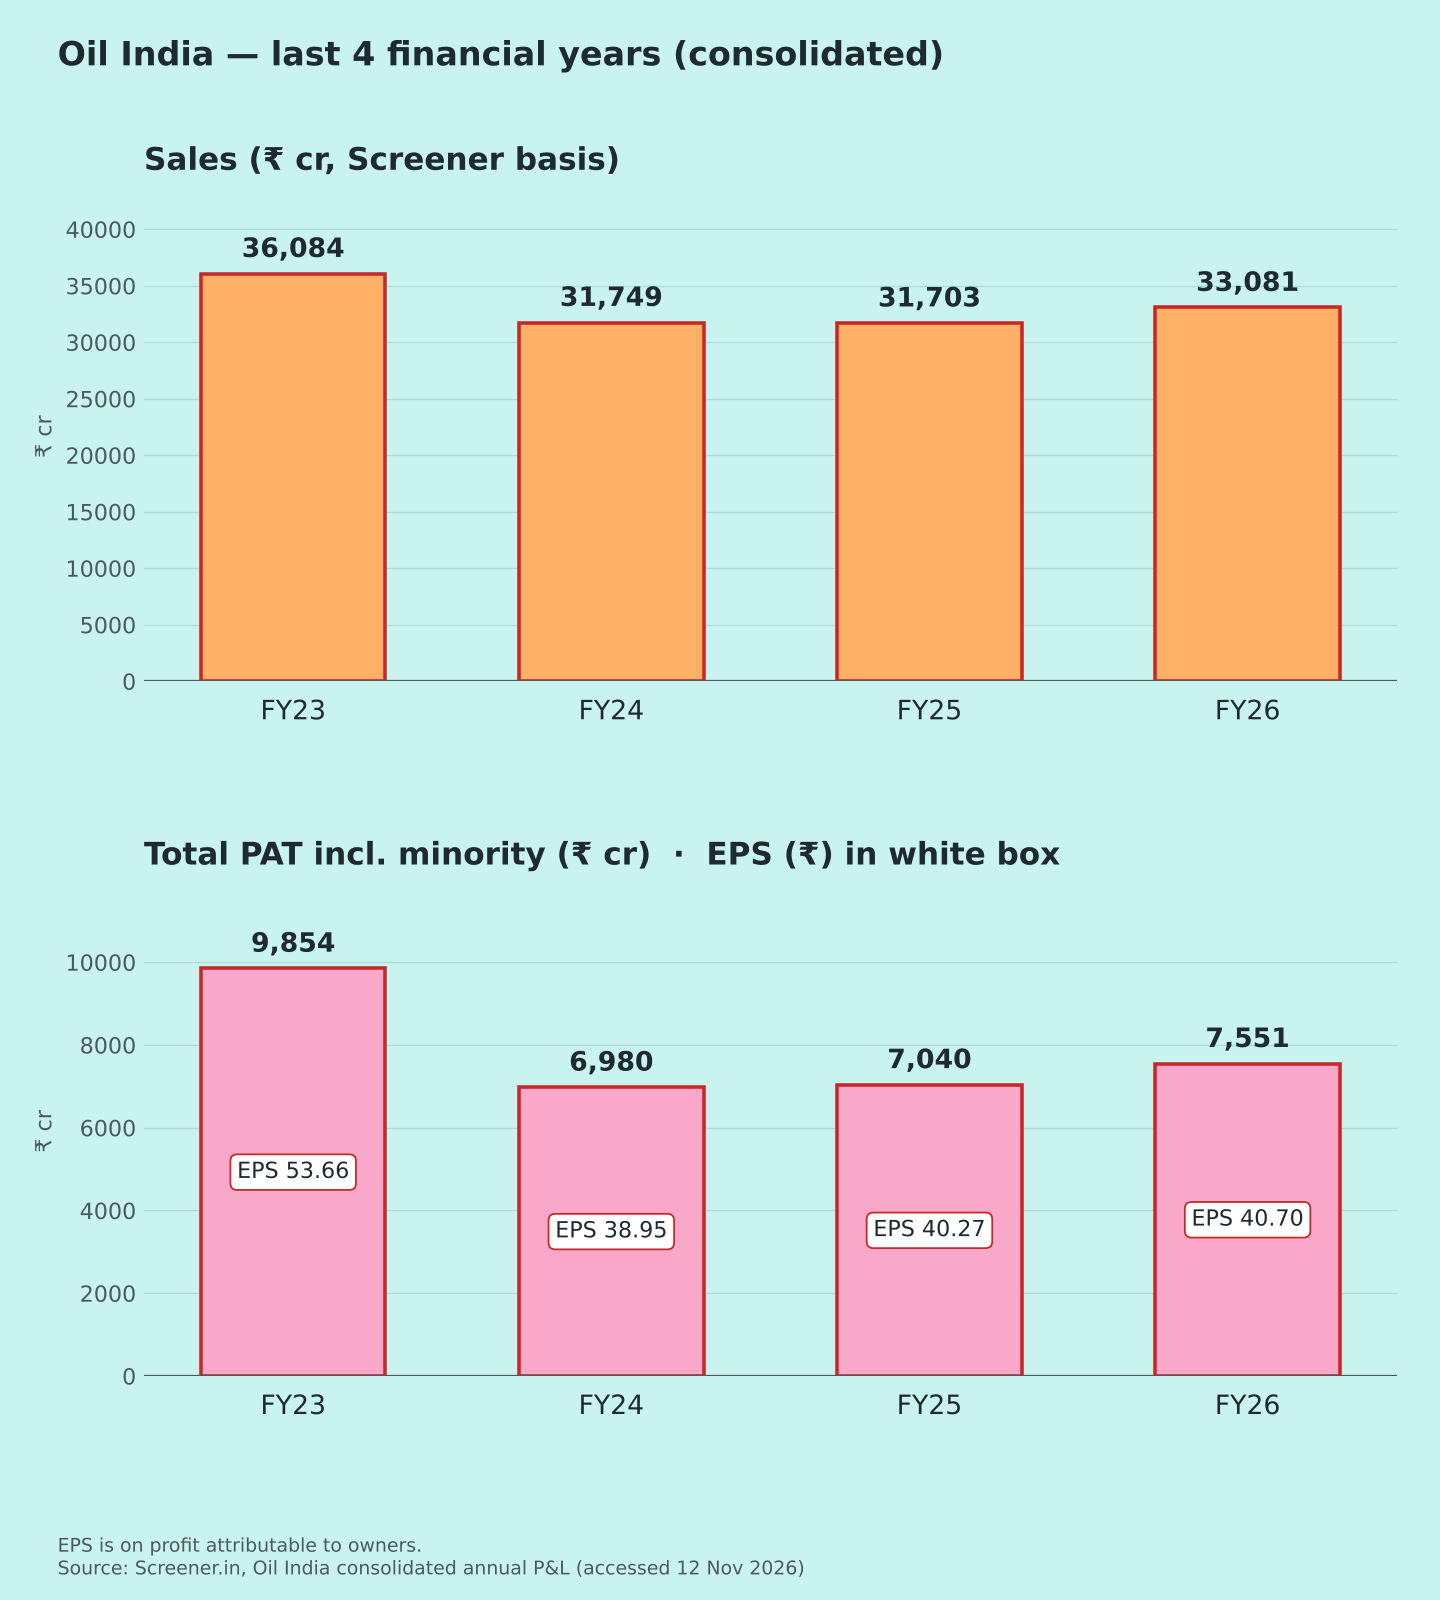
Charts: (1) 5 quarters total PAT and PAT to owners with EPS [1][4]; (2) FY23–FY26 (3) operations