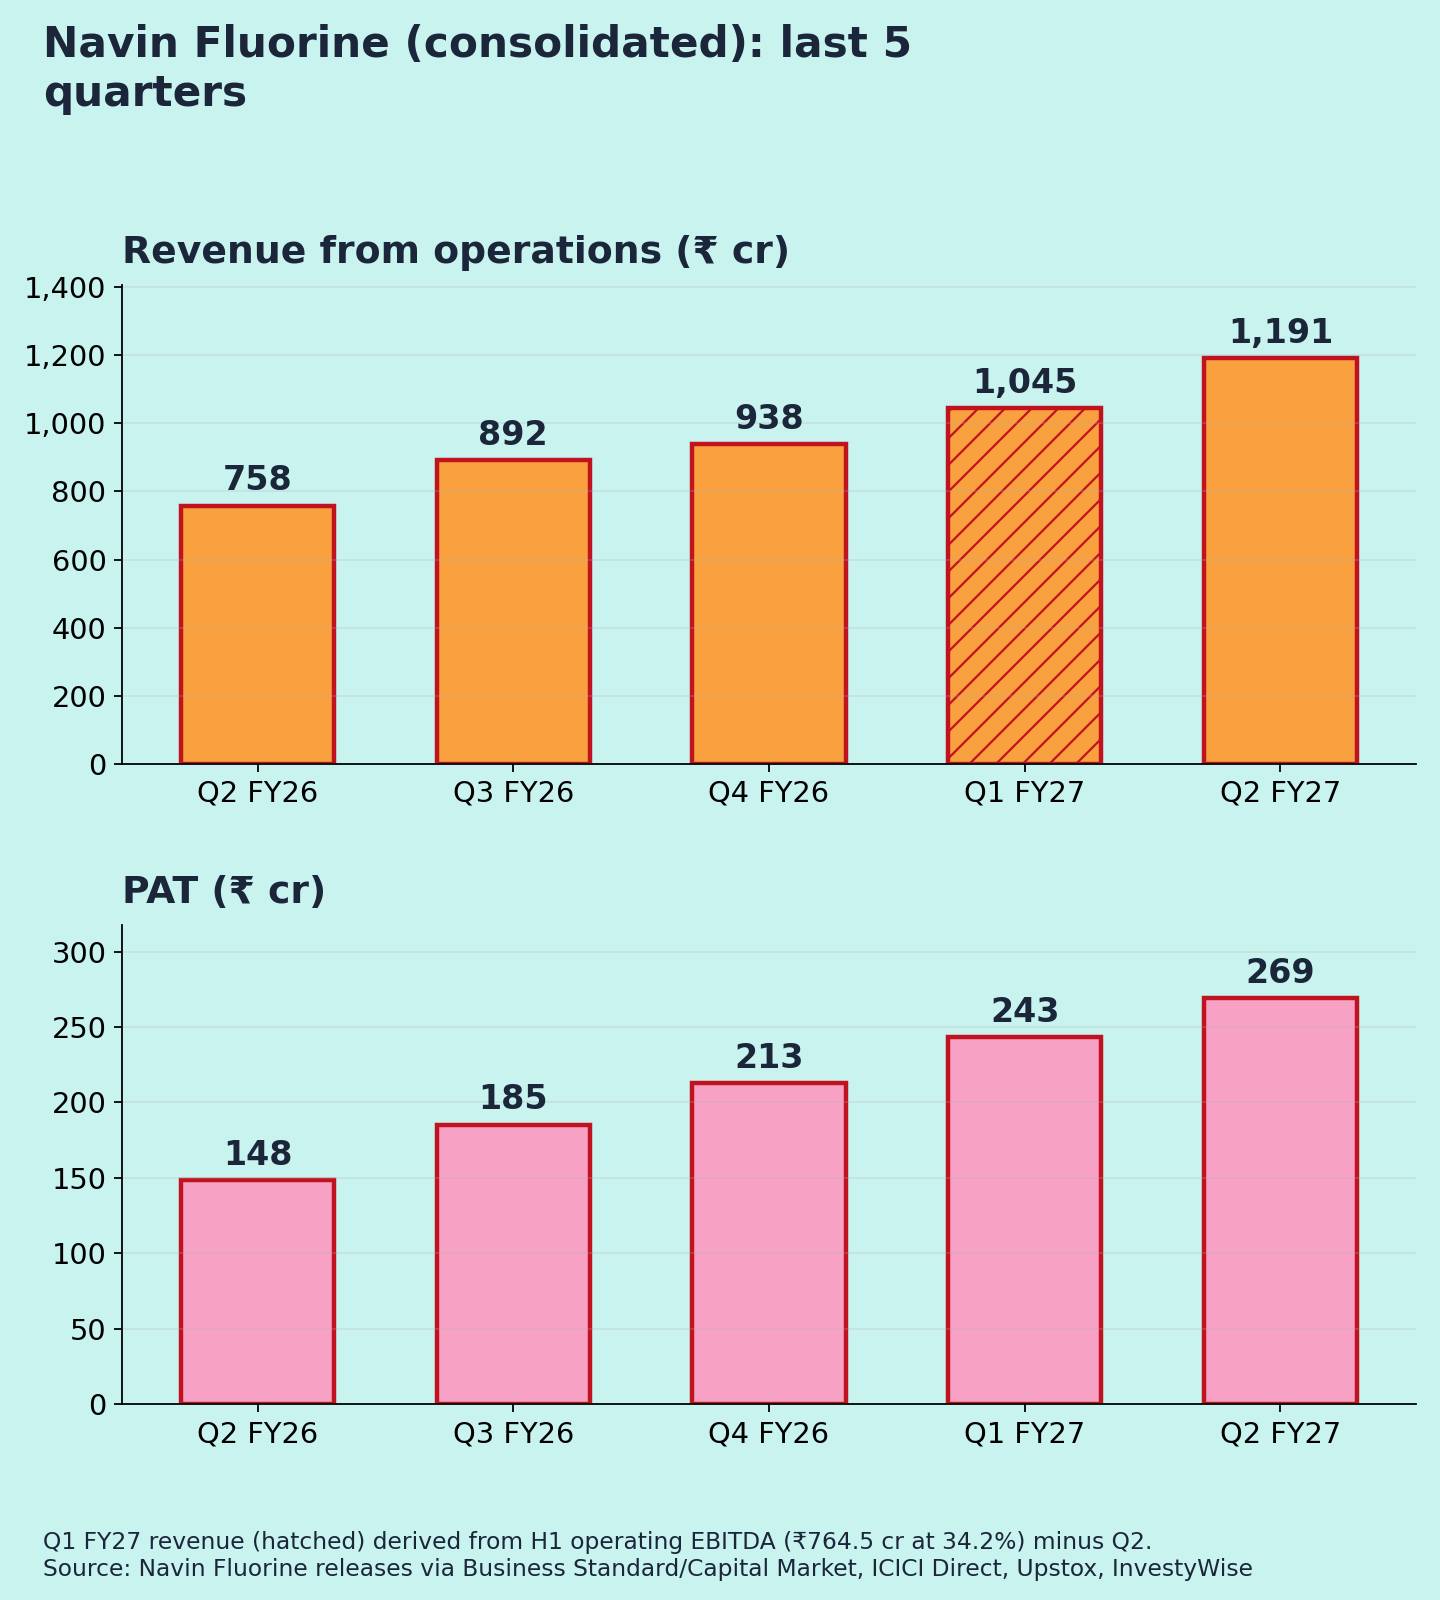
All figures consolidated, ₹ crore unless stated. Results approved on 30 Oct 2026. YoY/QoQ % and margins are my calculations; Q1 FY27 revenue and EBITDA are derived from H1 totals.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 1,190.7 | +57.0% | +14.0% |
| Operating EBITDA | 407.5 | +65.6% | +14.1% |
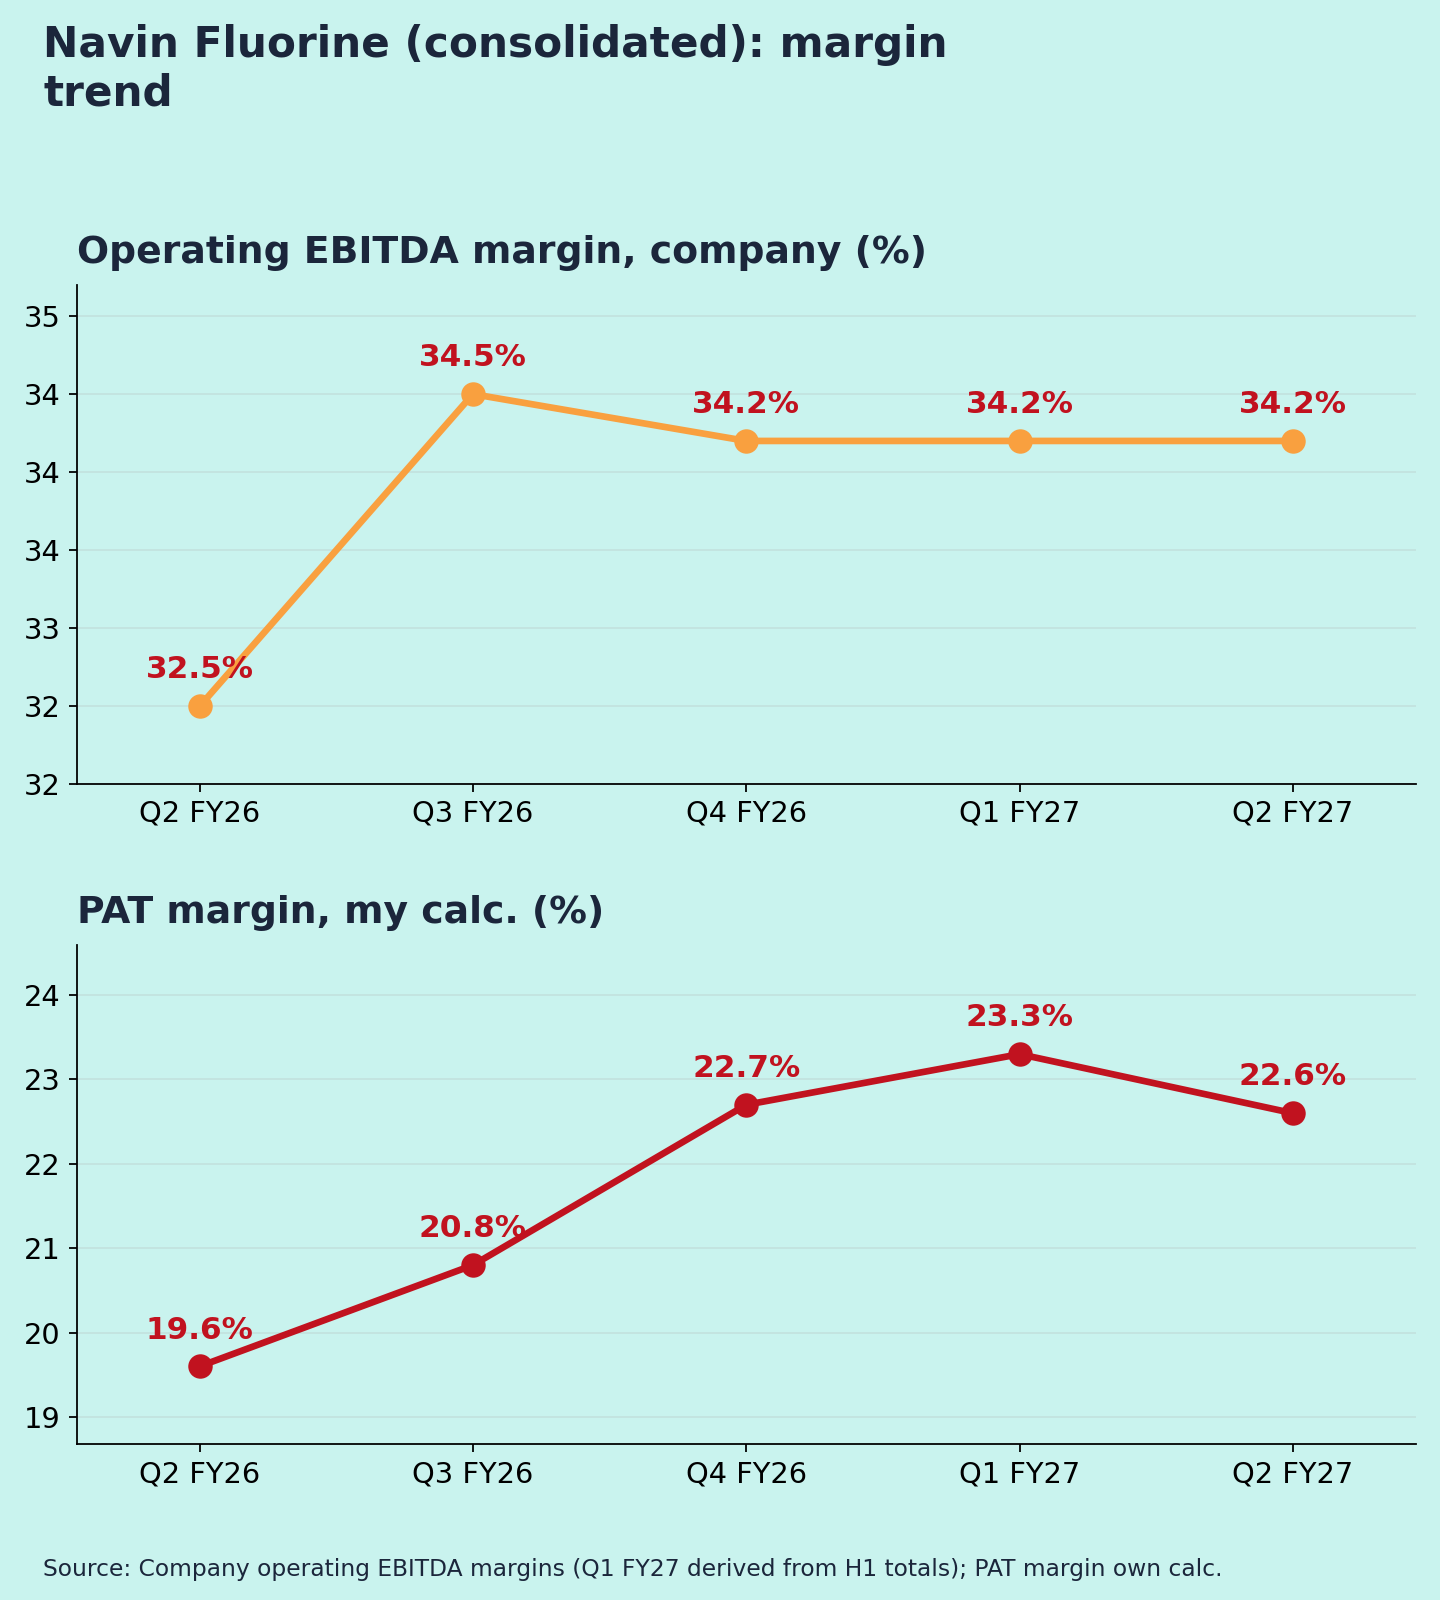
| EBITDA margin | 34.2% | 32.5% | 34.2% |
| PAT | 269.2 | +81.4% | +10.7% |
| PAT margin | 22.6% | 19.6% | 23.3% |
| Other income | ~15.6 | – | – |
For margin rows, the YoY and QoQ columns show the prior-period value.
Quality of earnings
Growth is operational and broad-based [4]:
- High Performance Products (refrigerant gases): ₹604 cr, +49%.
- Specialty Chemicals: ₹348 cr, +58%.
- CDMO (contract manufacturing for pharma): ₹239 cr, +78%.
Other income is small, about ₹16 cr against PAT of ₹269 cr (my calculation from [3]).
Base effect: Q2 FY26 was not a weak base. It was itself a breakout quarter, with EBITDA up 129% YoY and a 32.5% margin [5]. So growing 57% on top of that is a genuine step-up (my view).
QoQ, revenue and EBITDA both rose 14%, but PAT rose only 11%. The gap points to higher depreciation and interest as new capacity comes in (interpretation; the line items weren't in the coverage I found).
Margins (Chart 3)
Operating EBITDA margin over five quarters: 32.5% → 34.5% → 34.2% → 34.2% → 34.2%. It has held at about 34% for four quarters. Management attributes the earlier expansion to new molecules and operating leverage [8].
Guidance: what changed
- Margin: at Q4 FY26, management guided FY27 EBITDA margin at about 30%, plus or minus 1–2%. H1 is at 34.2% [4], well above. The guide looks conservative so far (my view).
- Capacity: a ₹240 cr project adding 15 ktpa of R-32 refrigerant [8], and the Dahej multipurpose plant debottlenecking, are both targeted for Q3 FY27 [9].
- Working capital: guided at 75–80 days.
- Dividend: interim ₹8 per share (400%).
Market reaction
Navin Fluorine rose 5.1% on 30 Oct.
Positives
- All three businesses growing 49–78%
- Margins steady at ~34%, above guidance
- CDMO scaling up fast (+78%)
Concerns
- The stock already prices in a lot after a strong FY26 (my view)
- PAT growing slower than EBITDA QoQ
- Refrigerant gases (HPP, half of revenue) are exposed to global regulation and pricing cycles [11]
Things to track in Q3 FY27
- Commissioning of the R-32 and Dahej projects
- EBITDA margin vs the 30% guide
- CDMO order flow
- Working capital days
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Upstox, 30 Oct 2026 · [2] Sahi – EBITDA · [3] InvestyWise – results filing · [4] InvestyWise – Q2 FY27 presentation · [5] Business Standard/Capital Market – Q2 FY26 · [6] ICICI Direct – Q3 FY26 · [7] Business Standard – Q4 FY26 · [8] ICICI Securities – Q4 FY26 note · [9] AlphaSpread – Q4 FY26 call · [10] Evening market wrap, 30 Oct 2026 (this series) · [11] ScanX – Kigali/HFC context · [12] Quartr – FY24 · [13] ScanX – FY26
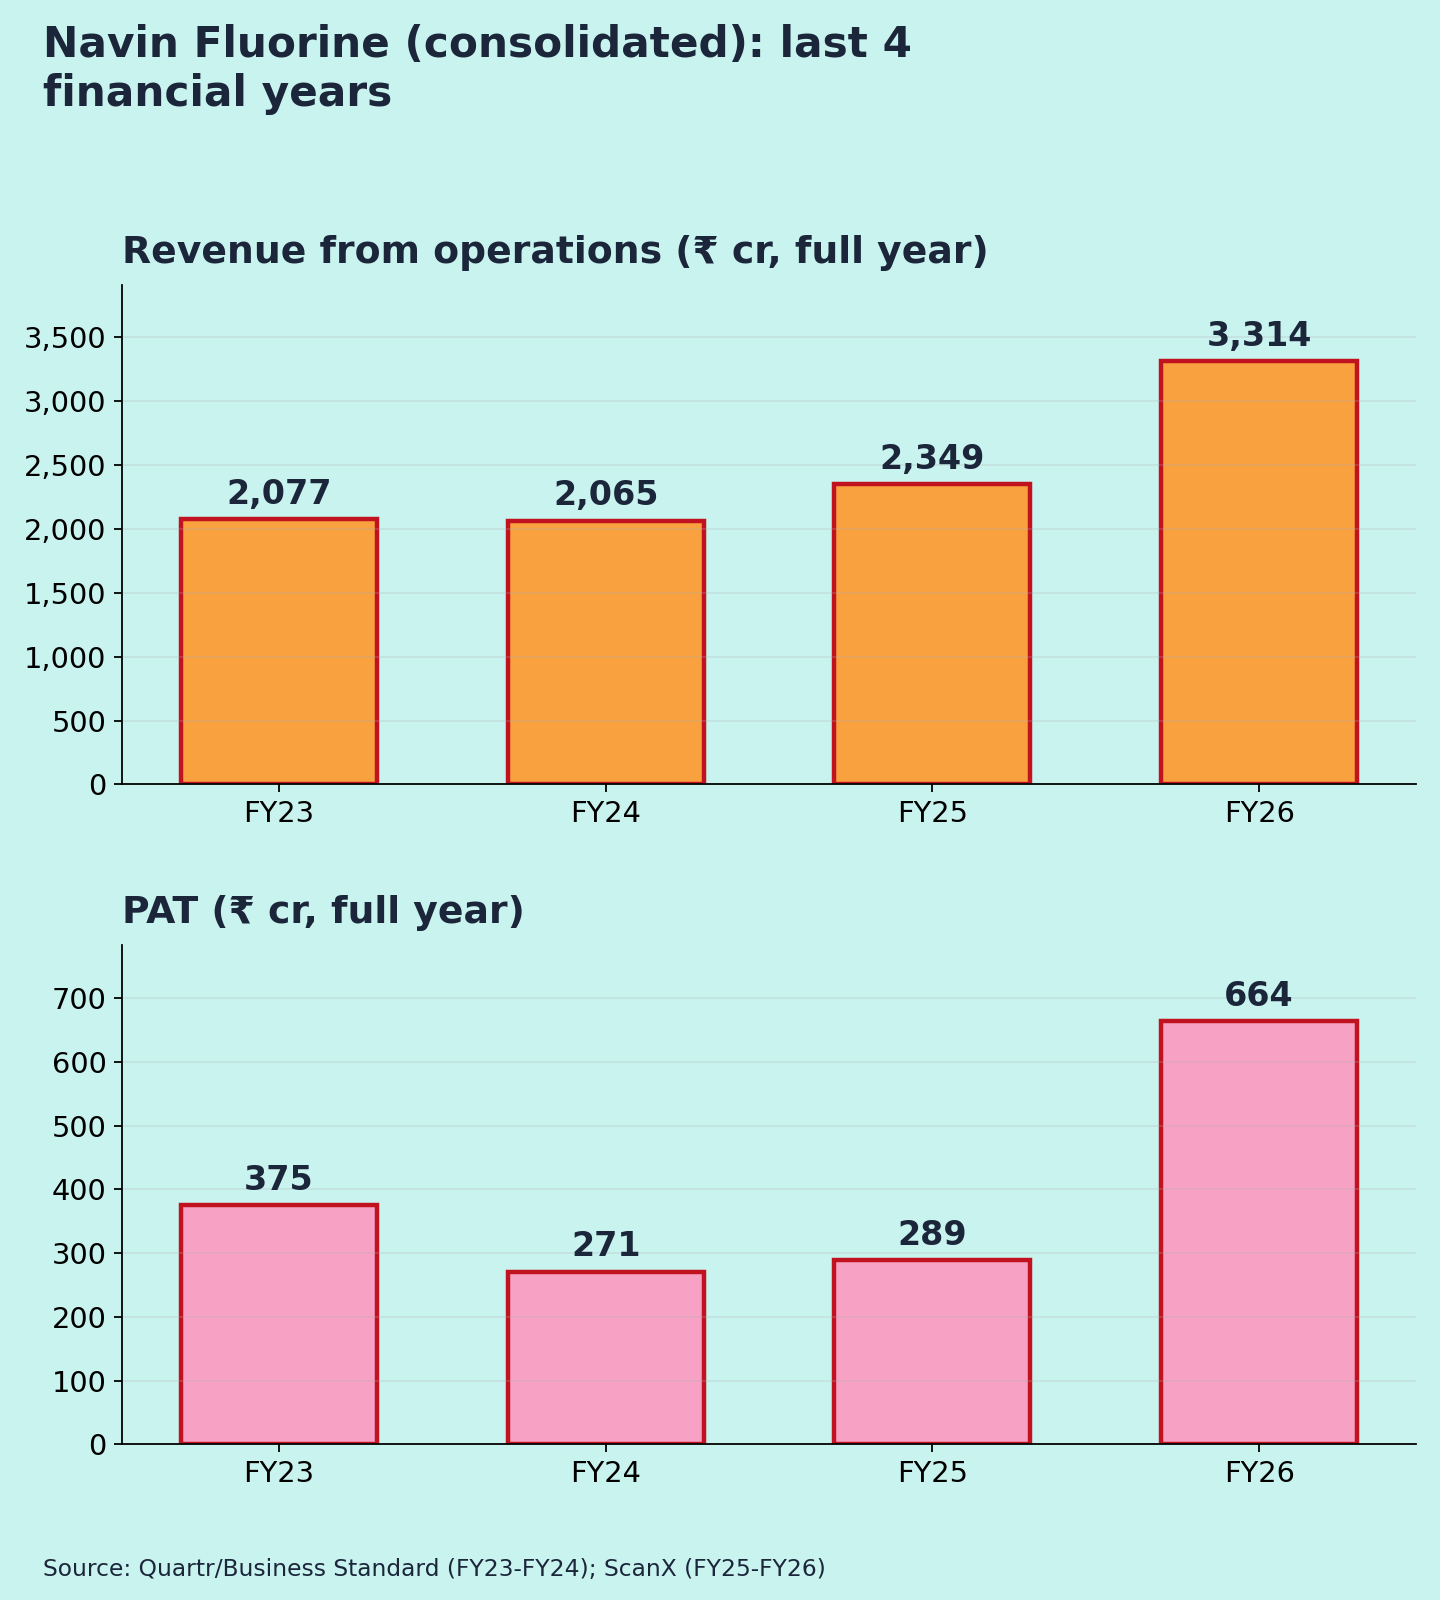
Charts: (1) last 5 quarters revenue & PAT ; (2) FY23–FY26 revenue & PAT; (3) operating EBITDA margin and PAT margin (own calc.).