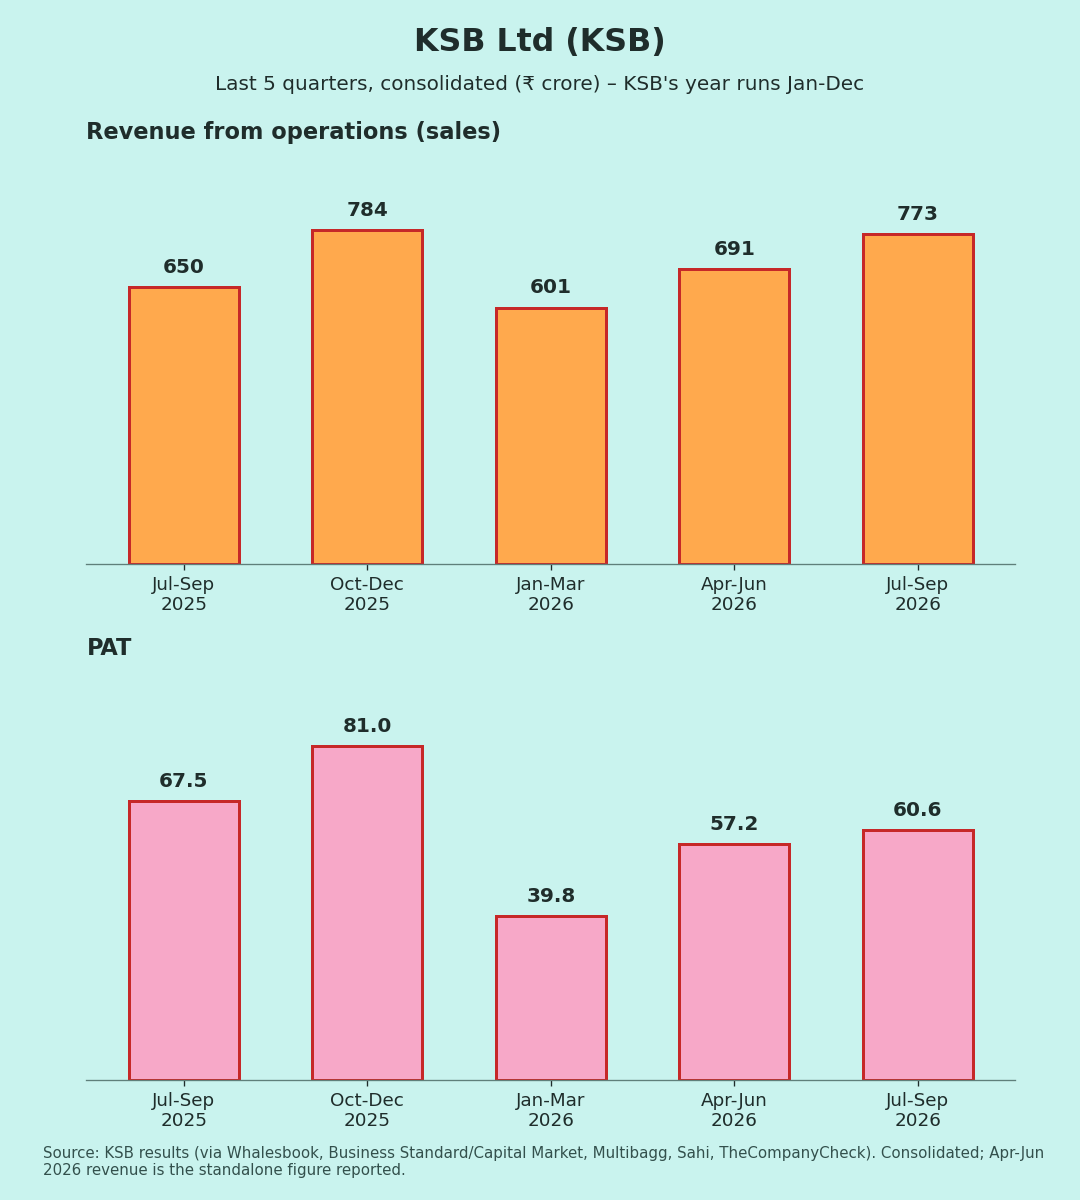
KSB's financial year runs January to December, like its German parent's. So the July–September quarter is its Q3 CY2026, not "Q2 FY27".
Consolidated figures, ₹ crore. Results were filed on 3 Nov 2026. YoY/QoQ % and margins are my calculations.
| Metric | Jul–Sep 2026 | YoY | QoQ |
| Revenue from ops | 772.7 | +18.9% | +11.9% |
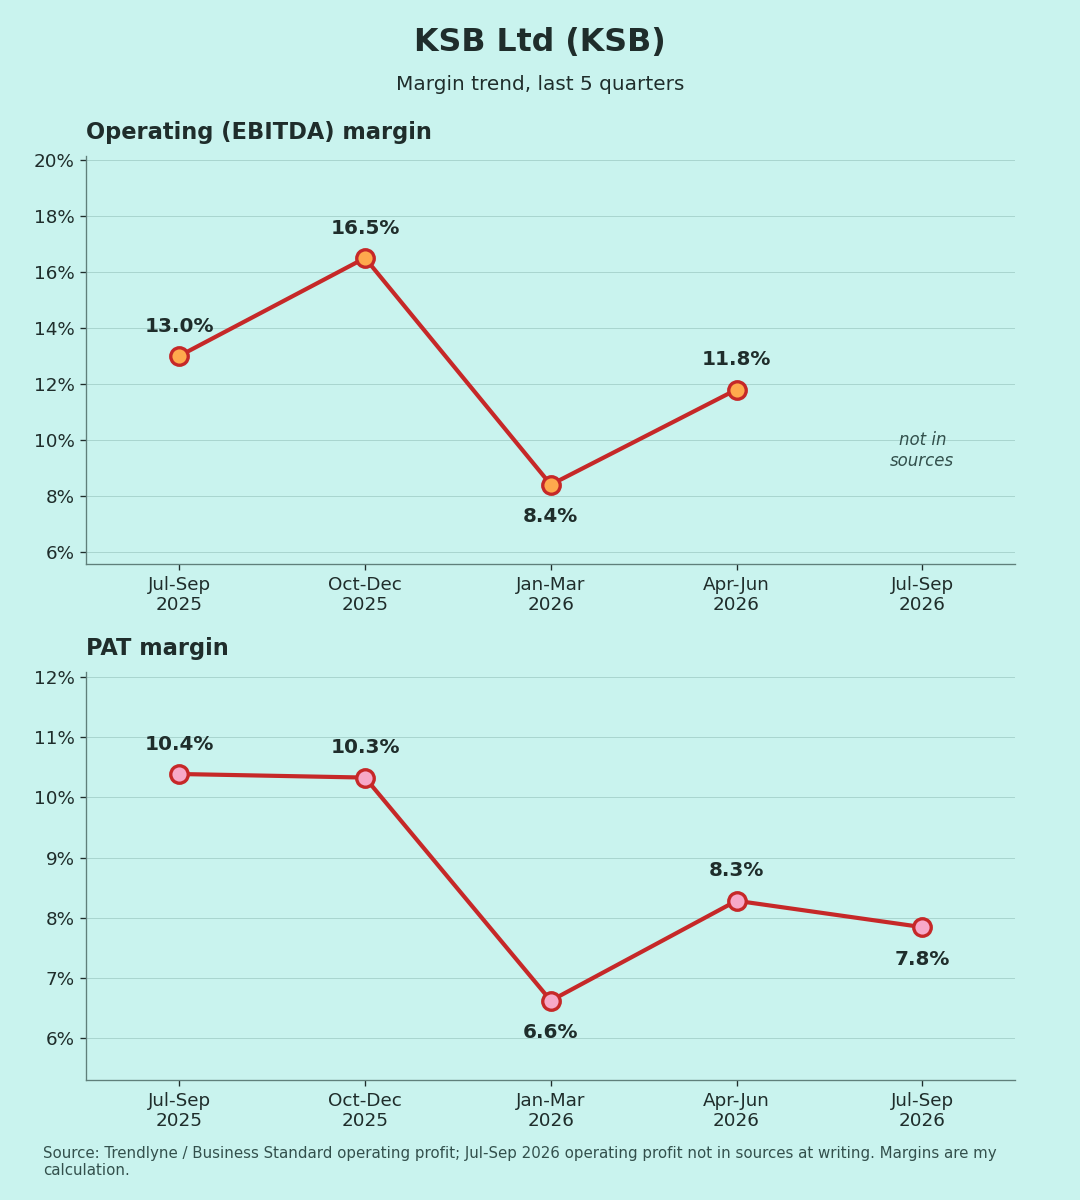
| EBITDA margin | not in sources | 13.0% | 11.8% |
| PAT | 60.6 | −10.2% | +5.9% |
| PAT margin | 7.8% | 10.4% | 8.3% |
| Total expenses | – | +22% | – |
Margin rows show the year-ago and last-quarter values.
Quality of earnings
Sales grew strongly, but profit fell. Total expenses rose 22%, faster than revenue [1]. The Q3 operating-profit line and other income weren't in my sources, so I can't split core and non-core profit yet.
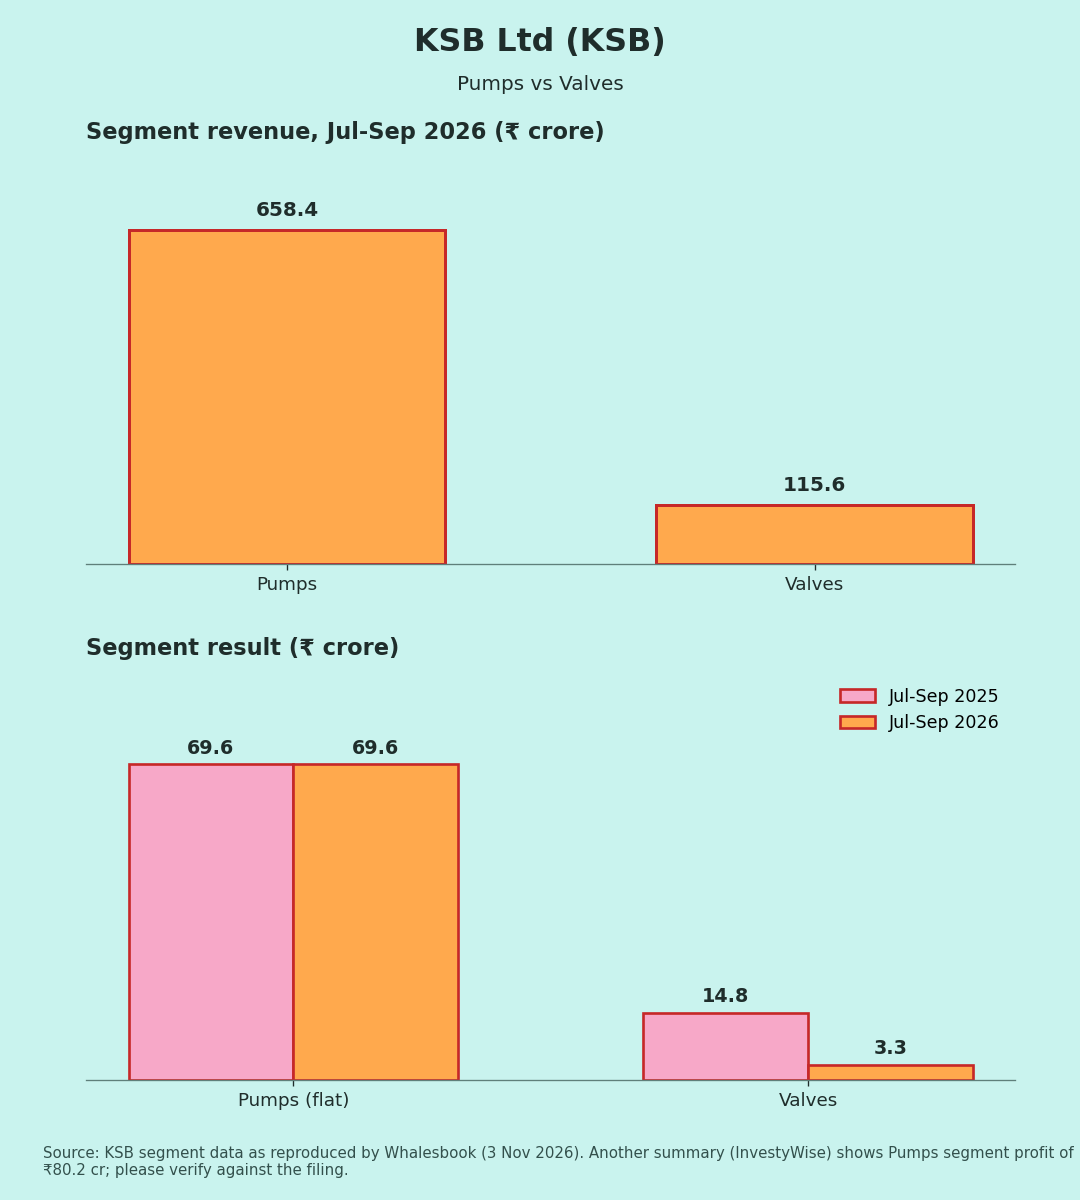
The split is by segment [1]:
- Pumps: revenue ₹658.4 cr, with a segment result that was flat YoY at ₹69.6 cr.
- Valves: revenue slipped to ₹115.6 cr, and the result fell to ₹3.3 cr from ₹14.8 cr.
So most of the profit decline is in Valves. Pumps grew revenue without growing profit, which points to lower margins on the extra sales (my reading).
Source flag: InvestyWise shows Pumps segment profit before tax of ₹80.2 cr and revenue from operations of ₹783.5 cr [2]. These differ from Whalesbook's numbers above. Please check the filing.
Base effect: the year-ago quarter (Jul–Sep 2025) was a normal quarter, with a 10.4% PAT margin [3]. The YoY fall is not a base effect.
Margins (Chart 3)
Operating margin over the last four quarters with data: 13.0% → 16.5% → 8.4% → 11.8% [4][5]. The Jul–Sep 2026 figure isn't available yet. PAT margin over five quarters: 10.4% → 10.3% → 6.6% → 8.3% → 7.8%.
Guidance: what changed
- CY2026 target: double-digit revenue growth, per the H1 presentation [6].
- Progress: nine-month revenue is about ₹2,065 cr [2], up roughly 8% YoY (my calculation). To reach 10% for the year, Oct–Dec needs about ₹900 cr, ~15% above last year's ₹784 cr (my calculation).
- Solar pumps: targeted to grow 20–25% to over ₹300 cr in CY2026 [7].
- Order book: ₹2,585 cr as of the CY2025 results [7].
- Q3 call: no coverage found at writing.
Positives
- Revenue +18.9% YoY
- Pumps revenue holding up
- Profit up 5.9% from Apr–Jun
Concerns
- Costs growing faster than revenue
- Valves profit down sharply
- Double-digit full-year target needs a big Q4 (my calculation)
Things to track (Oct–Dec 2026)
- Valves segment recovery
- Operating margin vs 13–16% in the last two Q4s
- Full-year growth vs the double-digit target
- Solar pump revenue toward ₹300 cr
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Whalesbook – Jul–Sep 2026 results & segments · [2] InvestyWise – filing summary · [3] TheCompanyCheck – quarterly consolidated · [4] Trendlyne – quarterly operating profit · [5] Business Standard – Dec 2025 quarter & CY2025 · [6] StocksBriefer – H1 2026 presentation · [7] Arthneeti – CY2025 call · [8] Multibagg – Apr–Jun 2026 · [9] Business Standard – CY2023
Charts:
(1) last 5 quarters revenue & PAT
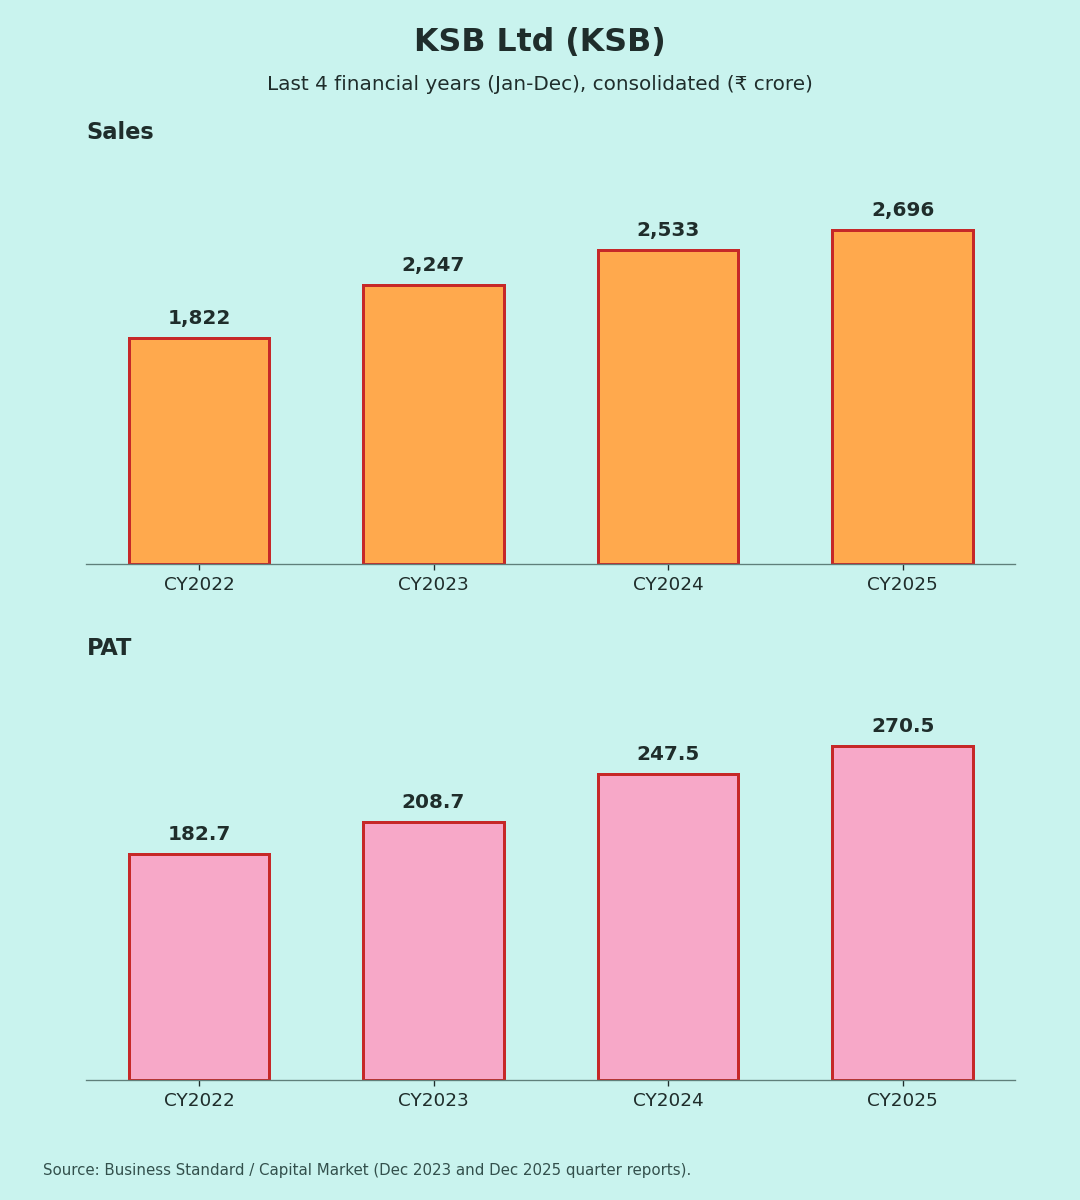
(2) CY2022–CY2025 sales & PAT
(3) operating and PAT margin (own calc.)
(4) Pumps vs Valves [1].