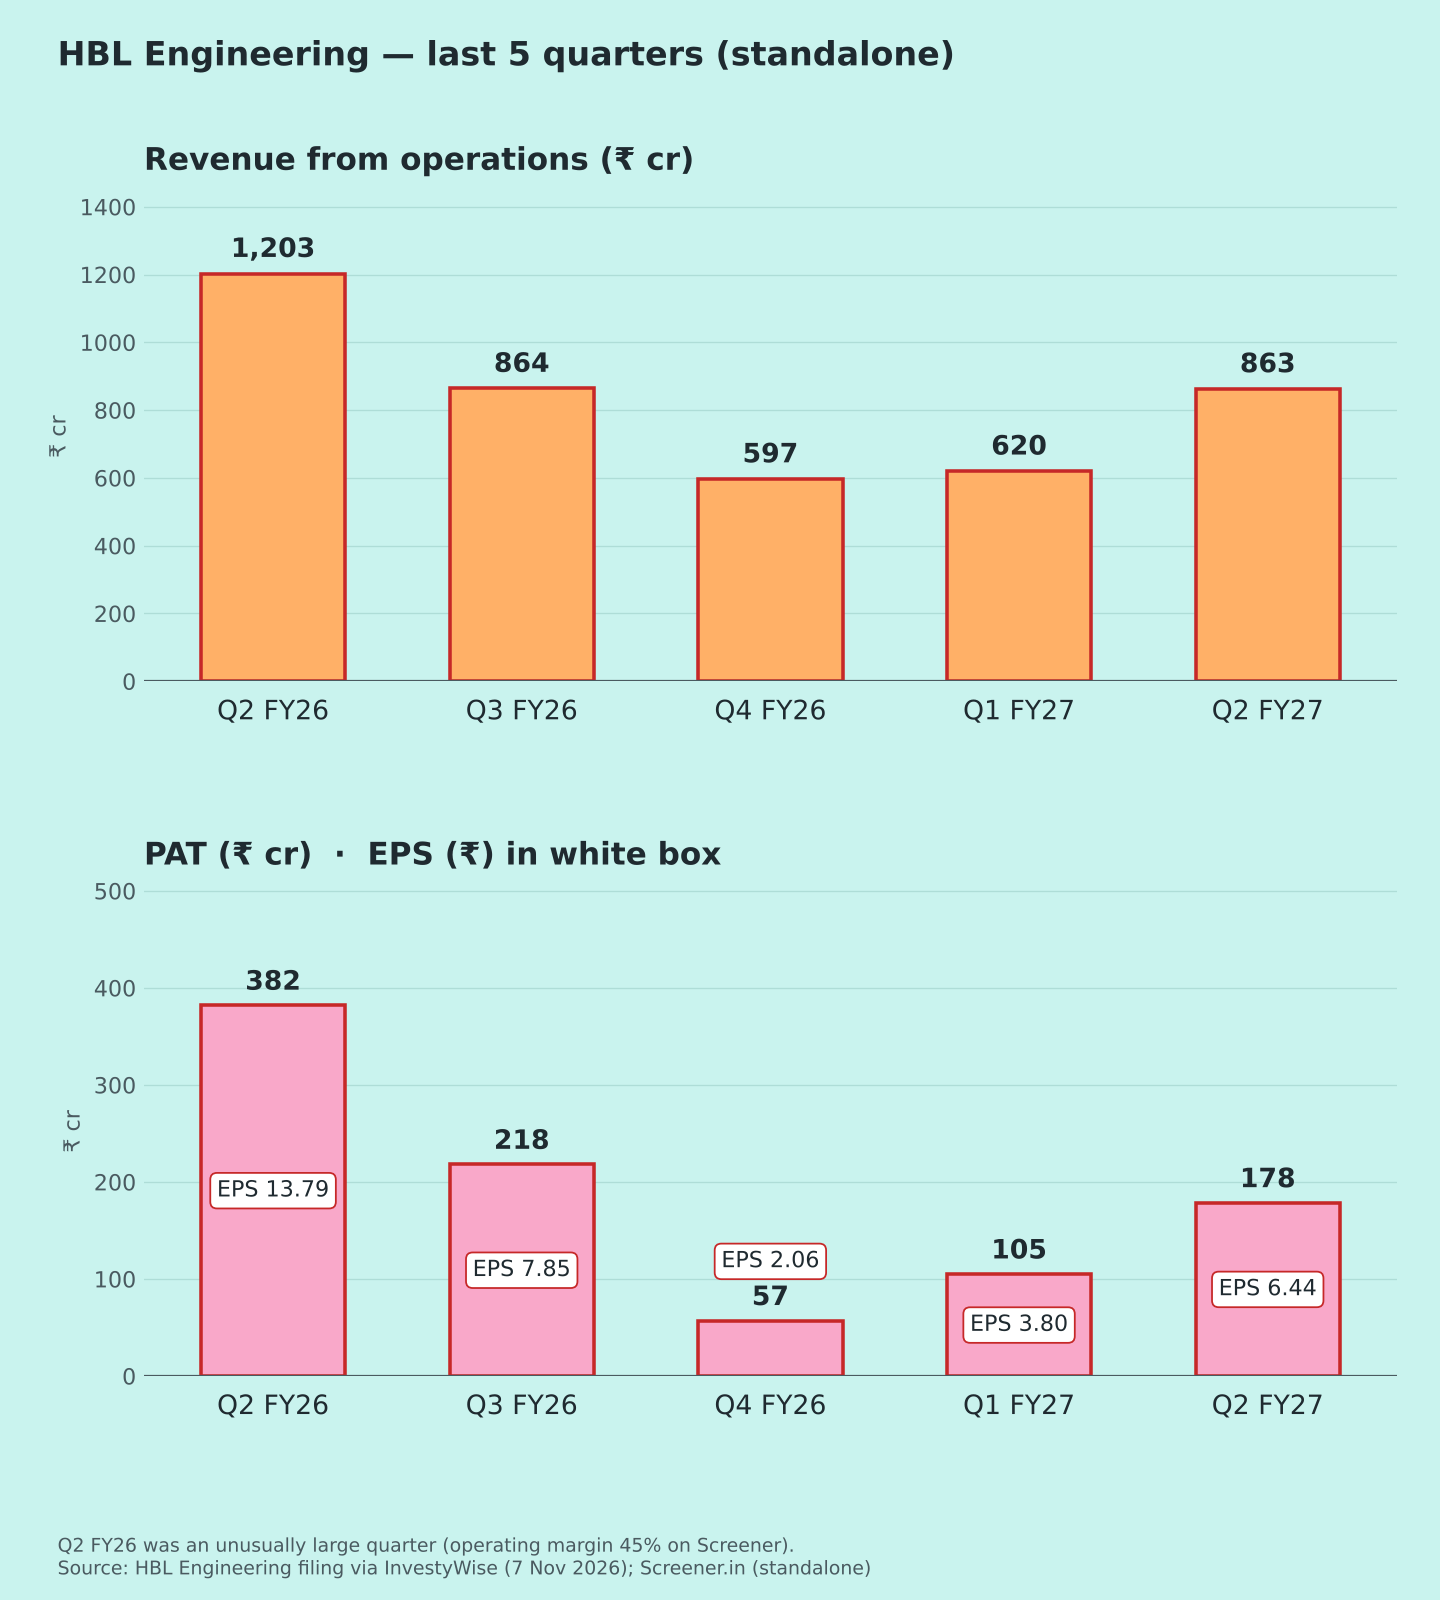
Standalone figures, ₹ crore. These are the most complete figures in coverage and match the history used. The board meeting ran 11:15 am–1:45 pm on 7 Nov 2026 [2]. PAT = standalone PAT. EBITDA, depreciation, finance cost and segment figures weren't in coverage, so they are left out. Q1 FY27 figures are H1 minus Q2, as reported [1].
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 862.94 | −28.3% | +39.3% |
| PBT | 236.35 | −54.1% | +65.9% |
| PAT | 178.46 | −53.3% | +69.2% |
| PAT margin | 20.7% | 31.8% | 16.9% |
| EPS (₹) | 6.44 | −53.3% | +69.5% |
Margin row shows year-ago and last-quarter values. % changes and margins are my calculations. Sources: [1][2][3]
Source notes: Consolidated PAT is ₹185.51 cr [1]. Total income less total expenses (₹223.19 cr) doesn't match the reported PBT of ₹236.35 cr; the ₹13 cr gap isn't explained in coverage. Please check the filing.
Quality of earnings
- The base quarter was exceptional. Q2 FY26 had an operating margin of about 45% on Screener, and PAT of ₹382 cr [3]. Against that, YoY looks weak. QoQ is the fairer read: PAT is up 69% from Q1.
- Other income is small: about ₹15 cr, roughly 6% of PBT (derived).
- Tax rate: about 24.5% (my calculation).
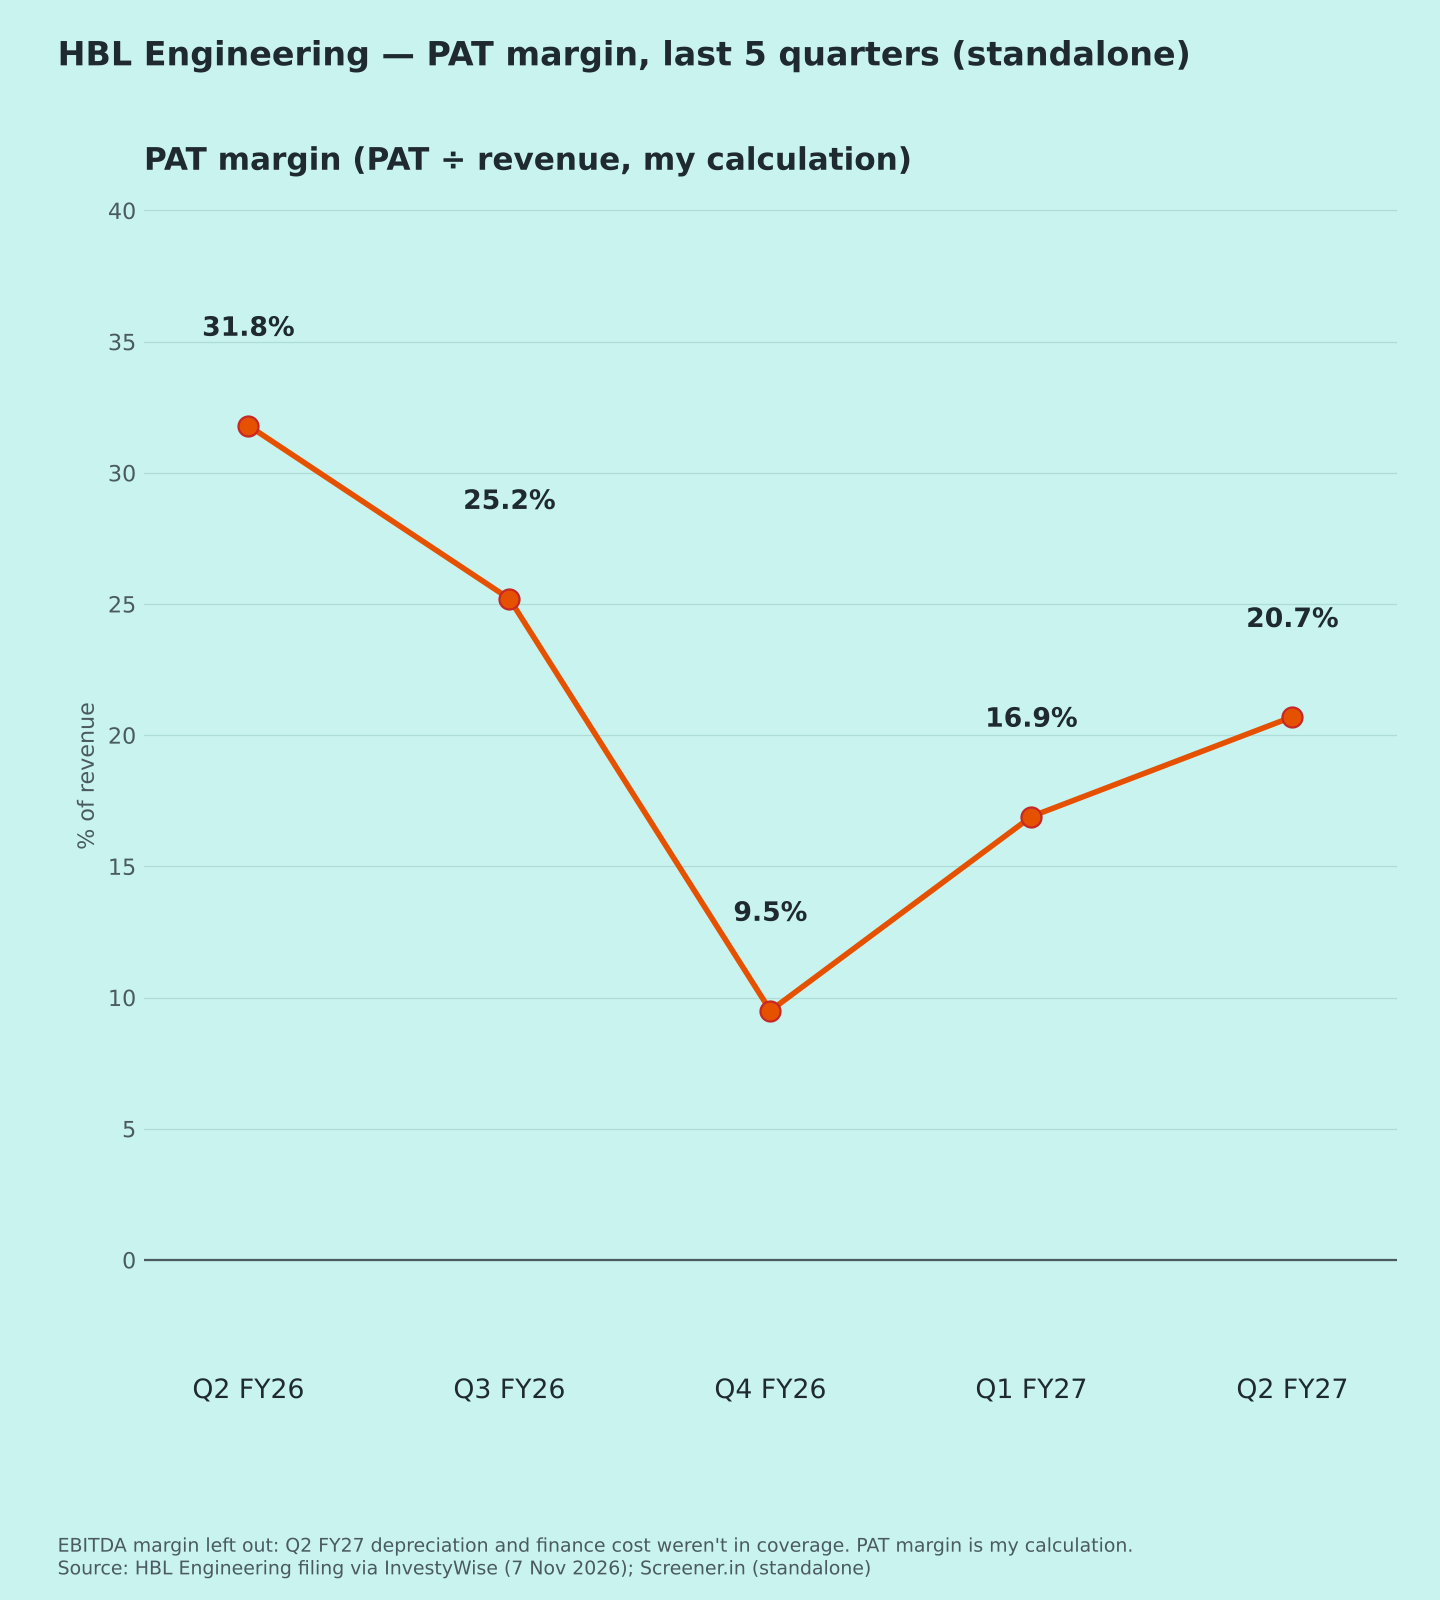
Margins (Chart 3)
PAT margin: 31.8% → 25.2% → 9.5% → 16.9% → 20.7% (my calculation). It is recovering from the Q4 FY26 low but is well below last year's peak.
Kavach and outlook
- Kavach dependence: Kavach (railway anti-collision systems) was about half of FY26 sales [5].
- Lost tender: in Jan 2026 HBL lost a large locomotive Kavach tender (6,300 units) on price [4].
- FY27 target: it guided ₹1,900 cr of Kavach revenue for FY27 (₹1,000 cr locomotive + ₹900 cr station) [4]. Q2 coverage doesn't say whether this target still stands.
- Other updates: Tonbo Imaging, in which HBL has invested, listed on 23 Oct 2026; the company says the investment's impact will show from next quarter [1]. CARE upgraded HBL's long-term rating to AA- in October [3].
Positives
- Strong QoQ recovery [1]
- Rating upgrade [3]
Concerns
- Heavy dependence on Kavach; lost a big tender [4][5]
- Segment and EBITDA detail missing in coverage
Things to track in Q3 FY27
- Kavach order inflow and deliveries
- Whether the ₹1,900 cr Kavach target is reaffirmed
- The Tonbo investment's accounting impact
- Segment mix once the filing is reviewed
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – Q2 FY27 results · [2] InvestyWise – board outcome · [3] Screener.in – standalone · [4] ScanX – Kavach tender & FY27 target, Jan 2026 · [5] Screener.in – consolidated (annual report summary)
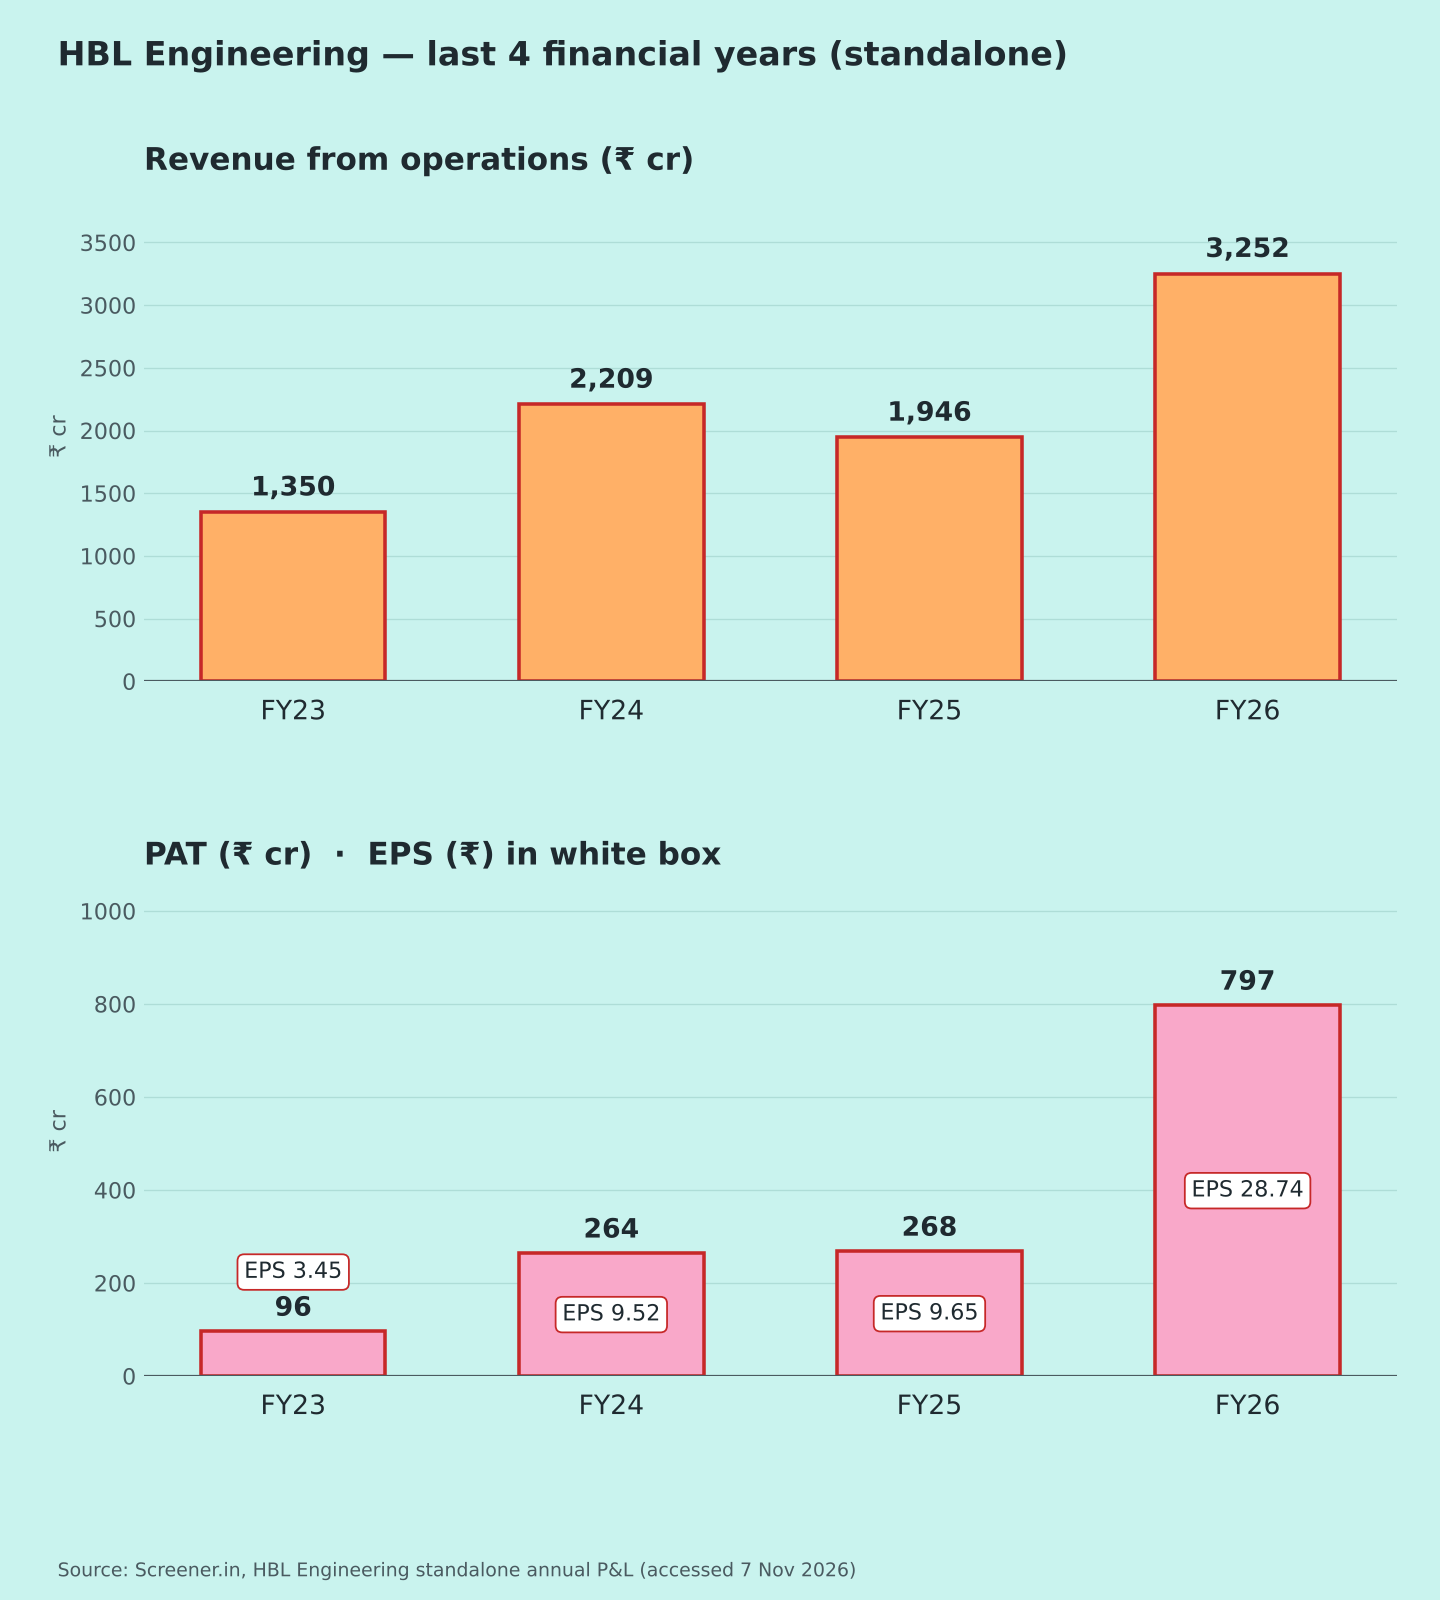
Charts: (1) 5 quarters revenue & PAT with EPS [1][3]; (2) FY23–FY26 [3]; (3) PAT margin [1][3]; (4) headline [1][3]. No segment chart: no segment data in coverage.