Skip to content

Bhansali Engineering Polymers

Bhansali Engineering Polymers Limited · NSE: BEPL · BSE: 500052

Registered research

Notes by SEBI-registered analysts, each with the analyst’s registration number and disclosures. Open a note to read its disclosures.

No registered research on this company yet.

Member discussion

Members’ own views, with what each disclosed about their holding when posting.

Vishal @vishal #2

Q2 FY27 summary (quarter ended 30 Sep 2026)

On a year-on-year basis this was a strong quarter. Consolidated revenue increased 24.1% from ₹325.10 crore to ₹403.37 crore, and consolidated net profit rose 54.4% from ₹40.45 crore to ₹62.46 crore. Margins also improved: Q2 EBITDA was ₹78.9 crore, up 60.69% from ₹49.1 crore, with EBITDA margin expanding 450 bps to 19.6% versus 15.1% a year ago (standalone figures). The board announced a ₹1 per share second interim dividend, taking total interim dividend to ₹2 per share.

Despite this, the shares closed at ₹117.46 today, down 8.63%.

Why the market punished it

No outlet has stated the reasons for the fall outright, so the following is my reading of the numbers and the announcement.

  1. The expansion delay is the main issue. The ₹200 crore expansion project, originally due by September 2026, has been hampered by external factors. The company announced a six-month delay in its ABS capacity expansion due to global supply chain and geopolitical disruptions. The project takes capacity from 75,000 to 100,000 TPA and is now due March 2027. That is roughly a third more capacity, and it was the main reason to expect growth. As recently as April, management confirmed the expansion remained on schedule, with commissioning expected by end-September 2026. A missed timeline after that reassurance hurts credibility.
  2. The quarter was weaker than Q1. Q1 FY27 had revenue of ₹472 cr and PAT of ₹66 cr. Compared with that, Q2 revenue fell about 15% and PAT fell about 5%. The market had probably taken Q1’s level as the new normal. The margin held up, which suggests lower volumes or prices rather than a cost problem.
  3. The year-ago comparison was weak. In Q2 FY26, revenue fell 11.4% YoY and net profit fell 12.7% YoY. That makes this year’s +24% and +54% look bigger than the underlying trend.
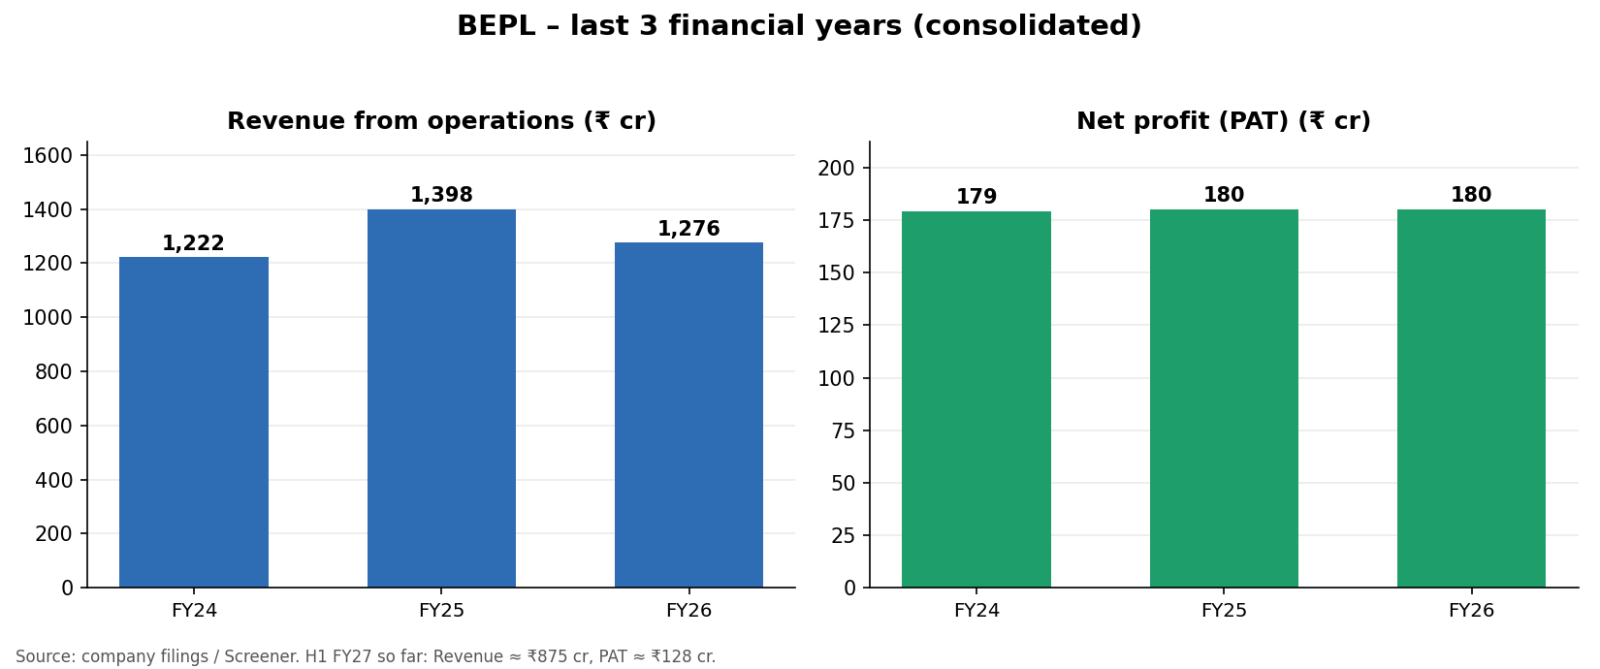
  4. The stock had already run up, and growth has been flat. Before results, the market cap was around ₹3,239 crore, up 33.7% in a year, which works out to roughly ₹128–130 per share. Meanwhile, the company has delivered sales growth of -0.25% over the past five years. Annual PAT has been stuck around ₹180 cr for three years. With the new capacity pushed out, the case for a re-rating weakens.

There are positives the market may be overlooking. On current numbers the company is almost debt free, with a dividend payout of around 55%, a P/E of 14.8 and a dividend yield of 3.32%.
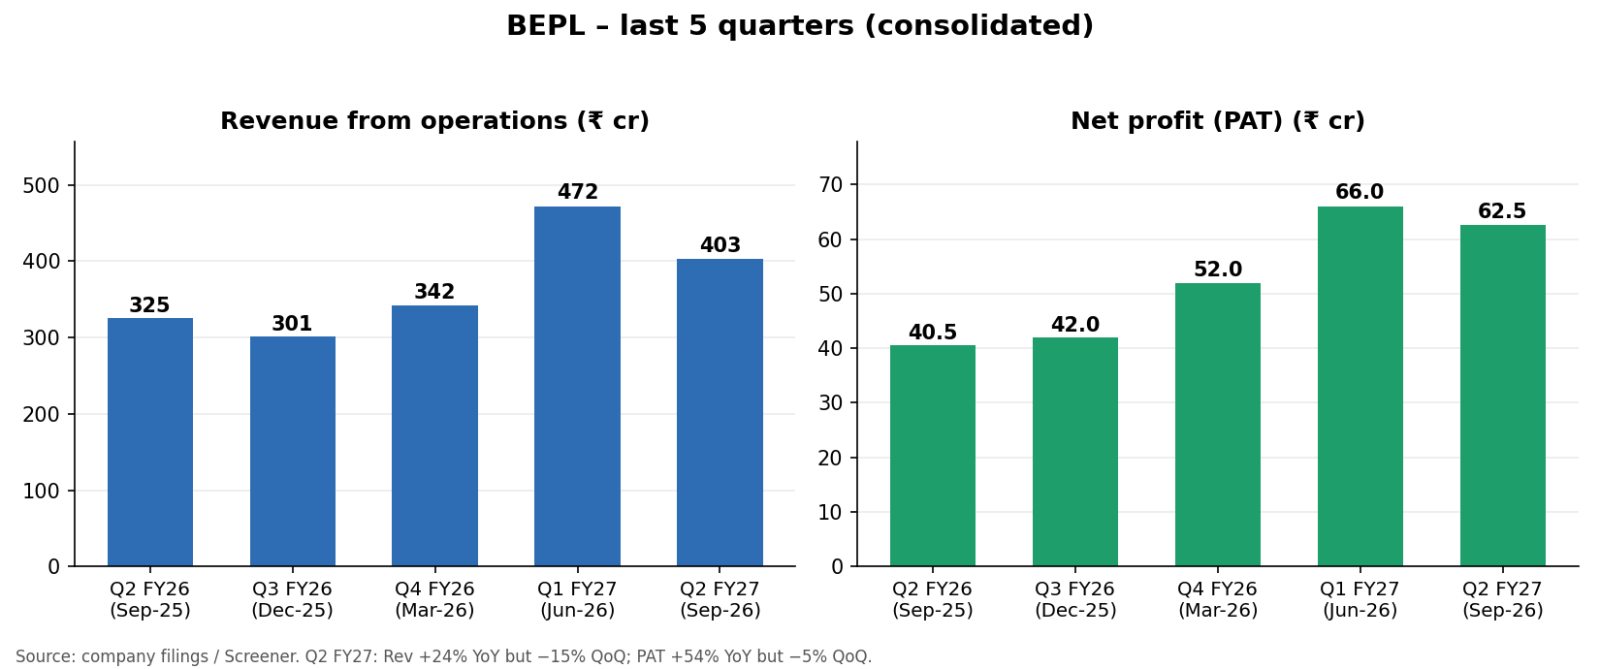
BEPL Quarterly comparison
BEPL Year on Year Results
Author's disclosure: Invested
Arun @arun #1

These are my notes on Bhansali Engineering Polymers (BSE 500052, NSE BEPL) from 18 July 2026 to now. The figures are as the company disclosed them, through the sources listed below.

Q1 FY27 results (board meeting, 18 July 2026). Consolidated revenue from operations was about ₹472 crore, against about ₹308 crore a year earlier, roughly 53% higher. Net profit was about ₹65.6 crore against about ₹45.9 crore, roughly 43% higher. The reported EBITDA margin was 19.2%, down from 20.0%, so profit grew more slowly than revenue. The company also filed a revised press release that day, and I haven’t checked what changed.

Dividend. The board declared a first interim dividend for FY27 of Re 1 per share (face value Re 1). The record date was 23 July 2026, with payment on or before 16 August 2026.

AGM (21 July 2026). The 42nd AGM was held by video conference. It approved a final dividend of Re 1 per share for FY26, on top of three interim dividends of Re 1 each. It also re-appointed a director who retired by rotation and appointed him Whole-Time Director for three years.

Capacity expansion. The company says it is debottlenecking its plants to raise ABS capacity from 75,000 to 100,000 MTPA. The cost is about ₹200 crore, paid for from internal accruals. It was aiming to commission the work in September 2026, with optimal utilisation in FY28. I couldn’t find any filing that says whether it has been commissioned. Reports also differ on whether the work is at Abu Road only or at both Abu Road and Satnoor.

Income tax penalty (17 September 2026). The company disclosed a penalty of ₹79.66 lakh under Section 270A for assessment year 2018-19, from an order dated 16 September. It says there is no material impact and that it intends to appeal.

Solar plant (reported around 9 October 2026). A 1,300 kW DC ground-mounted solar plant has been commissioned at the Satnoor unit, at a capex of about ₹6.42 crore, to raise the share of renewable energy in its power use.

Coming up. The company has announced a board meeting for Monday, 19 October 2026, and the corporate-action listing says the board will consider a dividend. I haven’t confirmed whether Q2 results are on the agenda.

Questions for members: has anyone seen a filing confirming the 100,000 MTPA debottlenecking was commissioned in September? And does anyone know how much of that capacity is at each plant?

Sources:

BSE filings, 18 Jul 2026: Board meeting outcome, Q1 results, Press release (revised), Record date

Value Research: board meeting outcome, 18 Jul 2026

FilingReader: dividend record and payment dates, 18 Jul 2026

Business Standard: Q1 figures, 20 Jul 2026

Business Standard: EBITDA and expansion, 20 Jul 2026

Kalkine: investor presentation summary, 20 Jul 2026

BSE: AGM outcome, 21 Jul 2026, and ScanX: AGM report, 21 Jul 2026

BSE: tax penalty disclosure, 17 Sep 2026, and ScanX: tax penalty report, 17 Sep 2026

BSE: solar plant filing, about 9 Oct 2026; ScanX: solar plant, 9 Oct 2026; Construction World: solar plant, 14 Oct 2026

BSE: board meeting intimation for 19 Oct, about 14 Oct 2026

Author's disclosure: Invested Reduced

Posts are members’ own views and are not investment advice. Holdings shown are what each member disclosed when posting. Research notes are by SEBI-registered analysts under their own registration; Mudraa hosts them and does not endorse them.

To take part, Log in or Join. Members verify their email and phone and agree to the community rules.

Report this

Tell the moderators what is wrong. The member is not told who reported them.

Reason