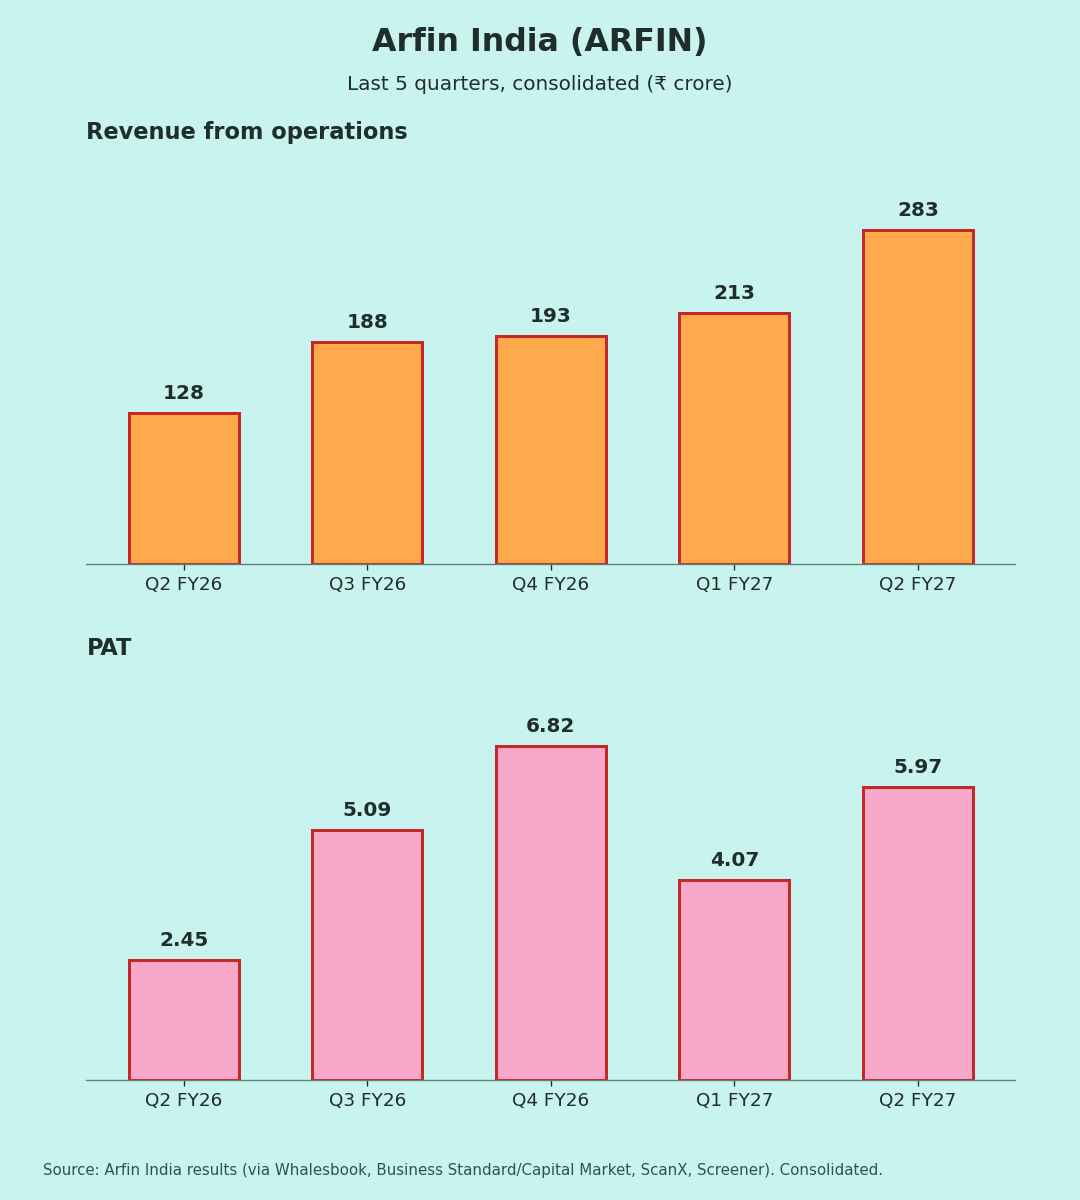
Consolidated figures, ₹ crore. Results were approved on 3 Nov 2026. At the time of writing, coverage of the filing gives revenue, PAT and EPS only. YoY/QoQ % and margins are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 283.2 | +121.3% | +33.1% |
| Operating margin (ex-OI) | not yet available | 7.3% a year ago | 4.8% last quarter |
| PAT | 5.97 | +143.7% | +46.7% |
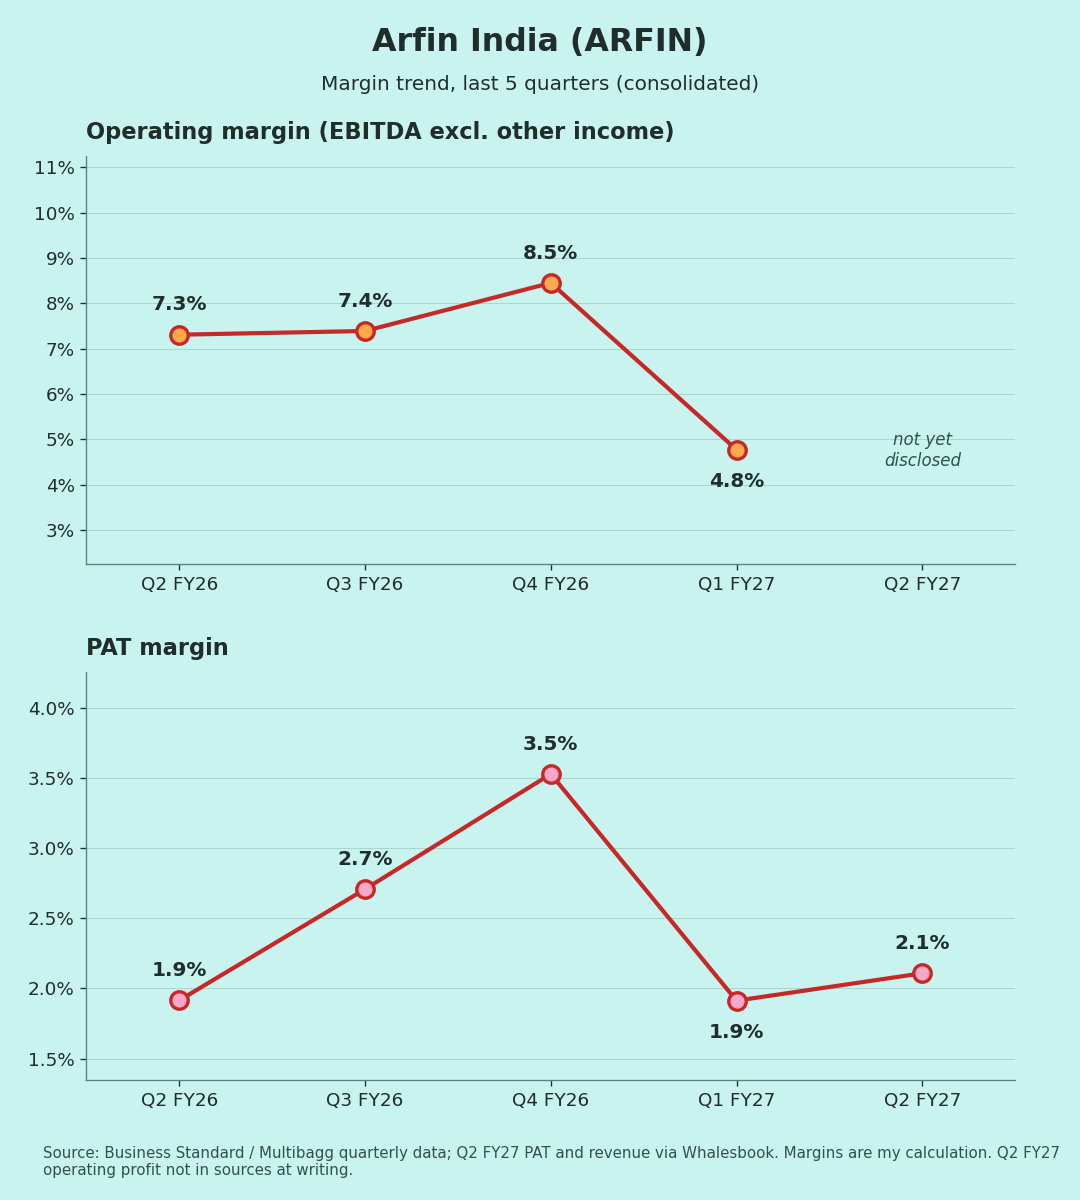
| PAT margin | 2.1% | 1.9% | 1.9% |
| H1 FY27 revenue | 496.0 | +109.4% | – |
| H1 FY27 PAT | 10.0 | +184.4% | – |
Standalone Q2 PAT was ₹5.6 cr vs ₹2.05 cr [5].
What the company does
Arfin makes aluminium products such as alloy ingots, wire rods and AAAC conductors for power lines. It reports a single business segment. Revenue moves with aluminium prices and order execution, so margins are thin by nature.
Quality of earnings
Revenue more than doubled, and PAT grew faster. But the PAT margin is still only ~2%, roughly where it was a year ago (my calculation). So most of the profit growth came from volume, not from better margins.
Two flags:
- Weak base: Q2 FY26 revenue had fallen 14% YoY [2]. Part of the +121% is that low starting point.
- Tax change: The company has opted for a concessional tax rate under the new Income Tax Act, which affects its deferred tax [1]. Q1 FY27's tax rate was only ~12%, against 25–37% in the previous four quarters [4]. Until the Q2 tax line is visible, some PAT growth may be tax-driven (interpretation).
Interest is heavy for the size of the business: FY26 finance cost was ₹18.7 cr against PBT of ₹23.7 cr [6][7].
Margins (Chart 3)
Operating margin: 7.3% → 7.4% → 8.5% → 4.8% over the four reported quarters. Q1 FY27 halved from Q4. Q2 FY27 is not yet available, so I can't say whether that dip reversed.
Management commentary / orders
Recent order disclosures:
- Diamond Power Infra: ₹321 cr, 11,000 MT of conductor, Jan–Nov 2026 [9]
- DGVCL: ₹85.6 cr AAAC conductor order, May–Nov 2026 [10]
- JFE Shoji: ₹180 cr of ingots and wire rods, Oct 2025–Mar 2026 [11]
Most of these end by November 2026. New order flow matters for H2 (my view).
The board also declared an interim dividend of ₹0.12 per share [1].
Positives
- Revenue +121% YoY, +33% QoQ
- H1 PAT nearly 3x last year
- Unmodified auditor review report
Concerns
- Thin margins (~2% PAT) leave little buffer against aluminium price swings
- Possible tax-driven boost to PAT
- High interest relative to profit [6]
- Large orders mostly end by Nov 2026
Things to track in Q3 FY27
- Q2 operating margin and tax rate, once the full filing is available
- New order wins to replace the expiring contracts
- Finance cost trend
- Aluminium prices (LME)
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Whalesbook – Q2 FY27 filing, 3 Nov 2026 · [2] Business Standard/Capital Market – Q2 FY26 · [3] Business Standard – quarterly results · [4] Screener.in – consolidated · [5] Sahi – standalone Q2 FY27 · [6] INDmoney – annual P&L · [7] Free Press Journal – Q4 FY26 · [8] Multibagg – Q1 FY27 figures · [9] Business Standard – Diamond Power order · [10] Univest – Q4 FY26 & DGVCL order · [11] Business Standard – JFE Shoji order · [12] Business Standard – FY24 results · [13] ScanX – Q1 FY27
Charts:
(1) last 5 quarters revenue & PAT
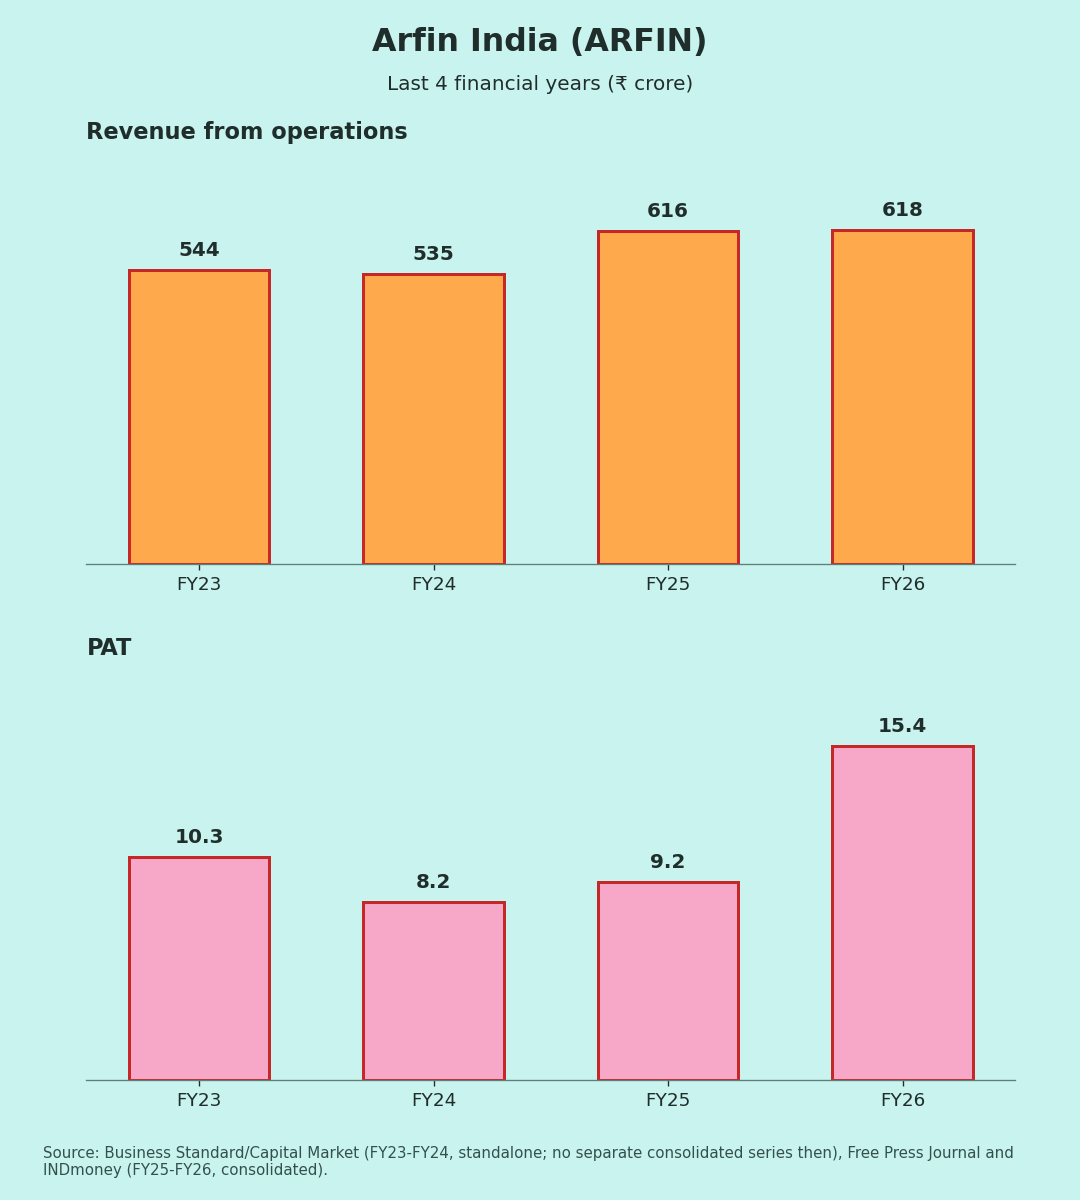
(2) FY23–FY26 revenue & PAT: FY23–FY24 standalone, FY25–FY26 consolidated
(3) operating margin (Q2 FY27 not yet available) and PAT margin (own calc.).