Elevate Campuses (ELEVATE): Q1 FY27 results analysis (quarter ended 30 Jun 2026)
Why Q1: Q2 FY27 results are not out yet. ELEVATE listed on 30 Sep 2026 [3], and its first filed results (19 Oct) cover the June quarter. A Reuters headline calls the ₹34.06 cr profit "Sept-quarter" [6], but it matches the Q1 figure exactly, so it looks mislabelled.
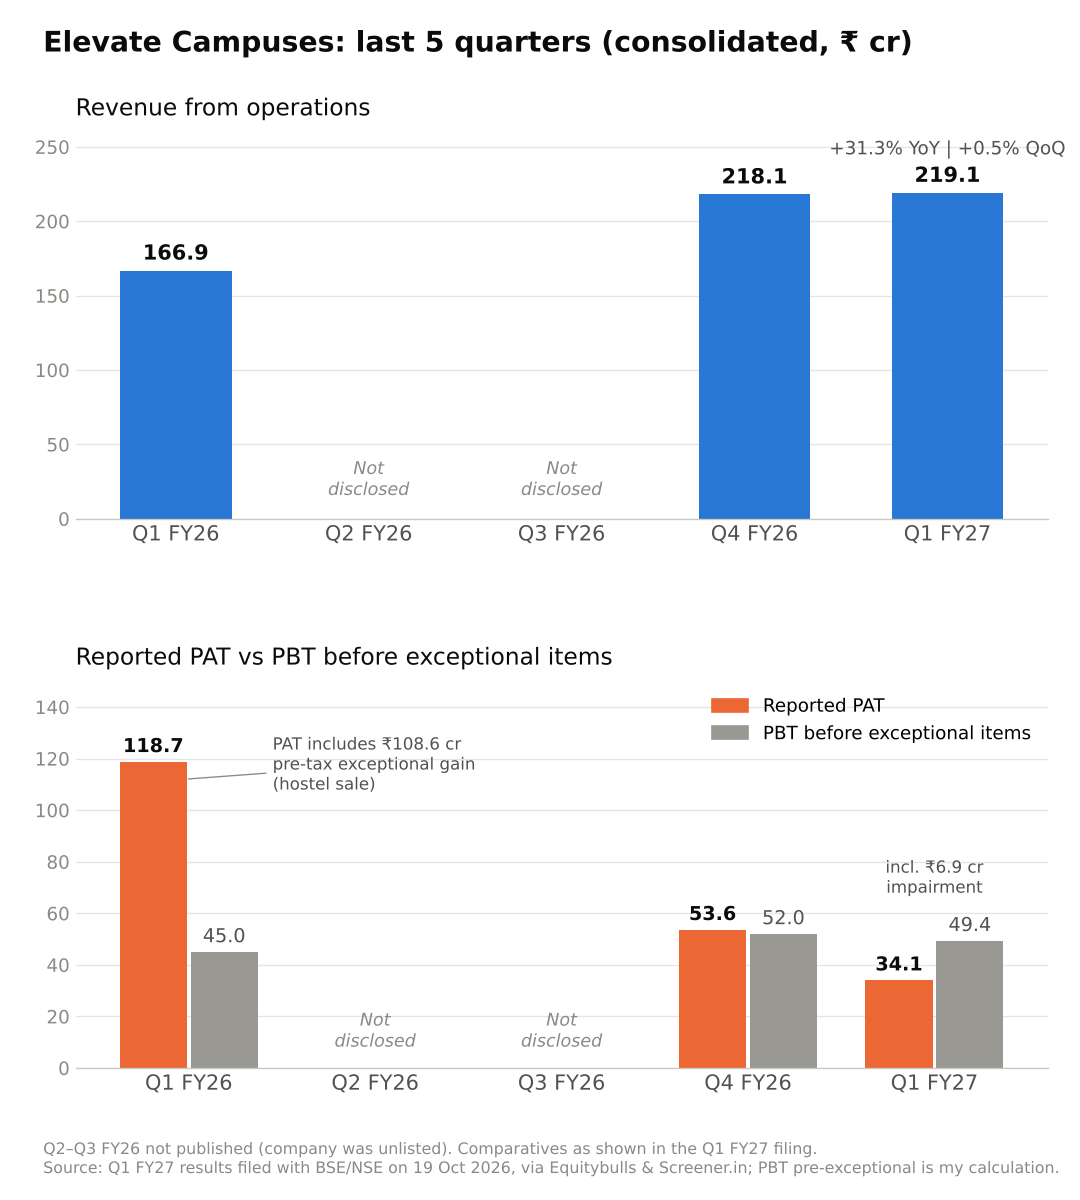
Figures are consolidated, in ₹ crore, from the Q1 FY27 filing as reproduced by [1][2] and cross-checked with Screener [4]. % changes and margins are my calculations. Q2–Q3 FY26 were never published (the company was unlisted).
| Metric | Q1 FY27 | YoY | QoQ |
| Revenue from ops | 219.1 | +31.3% | +0.5% |
| EBITDA (company definition, incl. other income) | 173.6 | +27.1% | +1.2% |
| EBITDA excl. other income | 164.7 | +29.3% | +0.8% |
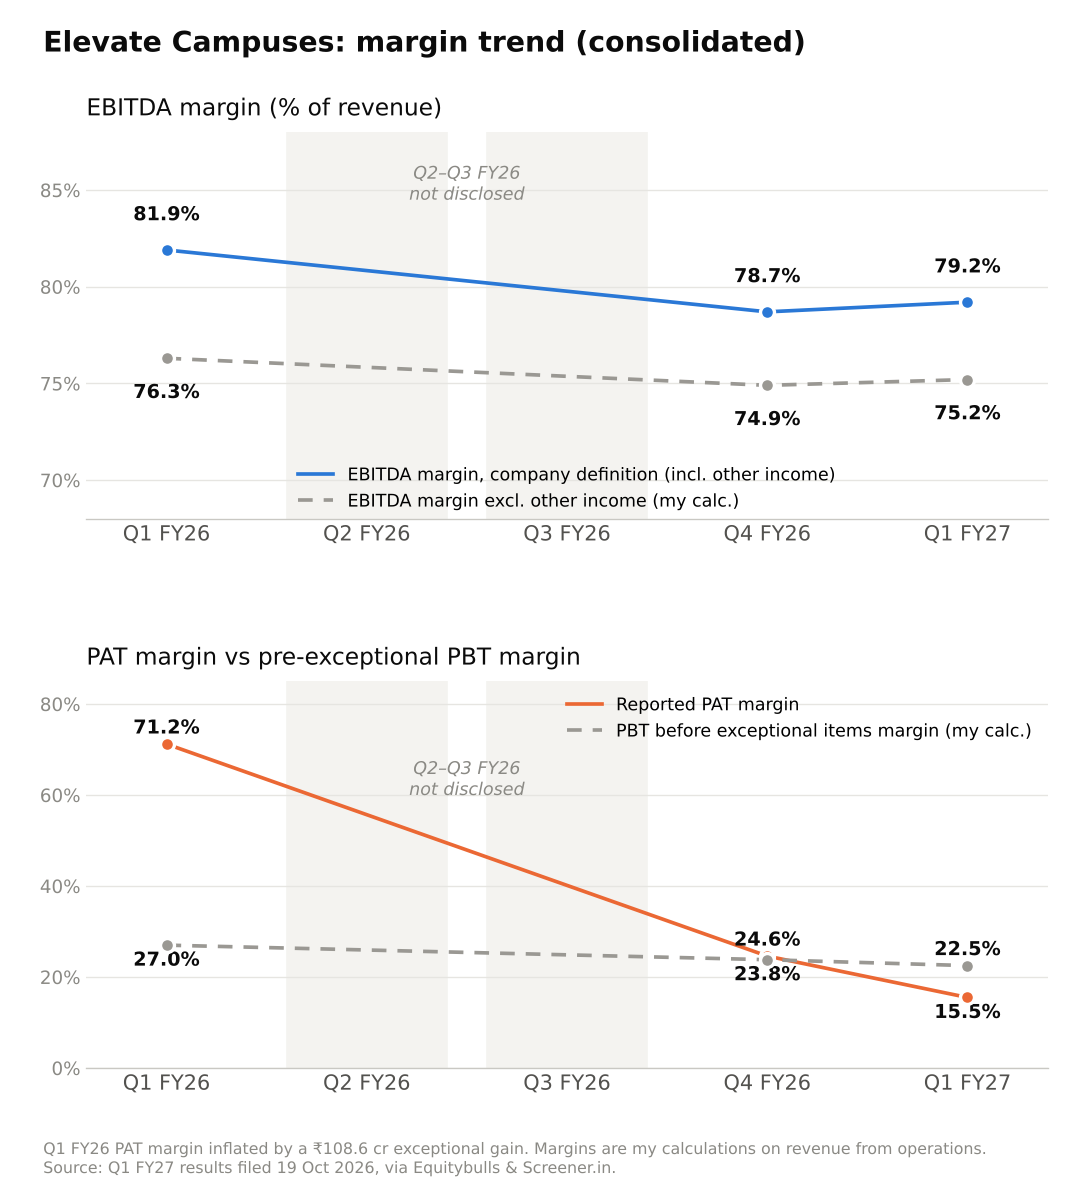
| EBITDA margin excl. other income | 75.2% | 76.3% | 74.9% |
| Finance cost | 83.0 | n/a | +4.2% |
| PBT before exceptional items | 49.4 | +9.6% | −5.1% |
| PAT | 34.1 | −71.3% | −36.5% |
| PAT margin | 15.5% | 71.2% | 24.6% |
| Other income / PBT | 21.0% | 6.0% | 15.7% |
For margin and ratio rows, the YoY and QoQ columns show the prior-period value. Sources: [1][2][4].
Quality of earnings
PAT −71% YoY is a high-base effect. Q1 FY26 included a ₹108.6 cr exceptional gain from selling a hostel undertaking. Q1 FY27 carries a ₹6.9 cr impairment of goodwill and intangibles [1]. On a pre-exceptional basis, PBT rose 9.6% YoY (my calculation).
Source flags: Multibagg quotes the gain as ₹109.4 cr, the standalone figure [5]. Screener nets the impairment into other income (₹2 cr vs ₹8.9 cr filed) [4].
Finance cost was ₹83.0 cr, or 38% of revenue, and EBITDA covers interest only ~2.1x. The tax rate was 19.7%, against a tax credit in Q4 FY26 (PAT above PBT) [1]. That credit flattered Q4, so the −36.5% QoQ PAT decline overstates the deterioration.
Growth was largely acquired [2]:
- K-12 outside India (Dubai schools, acquired Sep 2025 [7]) rose from ₹17.1 cr to ₹57.7 cr, about 78% of the YoY increase.
- Student accommodation rose 14.4% to ₹114.7 cr.
- K-12 India fell 5.5% to ₹46.8 cr.
Margins (Chart 3)
The company's 79.2% EBITDA margin includes other income. Excluding it: 76.3% → 74.9% → 75.2% (Q1 FY26, Q4 FY26, Q1 FY27), broadly stable. No segment margins were disclosed in the sources I found.
Pre-exceptional PBT margin slid from 27.0% to 22.5% over the same three quarters. Acquisition-linked interest rose from ~₹65 cr to ₹83 cr, and D&A from ~₹26 cr to ₹41 cr [4] (interpretation).
Guidance and what changed vs the RHP
No earnings call found; points below are from filing/presentation summaries [2][5].
- Occupancy: Owned beds were 95% occupied as of 1 Jul 2026, vs 89.4% for FY26 [2][8]. The Woodstock hostel (1,162 beds) reopened in July, as the RHP had said [8].
- Beds: Managed beds rose to 58,174 from 55,487 in March [2][9], even though the RHP flagged the termination of two ScholarZ contracts covering 4,480 beds [7].
- K-12 deal: The RHP earmarked ₹1,100 cr for 16 K-12 assets [8]. After the quarter, the company bought 14 K-12 entities for ₹1,115.7 cr [5][10]. I couldn't confirm whether the scope changed.
- Debt: ₹750 cr of IPO money goes to repayment [8]. On 8 Oct it disclosed USD 62.02m into Elevate UAE to repay debt by Oct 2026 [4].
Market reaction (interpretation)
Results came out between about 8:30 and 9 pm on 19 Oct [2][10], and 20 Oct was a market holiday (Dussehra) [11]. On 21 Oct the stock opened at ₹300 against a previous close of ₹313.90, hit a low of ₹299, and was last seen at ₹304.40 (−3.0%) [12]. Intraday figures; the close may differ. The stock is ~16% below its ₹362 IPO price [3].
Likely reasons: headlines saying "PAT −71%" without the base effect, flat QoQ revenue, the impairment, and a heavy interest burden.
Positives
- Pre-exceptional PBT up 9.6% YoY, and EBITDA excluding other income up 29% [1]
- Owned-bed occupancy recovered to 95% [2]
- Student accommodation up 14% YoY [2]
- IPO proceeds earmarked to cut debt [8]
Concerns
- Finance cost at 38% of revenue, with interest cover ~2.1x (my calculation)
- An impairment in the first quarter reported as a listed company [1]
- Related-party acquisitions. The RHP flags a benami notice on the PE Bowenpally asset and 100% pledges at the promoter holding companies [8]
Things to track
- Q2 FY27 results date: By my reading of LODR's 45-day rule, they should be due by mid-November. Quartr shows 18 Jan 2027 [13], so the sources differ.
- Finance cost after the ₹750 cr repayment.
- Occupancy at ~95%, and the managed-bed count.
- The 14 new K-12 entities: their revenue contribution, and the status of the Bowenpally case.
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Equitybulls – Q1 FY27 consolidated & standalone · [2] ScanX – Q1 FY27, segments, beds · [3] Chittorgarh – listing day · [4] Screener.in – ELEVATE · [5] Multibagg – Q1 FY27 · [6] TradingView/Reuters headline · [7] Listings Tracker – RHP notes · [8] Value Research – IPO review · [9] Kotak Neo – RHP figures · [10] Whalesbook – Q1 FY27 · [11] Outlook Business – 2026 market holidays · [12] Groww – ELEVATE quote, 21 Oct · [13] Quartr – events · [14] Finology Ticker – IPO analysis
Charts: (1) quarterly revenue & PAT [1][4];
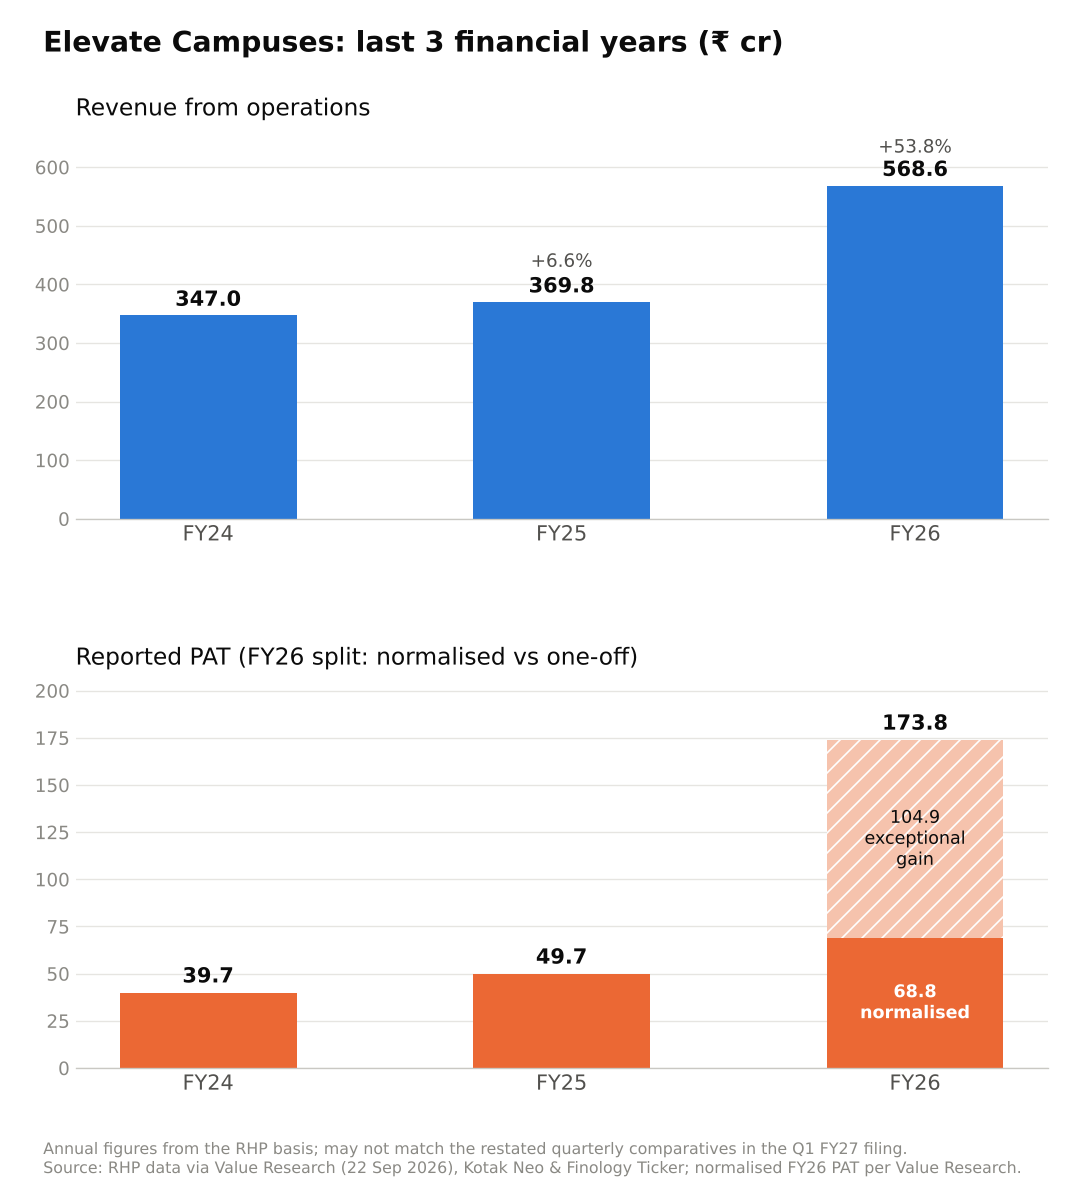
(2) FY24–FY26 revenue & PAT, RHP basis, which may not match the restated quarterly comparatives [8][9][14];
(3) margin trend (own calculations from [1]).