Delta Corp (DELTACORP): Q2 FY27 results analysis (quarter ended 30 Sep 2026)
All figures are consolidated, in ₹ crore unless stated. Results were filed on 19 Oct 2026 [1][3]. YoY/QoQ %, margins and ratios are my own calculations.
| Metric | Q2 FY27 | Q2 FY26 | Q1 FY27 | YoY | QoQ |
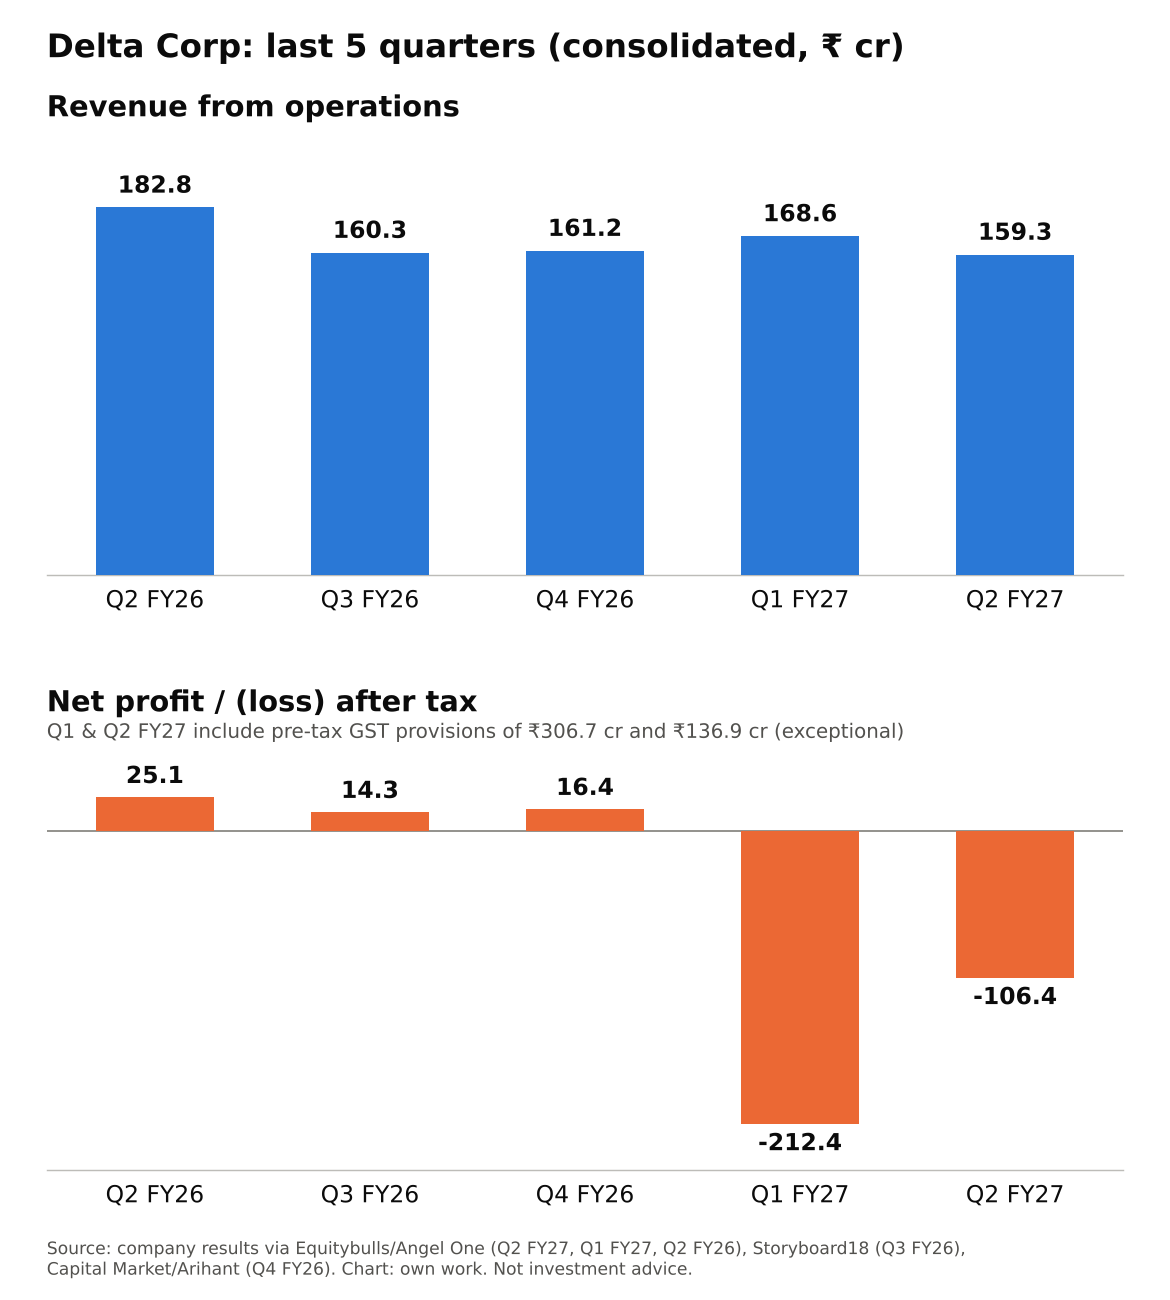
| Revenue from ops | 159.34 | 182.76 | 168.55 | −12.8% | −5.5% |
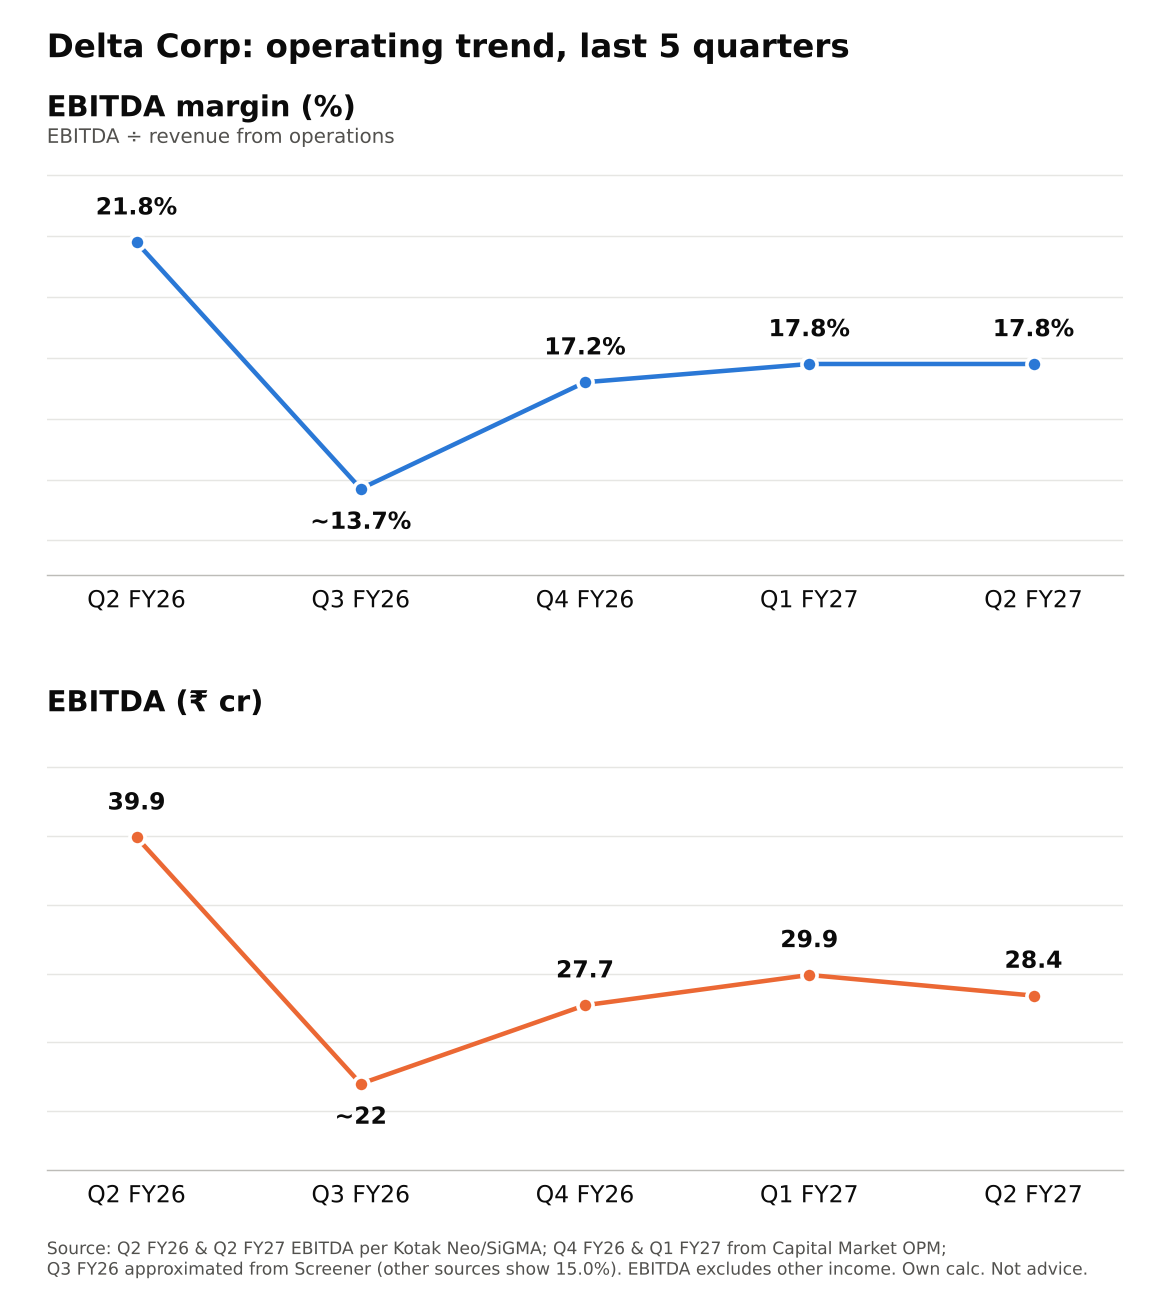
| EBITDA (ex-OI) | 28.4 | 39.9 | 29.9 | −28.8% | −5.0% |
| EBITDA margin | 17.8% | 21.8% | 17.8% | −400 bps | flat |
| PBT before exceptional items | 21.57 | 34.69 | 27.74 | −37.8% | −22.2% |
| Exceptional (GST) | (136.92) | – | (306.73) | ||
| PAT | (106.41) | 25.10 | (212.42) | n.m. | n.m. |
| PAT margin | n.m. | 13.7% | n.m. | ||
| Other income / pre-exceptional PBT | 21.8% | 22.8% | 34.6% |
Sources: [1][2][4][5]. Q1 EBITDA is derived from Capital Market's 17.75% OPM [5].
Source differences: Kotak Neo and SiGMA put EBITDA at ₹28.4 cr with a 17.9% margin [4][2]. Focus Gaming News says ~₹29 cr and 18% [6]. ₹28.4 cr ÷ revenue gives 17.8%.
Quality of earnings
The loss is driven by provisions. Before the GST charge, the business still made a profit, but a smaller one: pre-exceptional PBT fell 38% YoY [1]. Other income (₹4.71 cr) was about a fifth of that figure.
The exceptional charge of ₹136.9 cr follows the Supreme Court's 27 May 2026 GST ruling and later adjudication orders. Including Q1's ₹306.7 cr, the H1 total is ₹443.7 cr, interest included [1][2]. Of Q1's charge, ₹148.5 cr was interest and ₹14.4 cr penalty [7]. After the quarter ended, the company paid ₹80.97 cr of GST principal [2]. It says it booked these provisions "on a prudence basis" and will contest the demands [2]. My calculation shows an implied tax credit of about ₹9.5 cr [3].
Base effect. The YoY fall is not flattered by a weak base; if anything, it's the opposite. GST on chips rose to 40% from 22 Sep 2025 [8], so Q2 FY26 revenue was booked almost entirely under the old rate. Revenue has held at ₹159–169 cr for four quarters since then [1][5][9]. My reading is that QoQ is the fairer comparison this time.
Where revenue fell. Standalone casino revenue slipped only 3% YoY, to ₹119.1 cr. Subsidiaries' casino revenue fell 38%, to ₹32.2 cr (my calculation from [1]). That fits with King Casino being shut for all of H1 (interpretation). Hospitality revenue fell 53% QoQ because The Deltin, Daman was closed for 37 days after floods [3]. Its segment loss widened to ₹4.54 cr from ₹2.74 cr [2].
Margins (Chart 3)
EBITDA margin over five quarters went 21.8% → ~14% → 17.2% → 17.8% → 17.8% [4][5][10]. The step down in Q3 FY26 lines up with the higher GST rate (interpretation). Since then, margins have been stable even with King Casino, Sikkim and Daman closures. Casino segment profit rose 33.7% QoQ to ₹26.7 cr [11].
Source note: estimates for Q3 FY26 vary: ~14% (Screener [10]), 15.0% (ScanX [9]) and EBITDA of ₹31.5 cr (Kotak Neo [12]).
Guidance: what changed
- New Goa vessel: In Jan 2026, management targeted induction by March 2026 and operations from April 2026 [13]. The FY26 annual report (Aug 2026) moved this to "FY 2026-27" [8]. In Q2, King Casino stayed shut. Reopening now needs certificates and prior Bombay High Court permission, and no date has been given [11].
- Sikkim: Deltin Denzong was discontinued in May 2026 [8].
- Unchanged (no update in Q2): Panjim hotel-casino targeted for Q1 FY28, Alibaug hotel for H1 FY28, and the demerger for FY27 [8].
Market reaction (interpretation)
On 19 Oct the stock closed 5.1% lower at ₹76.89 [3][4]. I couldn't confirm whether the filing came before or after the close. 20 Oct was a market holiday, and 21 Oct data wasn't available at the time of writing.
The fall followed a sharp rally: from ₹58.39 on 21 Sep to a 52-week high of ₹87.99 on 30 Sep [14][15]. Final Goa GST orders (₹116.43 cr demand plus ₹37.11 cr penalty) came in far below earlier show-cause amounts [15][16]. Likely reasons for the fall: profit-taking after that run, a further ₹137 cr provision, and core PBT down 38%.
Positives
- EBITDA margin steady near 18% for three quarters [5][4]
- Casino segment profit up 33.7% QoQ [11]
- Final GST orders much smaller than show-cause notices [16]
Concerns
- Real cash outflows: ₹81 cr paid, with interest at 18% p.a. and penalties on top [2][16]
- The King Casino timeline has slipped twice, with no date now [13][8][11]
- Daman licence matter now before the Supreme Court [17]
- New orders keep arriving, e.g. a Sikkim order of ₹3.08 cr plus an equal penalty [18]
Things to track in Q3 FY27
- Approvals for the King Casino vessel and Bombay HC permission
- Further GST provisions, payments and appeal outcomes
- Q3 revenue and margin on a like-for-like base (both quarters at 40% GST)
- Demerger and Panjim project milestones
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Equitybulls, 19 Oct 2026 · [2] SiGMA · [3] Angel One · [4] Kotak Neo · [5] Capital Market via JM Financial – Q1 FY27, Q2 FY26, Q4 FY26/FY26 · [6] Focus Gaming News · [7] Multibagg – Q1 FY27 · [8] Annual Report FY26 (NSE) · [9] ScanX – Q3 FY26 · [10] Screener · [11] AGBrief, 20 Oct 2026 · [12] Kotak Neo – Q3 FY26 · [13] Storyboard18 – Q3 FY26 · [14] MarketsMojo · [15] Business Today, 5 Oct 2026 · [16] Sahi – GST orders · [17] Whalesbook · [18] NSE filing, 15 Oct 2026 · [19] Business Standard – FY24 · [20] Business Standard – FY25
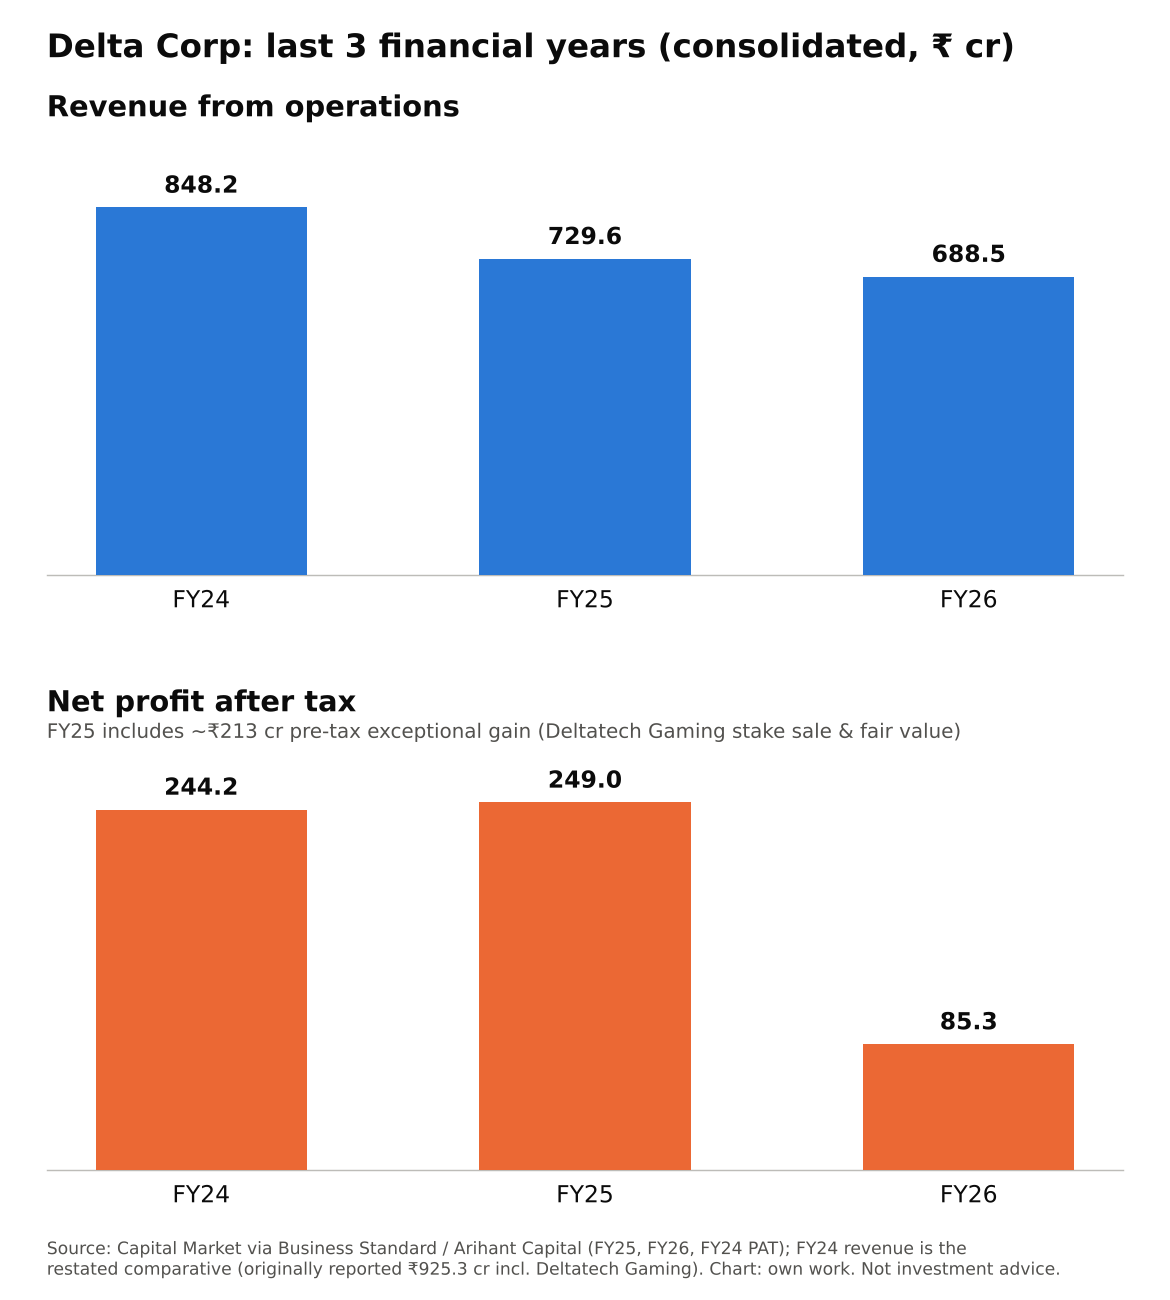
Charts: (1) last 5 quarters revenue & PAT [1][5][13]; (2) FY24–FY26 revenue & PAT [5][19][20]; FY24 revenue is the restated comparative; (3) EBITDA margin & EBITDA trend [4][5][10].