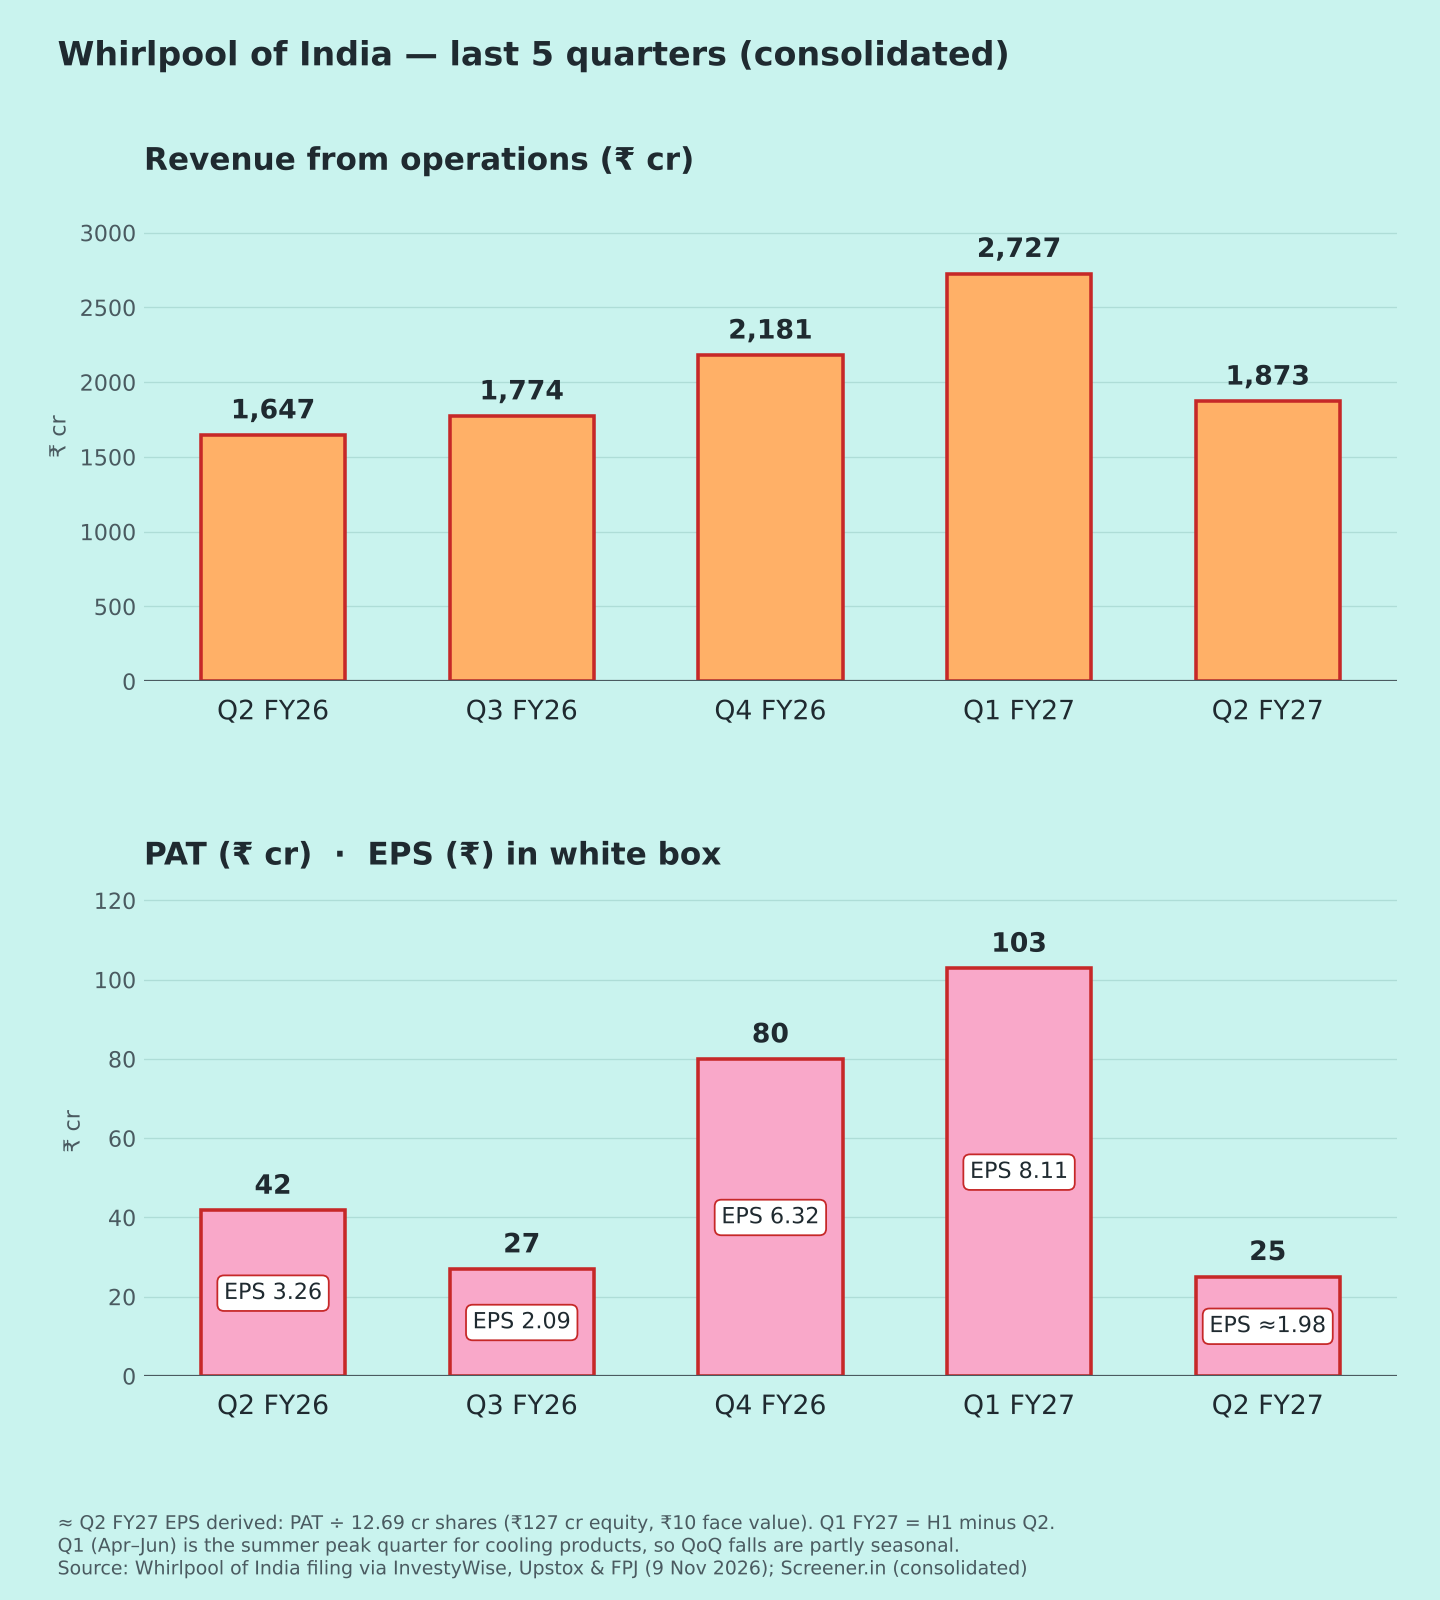
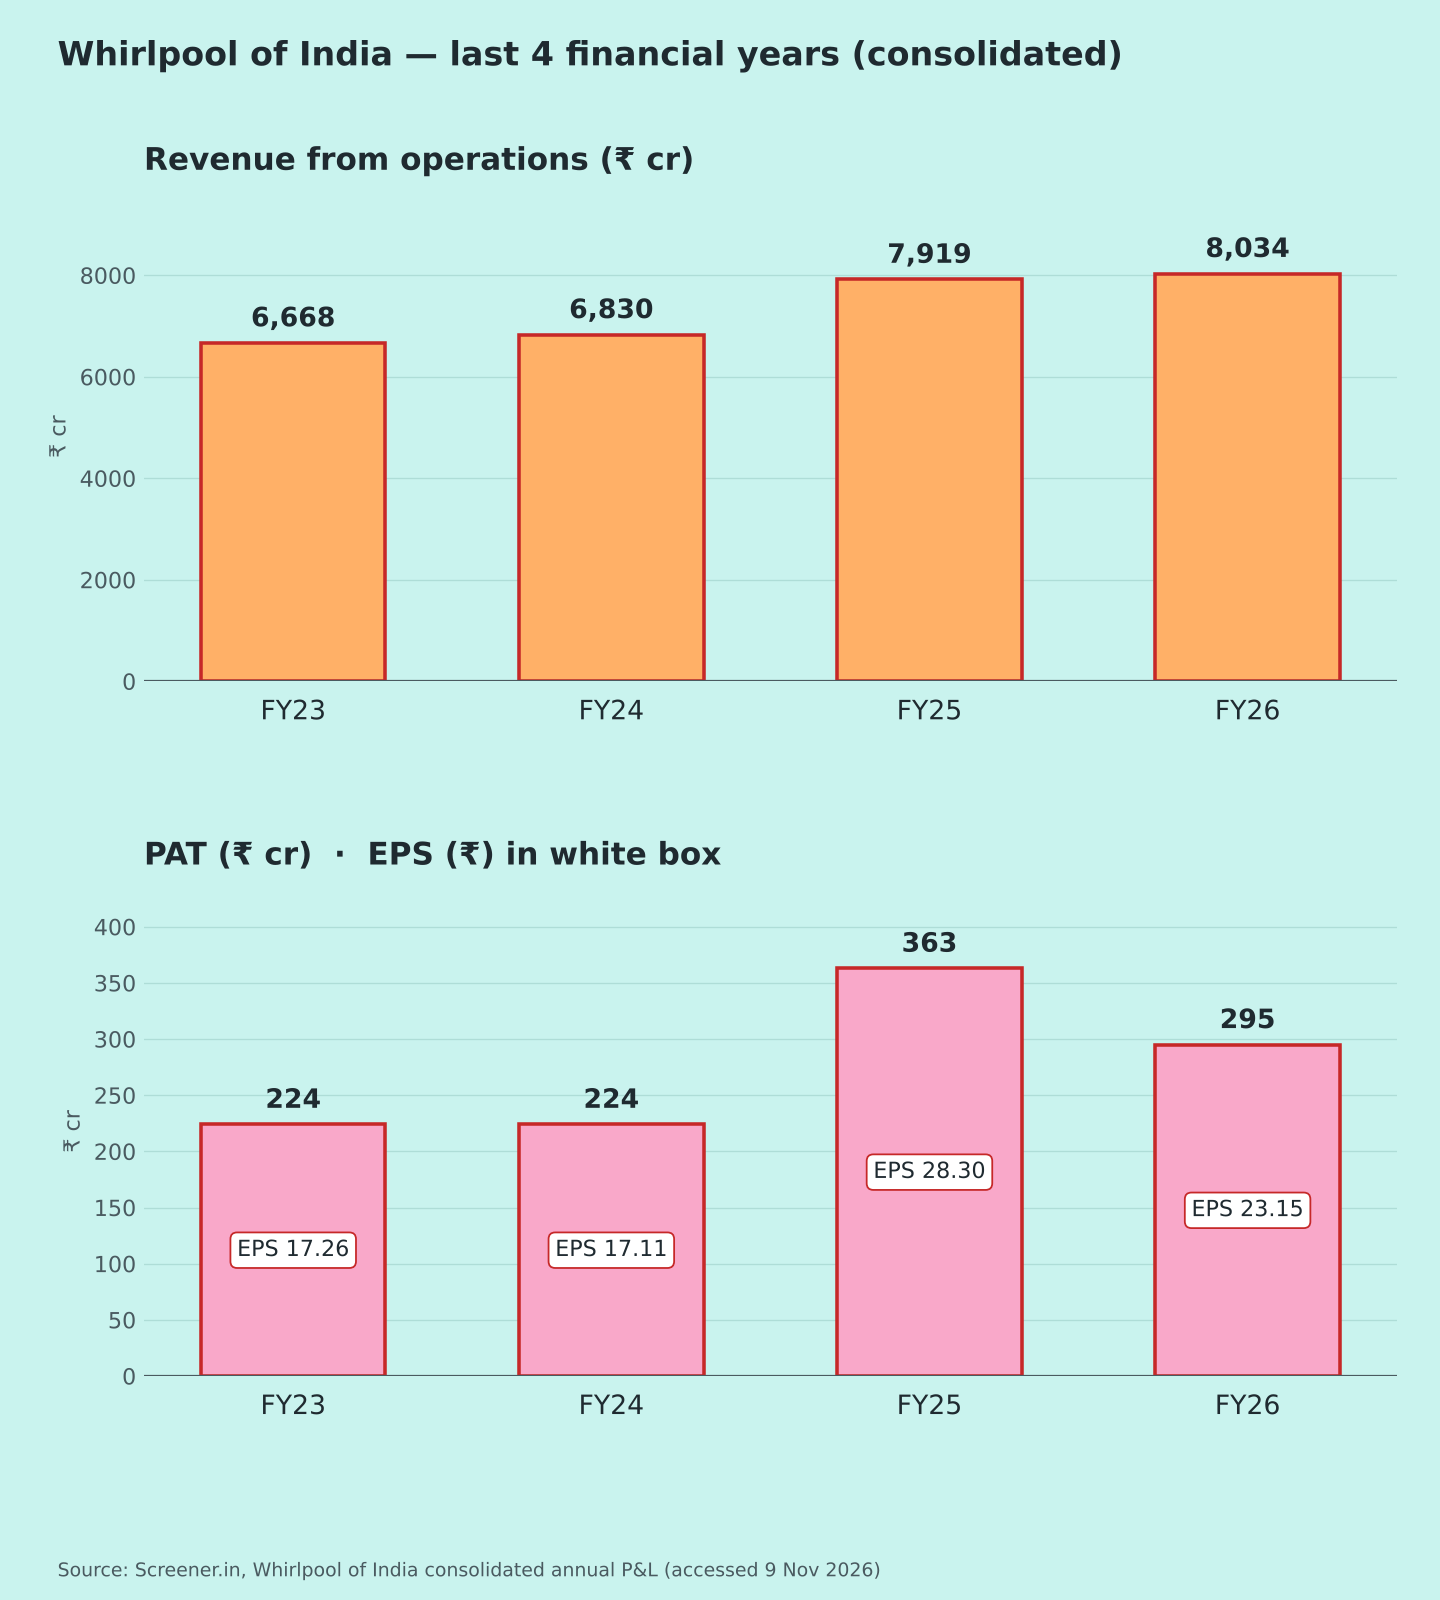
Consolidated figures, ₹ crore. Results announced 9 Nov 2026. EBITDA excludes other income. Reported EPS wasn't in coverage, so it is derived. Q1 FY27 figures are H1 minus Q2. Note: Q1 (Apr–Jun) is the summer peak for cooling products, so QoQ comparisons are seasonal.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 1,873.1 | +13.7% | −31.3% |
| EBITDA | ~40 | −31% | ≈−71% |
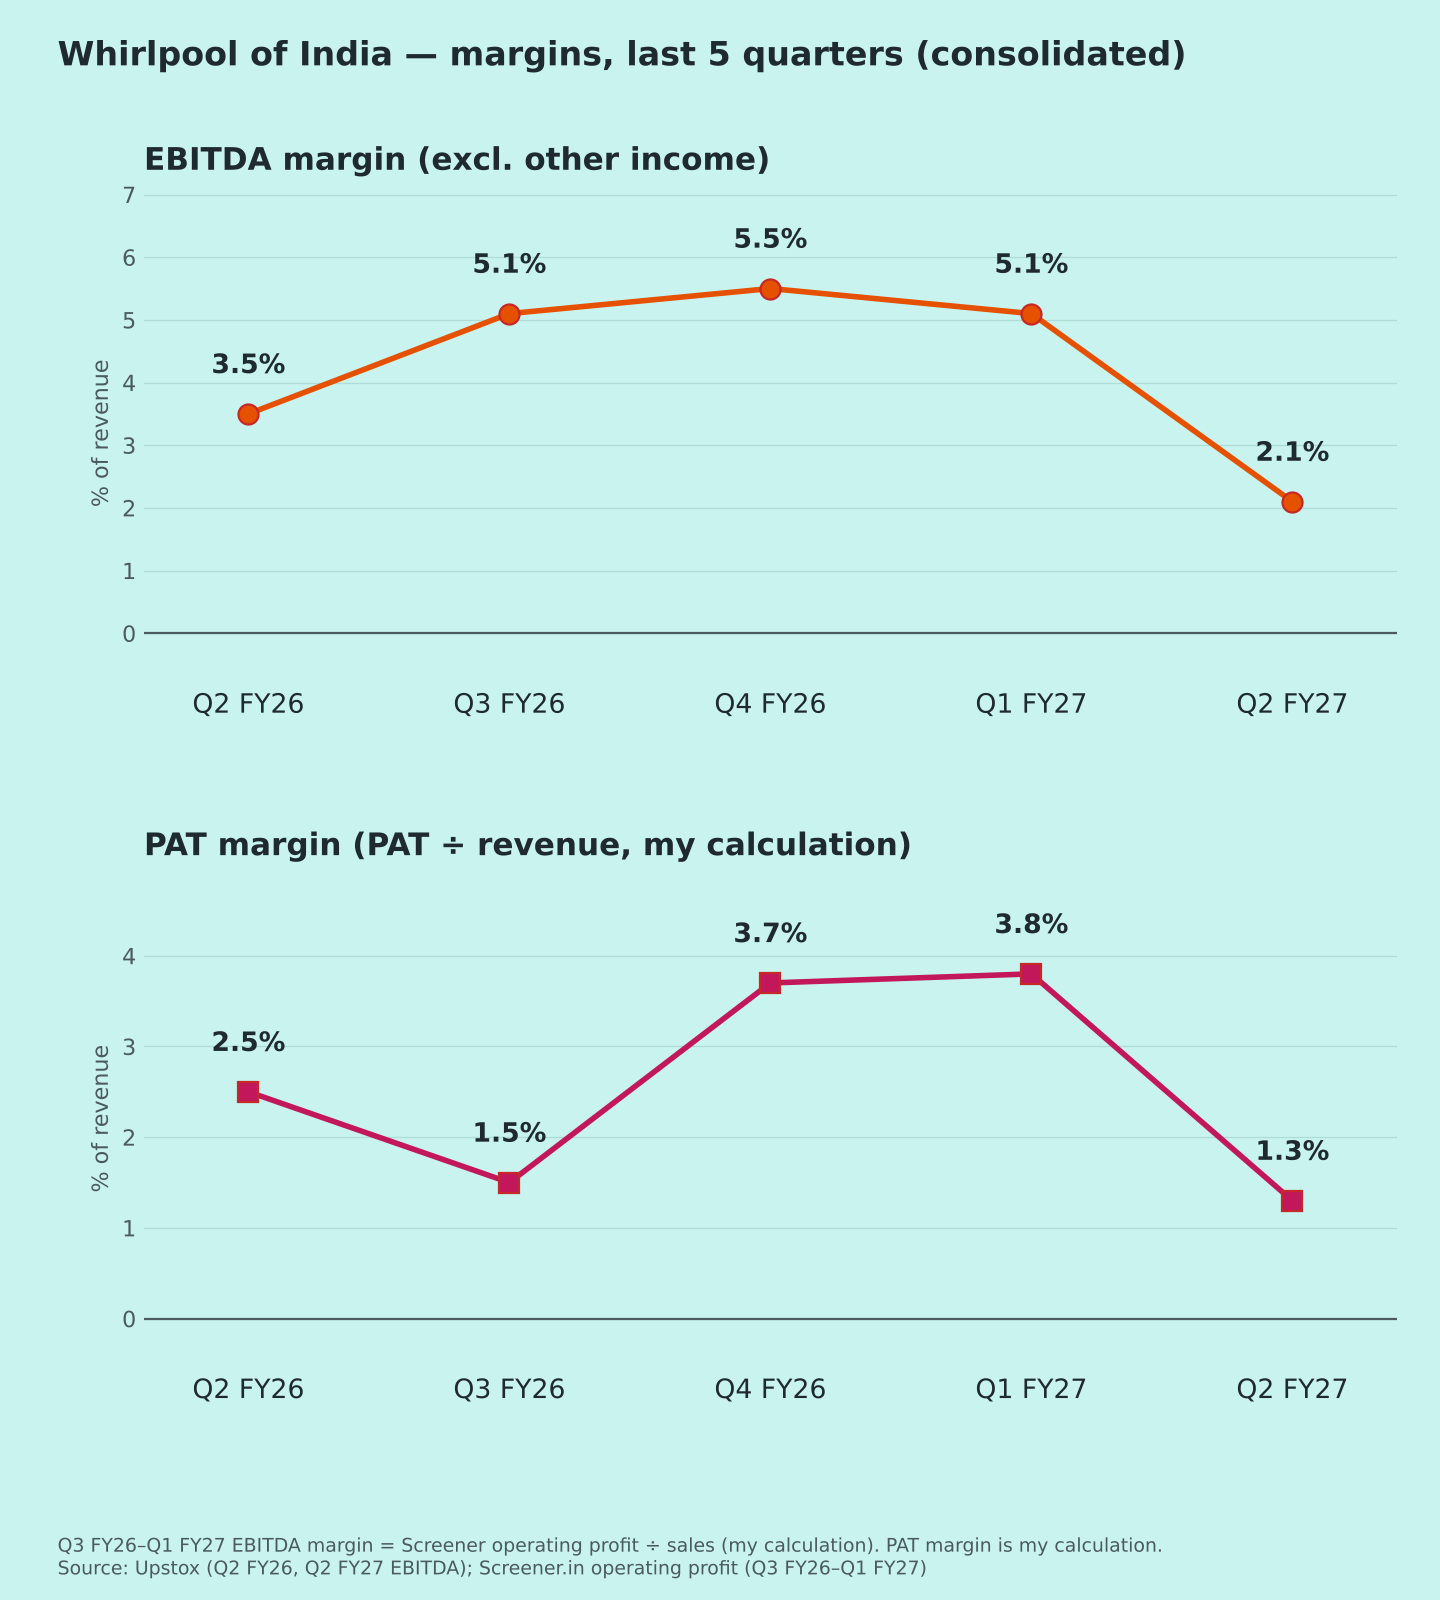
| EBITDA margin | 2.1% | 3.5% | 5.1% |
| Other income | 57.8 | ≈−4% | ≈−16% |
| PBT | 34.3 | ≈−41% | ≈−75% |
| PAT | 25.08 | −40.0% | ≈−75.6% |
| PAT margin | 1.3% | 2.5% | 3.8% |
| EPS (₹, ≈ derived) | ≈1.98 | 3.26 → ≈1.98 | 8.11 → ≈1.98 |
| Other income / PBT | ≈169% | ≈103% | ≈50% |
Margin and ratio rows show year-ago and last-quarter values. ≈ derived: EPS = PAT ÷ 12.69 cr shares; Q1 and year-ago EBITDA, other income and PBT from Screener [5]. % changes are my calculations except revenue, EBITDA and PAT YoY [2][3]. Sources: [1][2][3][5]
Source notes: Some reports say profit fell 39% [2][4]. That uses rounded crore figures; on exact figures (₹25.08 cr vs ₹41.80 cr) the fall is 40% [3]. One report calls ₹1,930.96 cr "H1 revenue" [3]; that is actually Q2 total income. H1 revenue is ₹4,599.87 cr [1].
Quality of earnings
- The core business lost money this quarter. Other income (₹57.8 cr) was larger than PBT (₹34.3 cr). Without it, pre-tax profit would be about −₹23.5 cr (my calculation). Other income also exceeded PBT a year ago.
- Costs rose faster than revenue. Revenue grew 14% on price increases, industry volumes and premium products, but expenses grew 15% [2].
- Reasons the company gave [2]:higher costs from new energy-efficiency rules for refrigerators and ACs
- spending on the "Luxuriem" launch
- commodity inflation, higher crude oil prices and a weaker rupee
- Subsidiary Elica India grew revenue 12% and PBT 22% [2].
Margins (Chart 3)
EBITDA margin: 3.5% → 5.1% → 5.5% → 5.1% → 2.1% [2][5]. It is the lowest in five quarters. Margins have been thin (≤5.5%) throughout.
Response and other news
- Whirlpool took another price increase of about 5% from 1 Nov 2026 [2], and says it is cutting costs through its "P4G" programme. No numeric guidance was given.
- Other updates [5]:
- The Head of Accounting and the Head of Taxation both resigned, effective 30 Oct 2026.
- Promoter holding is 39.76%, down from 51% in the Dec 2025 quarter.
- A new employee stock option scheme (ESOP 2026) has been set up.
Positives
- Revenue +13.7% with price increases sticking [2]
- Elica subsidiary growing [2]
Concerns
- Operating loss before other income (my calculation)
- Regulatory and commodity cost pressure [2]
- Senior finance resignations [5]
Things to track in Q3 FY27
- Whether the 5% price increase restores margins
- EBITDA margin vs 5%
- Other income dependence
- Management changes
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – results · [2] Upstox – Q2 FY27 results · [3] Free Press Journal – Q2 results · [4] The Hans India (IANS) · [5] Screener.in – consolidated
Charts: (1) 5 quarters revenue & PAT with EPS [1][5]; (2) FY23–FY26 [5]; (3) margins [2][5];