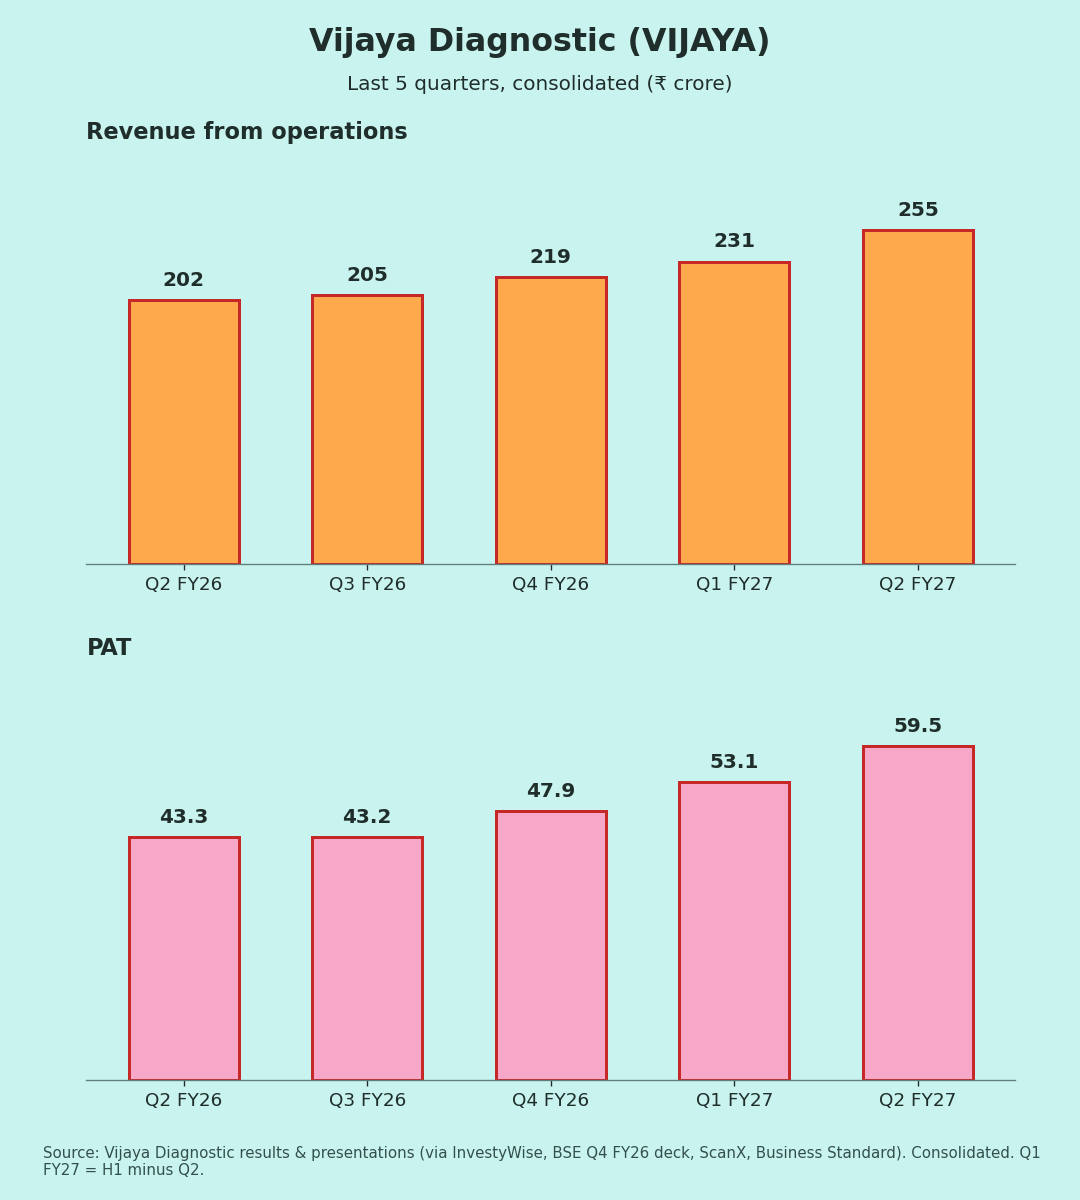
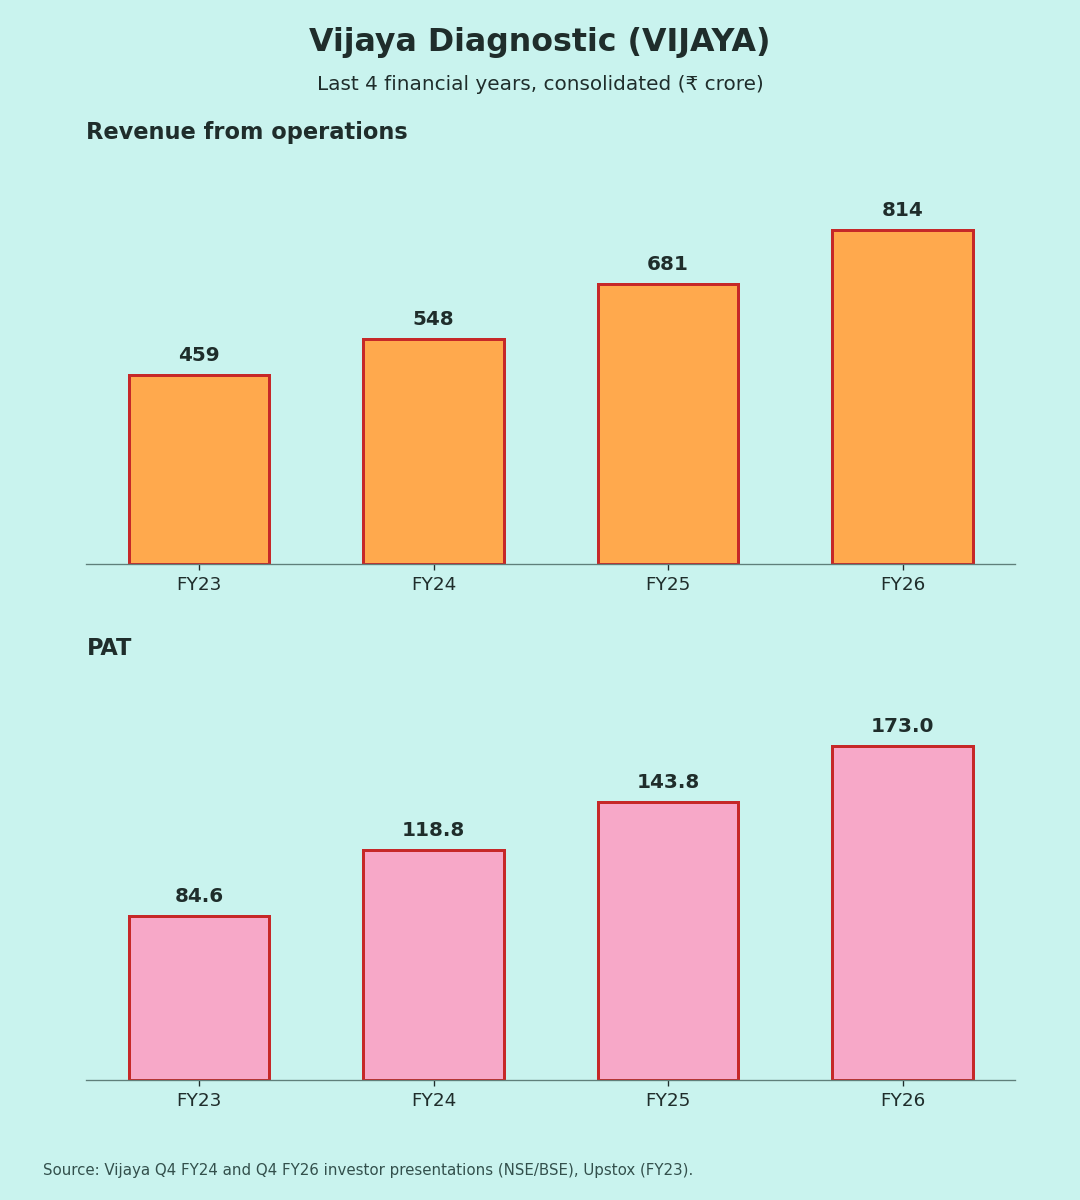
Consolidated figures, ₹ crore. Results were filed on 3 Nov 2026 .
EBITDA is as reported by the company. YoY/QoQ % and margins are my calculations. Q1 FY27 figures are H1 minus Q2.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 255.4 | +26.7% | +10.6% |
| EBITDA | 112.8 | +37.8% | +14.4% |
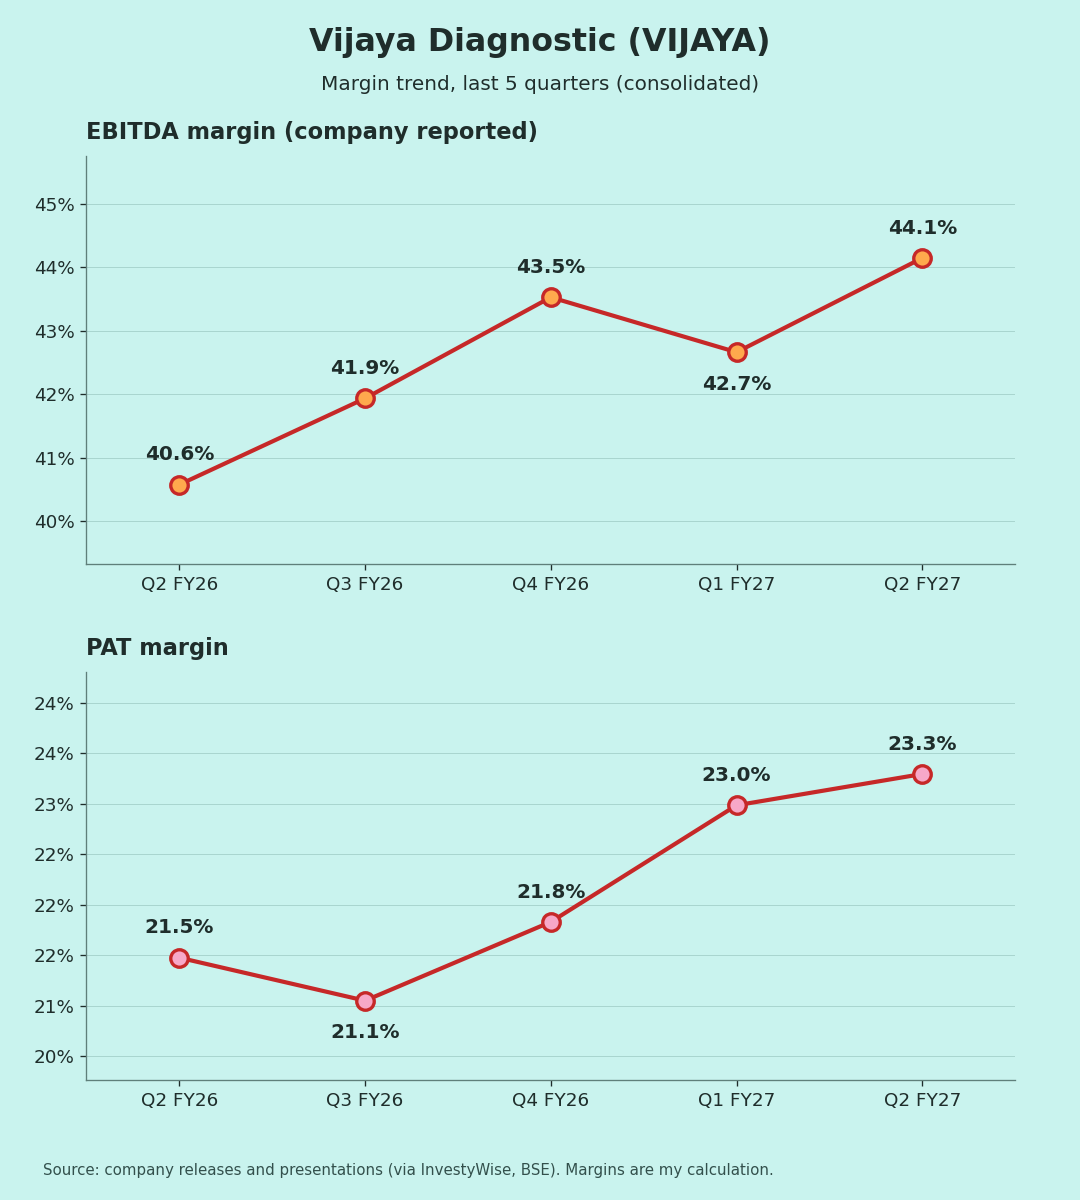
| EBITDA margin | 44.1% | 40.6% | 42.7% |
| PAT | 59.5 | +37.4% | +12.0% |
| PAT margin | 23.3% | 21.5% | 23.0% |
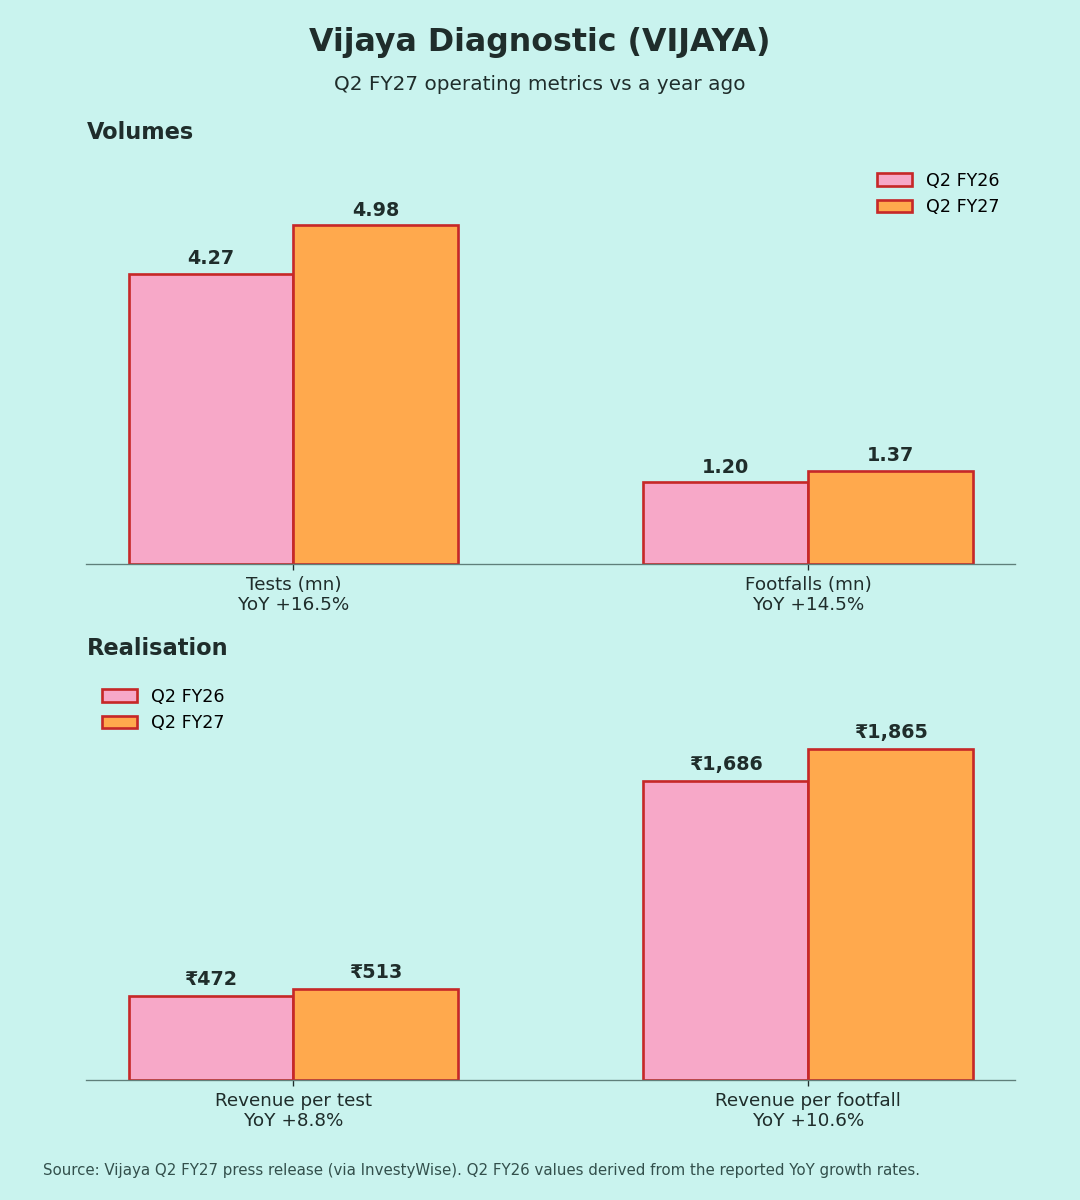
| Tests / footfalls | 4.98 mn / 1.37 mn | +16.5% / +14.5% | – |
| Revenue per test | ₹513 | +8.8% | – |
Margin rows show the year-ago and last-quarter values.
Quality of earnings
Both volume and price grew:
- Volume: tests rose 16.5% and footfalls 14.5% [1].
- Realisation: revenue per test rose 8.8% and revenue per footfall 10.6% [1].
- Existing centres grew about 20%, per the CEO [1], so this isn't only new-centre growth.
- Standalone revenue grew 27.4% [3], close to the consolidated growth. Coverage also credits the integrated Medinova business [3].
PAT grew in line with EBITDA (+37%). So the gain is operational, not from tax or one-offs (my reading). Other income and tax weren't in my sources.
Base effect: Q2 FY26 was a soft quarter. PAT then grew only 3.3% YoY and the EBITDA margin was 40.6%, as new hubs ramped up [6]. That flatters the YoY growth somewhat. QoQ PAT +12% is the cleaner read.
Margins (Chart 3)
EBITDA margin over five quarters: 40.6% → 41.9% → 43.5% → 42.7% → 44.1%. Q2 FY27 is the highest of the five. The CEO says the newer centres are ramping up well [1].
Guidance: what changed
- FY27 growth (Q1 call): "high double-digit" revenue growth, and ~15% over the medium term [5].
- Margin: the company's long-run guide is about 40% EBITDA [4].
- H1 actual: revenue up 24.8% and EBITDA margin at 43.4% [2]. Both are ahead of guidance.
- Network: 2 hubs and 7 spokes opened in H1. Another 3 hubs and 7 spokes are planned for H2 [1]. There are now 168 centres; 92% of revenue is B2C [2].
- Acquisition: an agreement to buy Arya Wellness Centre, the company's first entry into the North-East [1].
Positives
- Volume and realisation both growing [1]
- Margin at a five-quarter high [1]
- H1 ahead of guidance on growth and margin [2][5]
Concerns
- Ten new centres in H2 could dilute margins while they ramp up, as happened in FY26 [6]
- Revenue is concentrated in Hyderabad (~67%) [5]
- Integration of acquisitions (Medinova, Arya Wellness) (my view)
Things to track in Q3 FY27
- Whether the EBITDA margin holds above 42% as new hubs open
- Organic growth at existing centres (~20% in Q2)
- Growth in tests vs revenue per test
- Arya Wellness closing and contribution
Not a buy/sell recommendation.Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – Q2 FY27 results & commentary · [2] InvestyWise – Q2 FY27 presentation · [3] Whalesbook – filing summary · [4] BSE – Q4 FY26 presentation · [5] FundsIndia – Q1 FY27 note · [6] ScanX – Q2 FY26 · [7] NSE – Q4 FY24 presentation · [8] Upstox – FY23
Charts:
(1) last 5 quarters revenue & PAT
(2) FY23–FY26 revenue & PAT
(3) EBITDA and PAT margin (own calc.);
(4) volumes and realisation [1], Q2 FY26 values derived from the reported growth.