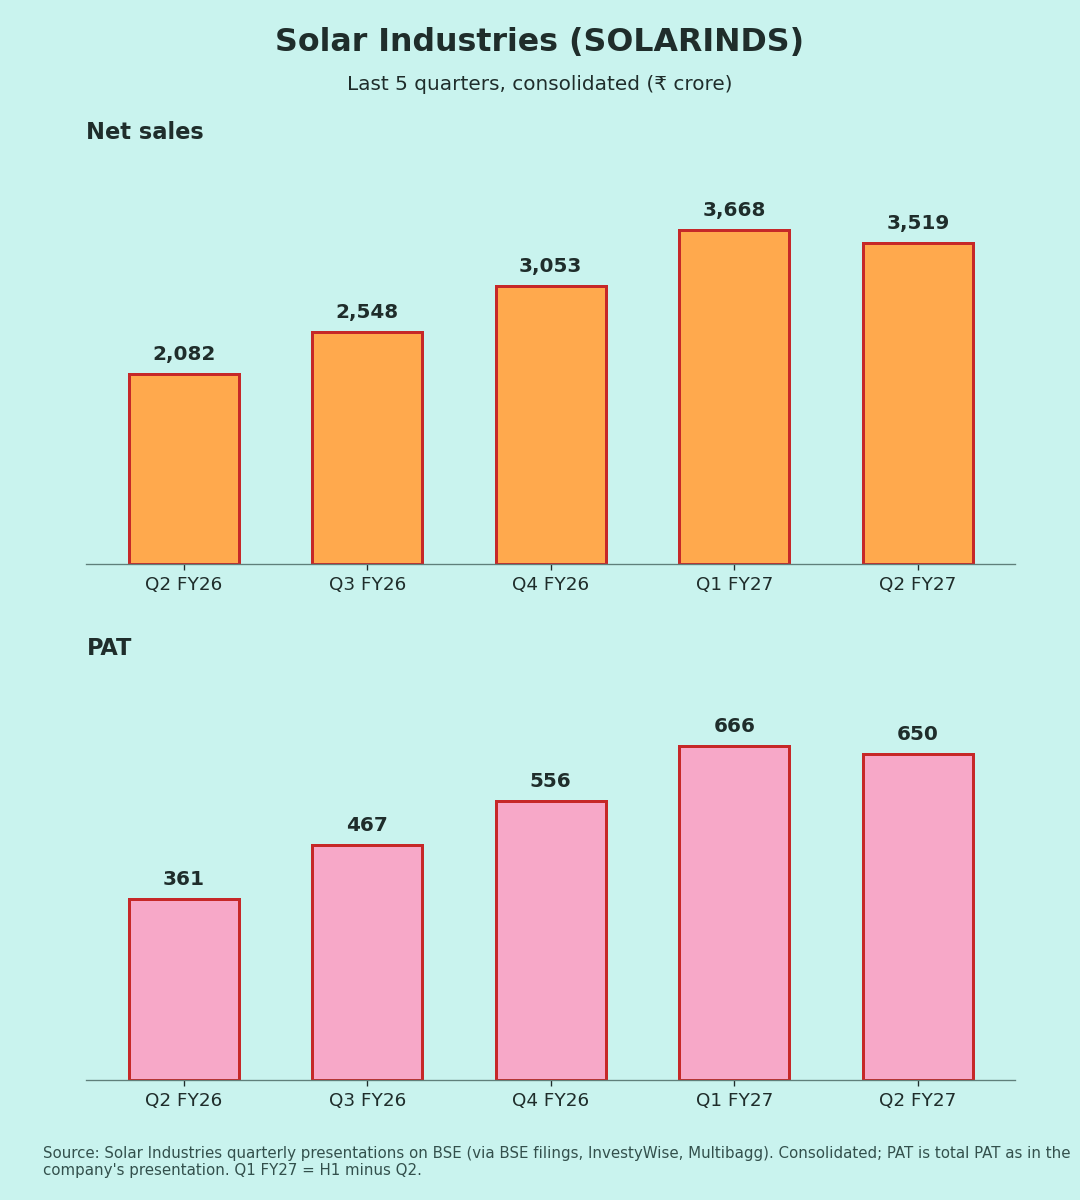
Consolidated figures, ₹ crore, as presented in the company's results deck. Results were declared on 3 Nov 2026 . YoY/QoQ % and margins are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Net sales | 3,519 | +69.0% | −4.1% |
| EBITDA | 1,021 | +75.4% | −0.3% |
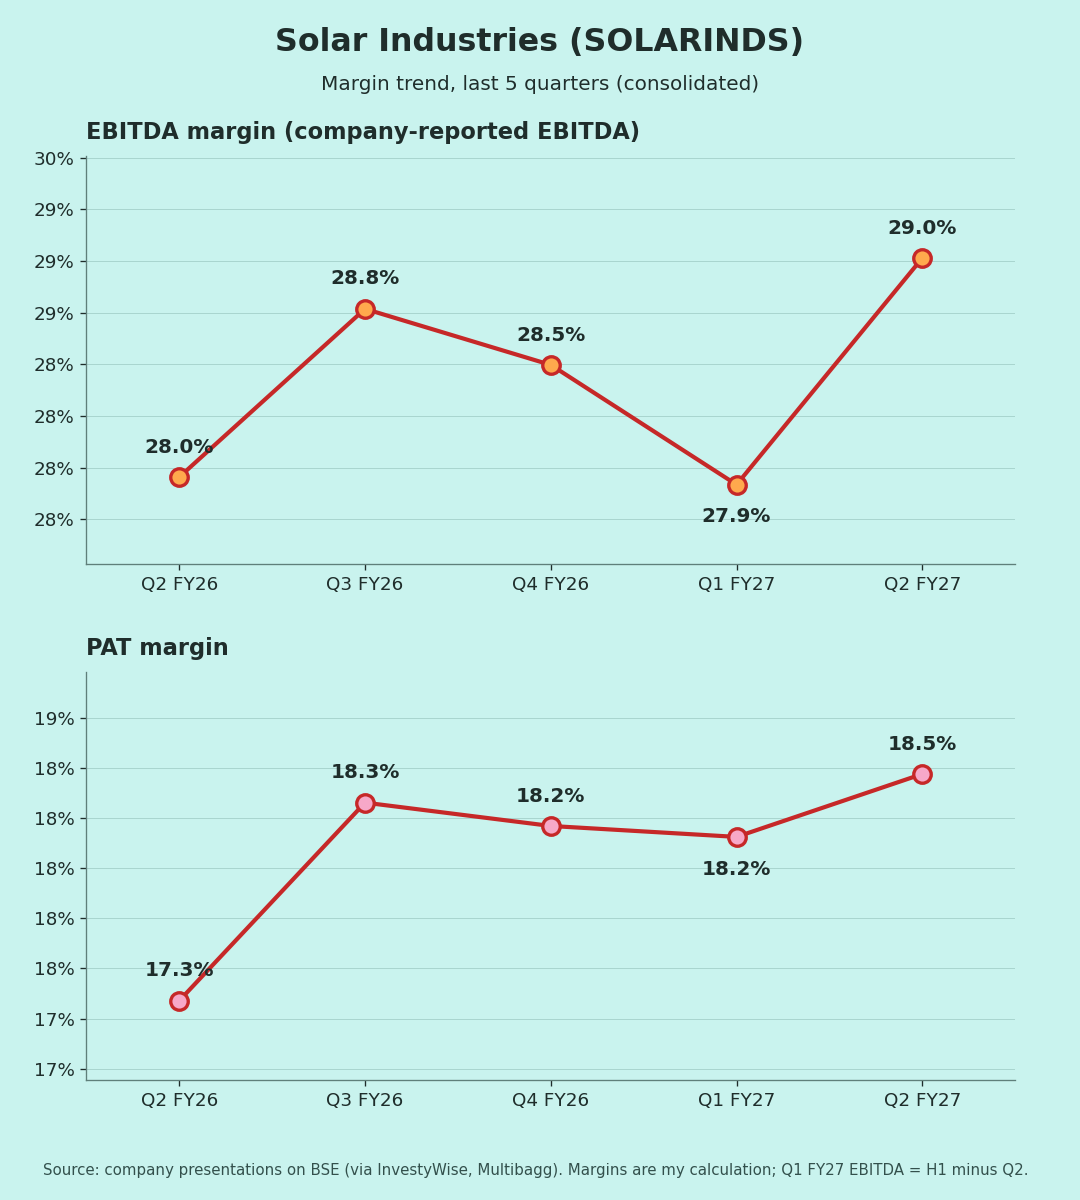
| EBITDA margin | 29.0% | 28.0% | 27.9% |
| PBT | 877 | +79.2% | −3.8% |
| PAT | 650 | +80.1% | −2.4% |
| PAT margin | 18.5% | 17.3% | 18.2% |
| Other income / PBT | ~1.7% | ~5.9% | – |
Margin and ratio rows show the year-ago and last-quarter values.
Quality of earnings
Growth is operational:
- Other income is tiny: the company's EBITDA (₹1,021 cr) is only about ₹15 cr above EBITDA excluding other income (₹1,006 cr) [1][2] (my calculation).
- The tax rate is a normal ~26%.
- No exceptional items appear in the coverage.
Base effect: Q2 FY26 was a normal quarter, with PAT up 21% YoY at the time [4]. So the 69% sales growth is not flattered by a weak base.
QoQ, sales and profit dipped slightly from a record Q1. My understanding is Q2 is usually softer for mining explosives because of the monsoon.
Margins (Chart 3)
EBITDA margin over five quarters: 28.0% → 28.8% → 28.5% → 27.9% → 29.0%. Q2 is the highest of the five. The likely reason is mix: defence and international explosives together are now 72% of sales.
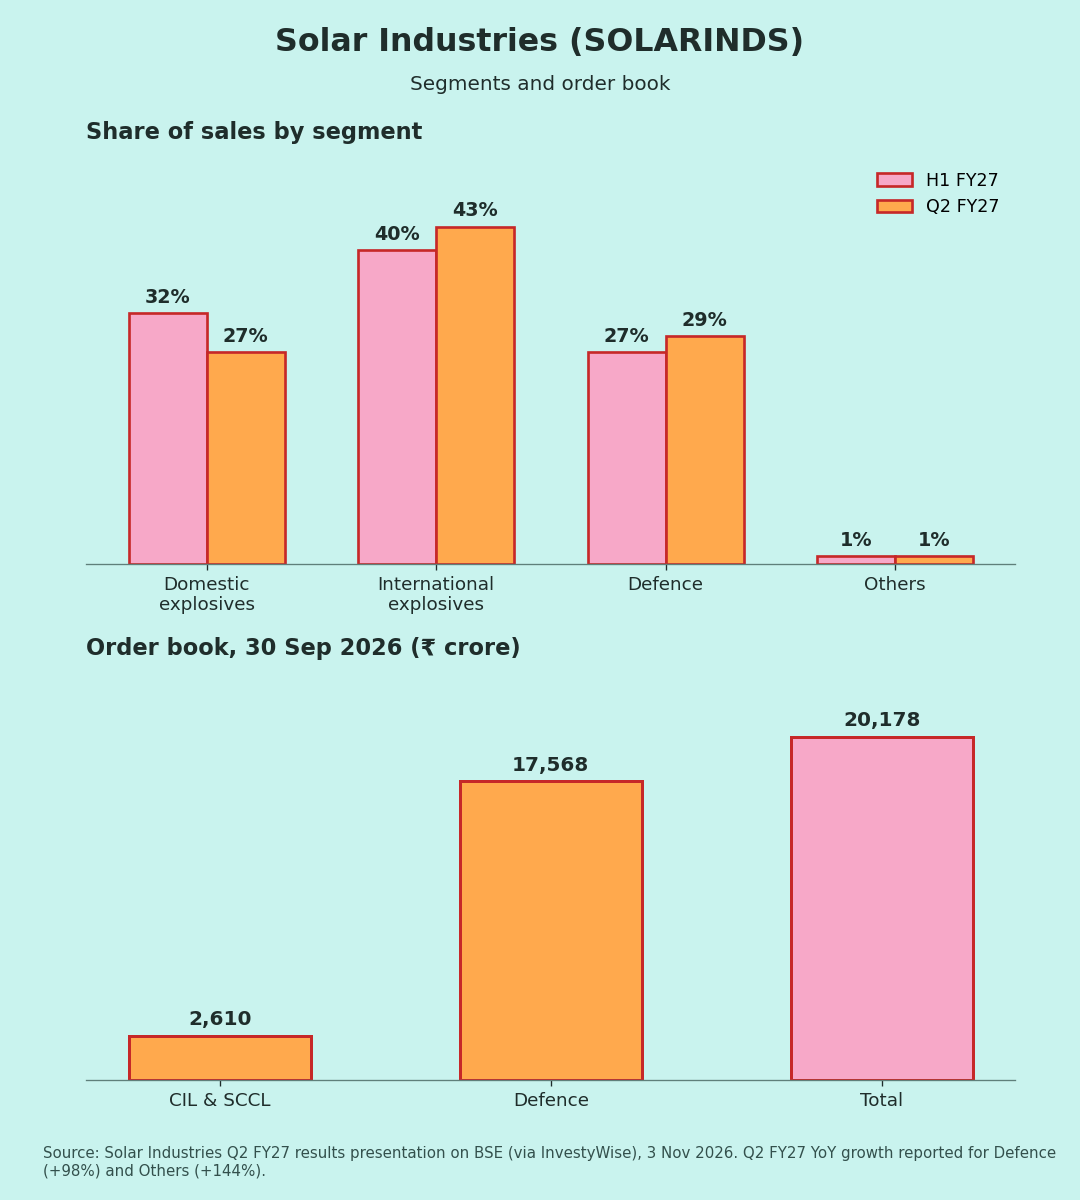
Segments [1]
| Segment | Share of Q2 sales | YoY |
| Domestic explosives | 27% | grew (rate not given) |
| International explosives | 43% | grew (rate not given) |
| Defence | 29% | +98% |
| Others | 1% | +144% |
The deck says all segments grew YoY.
Guidance: what changed
- FY27 targets (from May): revenue ₹14,000 cr, defence ₹4,500 cr, domestic explosives growth ~35% [7][8].
- Now: management expects to surpass its FY27 guidance [2]. H1 sales of ₹7,187 cr are already 51% of the ₹14,000 cr target (my calculation).
- Defence: H1 defence sales are about ₹1,940 cr (27% of H1 sales, my calculation), so H2 needs ~₹2,560 cr to reach ₹4,500 cr. Management expects large domestic and export orders soon, including guided Pinaka rockets [2].
- Order book: ₹20,178 cr on 30 Sep, of which defence is ₹17,568 cr [1]. In August it was "over ₹21,350 cr" [9], so it is slightly lower as execution runs ahead of new orders (my reading).
Balance sheet: Net debt ₹1,177 cr, net debt/EBITDA 0.29x; H1 capex ₹873 cr; working-capital days 108 [1].
Positives
- Sales +69%, PAT +80% YoY [1]
- EBITDA margin at a five-quarter high [1]
- Low leverage despite heavy capex [1]
Concerns
- Order book down from August levels [1][9]
- Earnings increasingly depend on defence and exports, which can be lumpy (my view)
- Working capital at 108 days ties up cash [1]
- Raw-material costs (ammonium nitrate) are a known pressure point [8]
Things to track in Q3 FY27
- New defence order wins and the order-book trend
- Defence revenue run-rate vs the ₹4,500 cr target
- EBITDA margin holding near 29%
- Domestic explosives growth vs the ~35% outlook
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – Q2 FY27 results presentation (BSE) · [2] Upstox – Q2 FY27 results, 3 Nov 2026 · [3] Multibagg – Q1 FY27 figures · [4] Business Standard – Q2 FY26 · [5] BSE – Q3 FY26 presentation · [6] BSE – Q4 FY26 presentation · [7] ICICI Direct – Q4 FY26 note · [8] Whalesbook – FY27 outlook, May 2026 · [9] Sahi – Q1 FY27 & guidance · [10] BSE – FY24 results release · [11] Business Standard – FY25 results
Charts:
(1) last 5 quarters sales & PAT
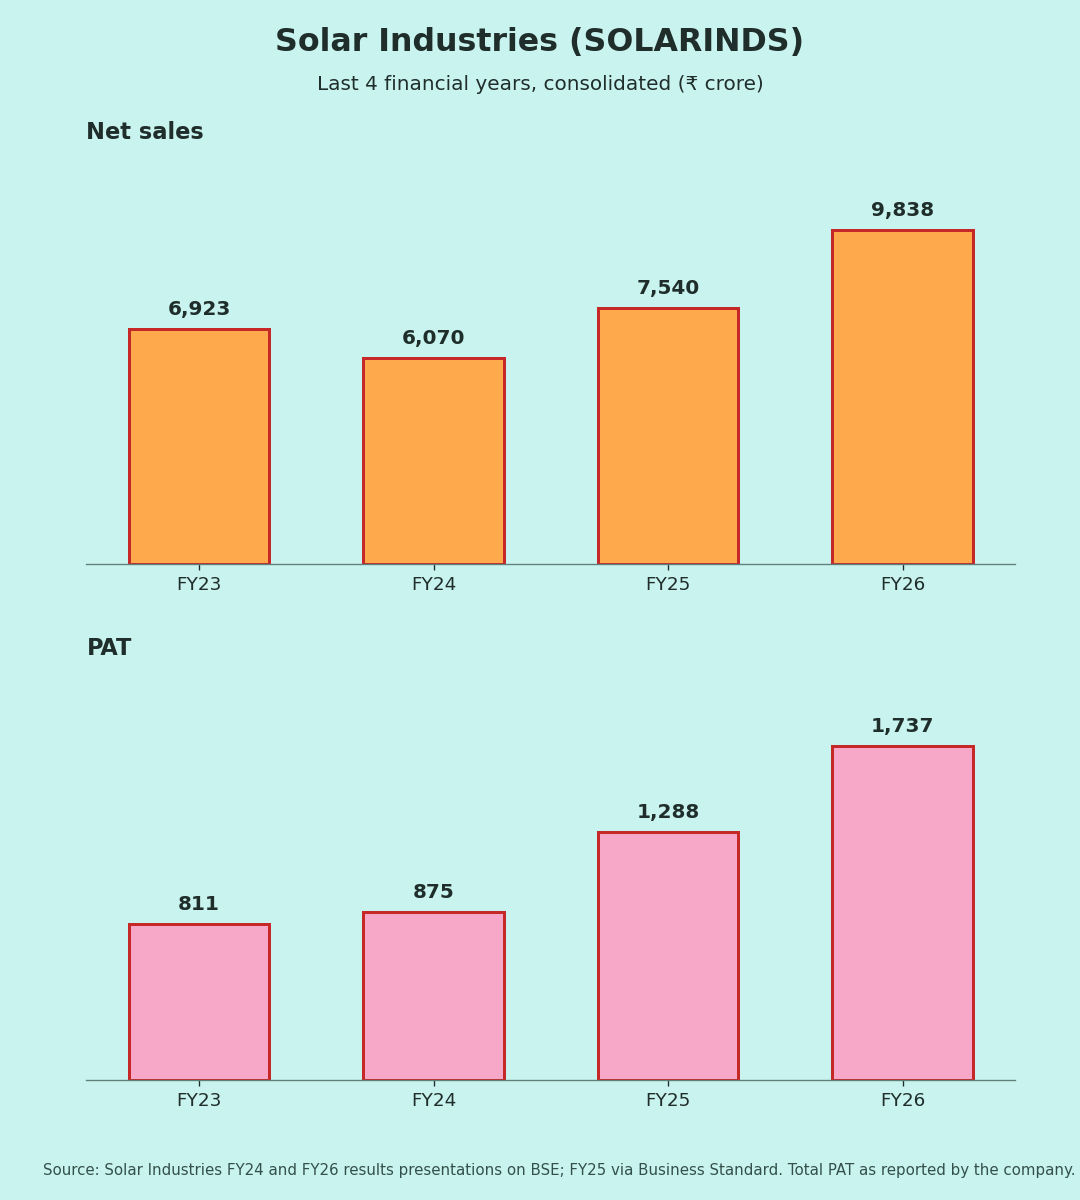
(2) FY23–FY26 sales & PAT
(3) EBITDA and PAT margin (own calc.)
(4) segment mix and order book.