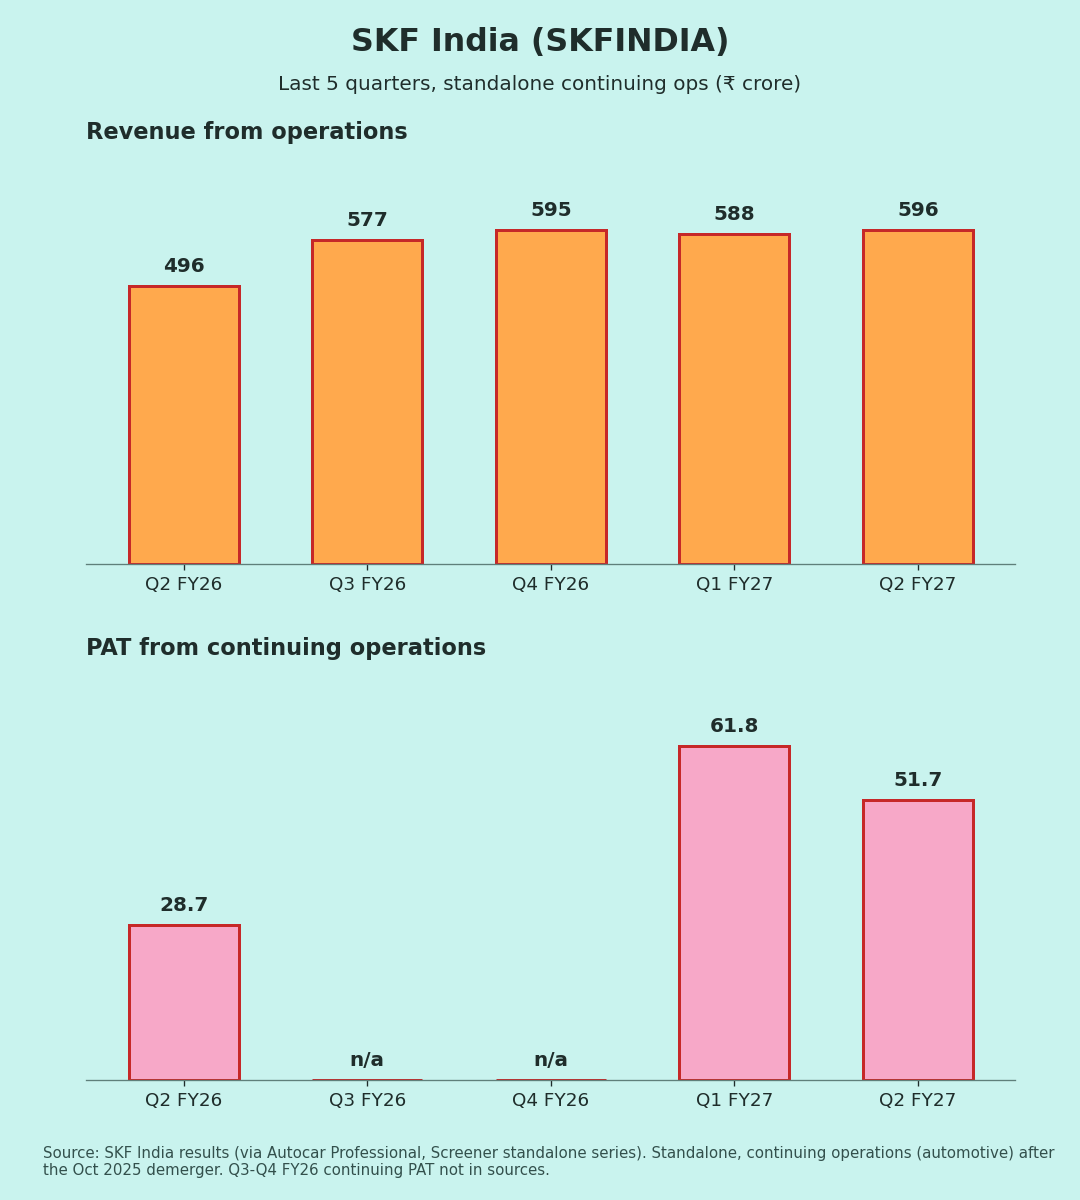
Standalone figures for continuing operations, ₹ crore.
The industrial business was demerged into SKF India (Industrial) Ltd effective 1 Oct 2025, so SKF India is now the automotive bearings business. Year-ago figures are re-presented on the same basis [1]. Results were filed on 3 Nov 2026. YoY/QoQ % and margins are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 595.8 | +20.1% | +1.4% |
| Total expenses | 555.1 | +22.5% | +7.5% |
| Operating profit before other income* | 40.7 | −4.5% | −43.0% |
| Operating margin before other income* | 6.8% | 8.6% | 12.2% |
| PAT (continuing ops) | 51.7 | +80.0% | −16.4% |
| PAT margin | 8.7% | 5.8% | 10.5% |
| EBITDA (company basis) | not in sources | – | – |
*Revenue minus total expenses, which include depreciation and interest. Company-reported EBITDA for Q2 wasn't in the coverage at writing. Margin rows show the year-ago and last-quarter values.
Quality of earnings
The headline (+80% PAT) and the operating trend point in opposite directions:
- Revenue: up 20% YoY, driven by domestic demand [1].
- Costs: expenses grew faster, +22.5% YoY [1]. Purchases of traded goods (₹130 cr) were about 22% of revenue.
- Operating profit: revenue minus expenses fell 4.5% YoY and 43% QoQ (my calculation).
- PAT is above that operating profit. So other income (likely treasury income on cash) must have supported the quarter. The filing's other-income line wasn't in my sources (interpretation).
- No exceptional items are mentioned for Q2.
Base effect: the year-ago quarter had only ₹28.7 cr of continuing PAT. Total Q2 FY26 PAT of ₹105.7 cr included ₹76.9 cr from the demerged industrial business [1]. YoY comparisons rest on re-presented numbers, so QoQ is the fairer read here.
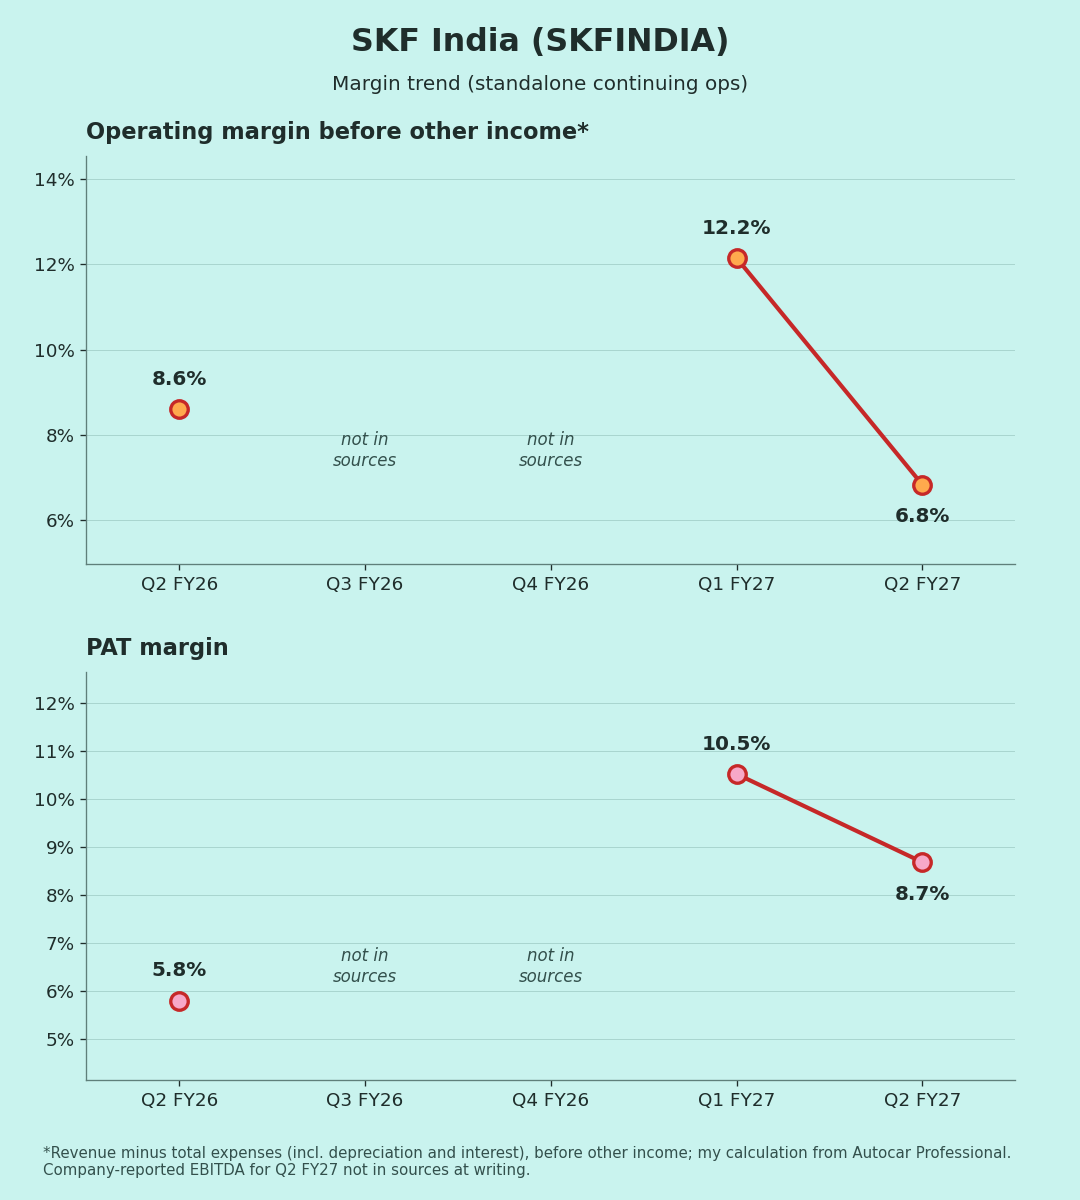
Margins (Chart 3)
On a comparable basis, operating margin before other income was 8.6% a year ago, 12.2% in Q1 and 6.8% in Q2 (my calculation). Management cited higher material and operating costs for the QoQ drop [1]. For reference, the company's EBITDA margin was 11.7% in Q4 FY26 and 17.1% in Q1 FY27 [3].
Guidance: what changed
- FY27 growth (August call): raised to ~20% revenue growth, from 12% earlier, with margins around 17% expected to hold for two years [3].
- H1 actual: revenue up about 24% (my calculation from [1][2]), ahead of the growth guide.
- Margin: Q2's cost jump puts the ~17% margin guide in question (my view). The Q2 company EBITDA figure is needed to check.
- Capex: ₹140.4 cr approved [1]:
- Haridwar: two ball-bearing lines, production from Dec 2026–Mar 2027
- Pune: two tapered-roller lines, production from Mar–Jul 2027
- Aim: cut reliance on imported traded goods
- Brand: the business now trades as "SKF Vertevo" from 3 Nov 2026 [4].
Positives
- Revenue +20% YoY [1]
- Capex to localise imported products [1]
- Almost debt-free [2]
Concerns
- Operating profit fell 43% QoQ [1]
- Profit leans on other income (interpretation)
- High share of traded (imported) goods [1]
- Earlier quarters on the new basis are only partly disclosed
Things to track in Q3 FY27
- Company-reported EBITDA margin vs the ~17% guide
- Material and traded-goods costs as a share of revenue
- Other income's share of PBT
- Haridwar line start-up from Dec 2026
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Autocar Professional – Q2 FY27 filing, 3 Nov 2026 · [2] Screener.in – standalone · [3] Quartr – Q1 FY27 summary & guidance · [4] Whalesbook – Q2 FY27, Vertevo brand · [5] Sahi – demerger effect on reported revenue
Charts:
(1) last 5 quarters revenue & continuing PAT [1][2], with Q3–Q4 FY26 continuing PAT not in sources;
(2) operating and PAT margin (own calc.). There is no 4-year chart: before FY26 the reported numbers include the demerged industrial business, so no comparable history exists.