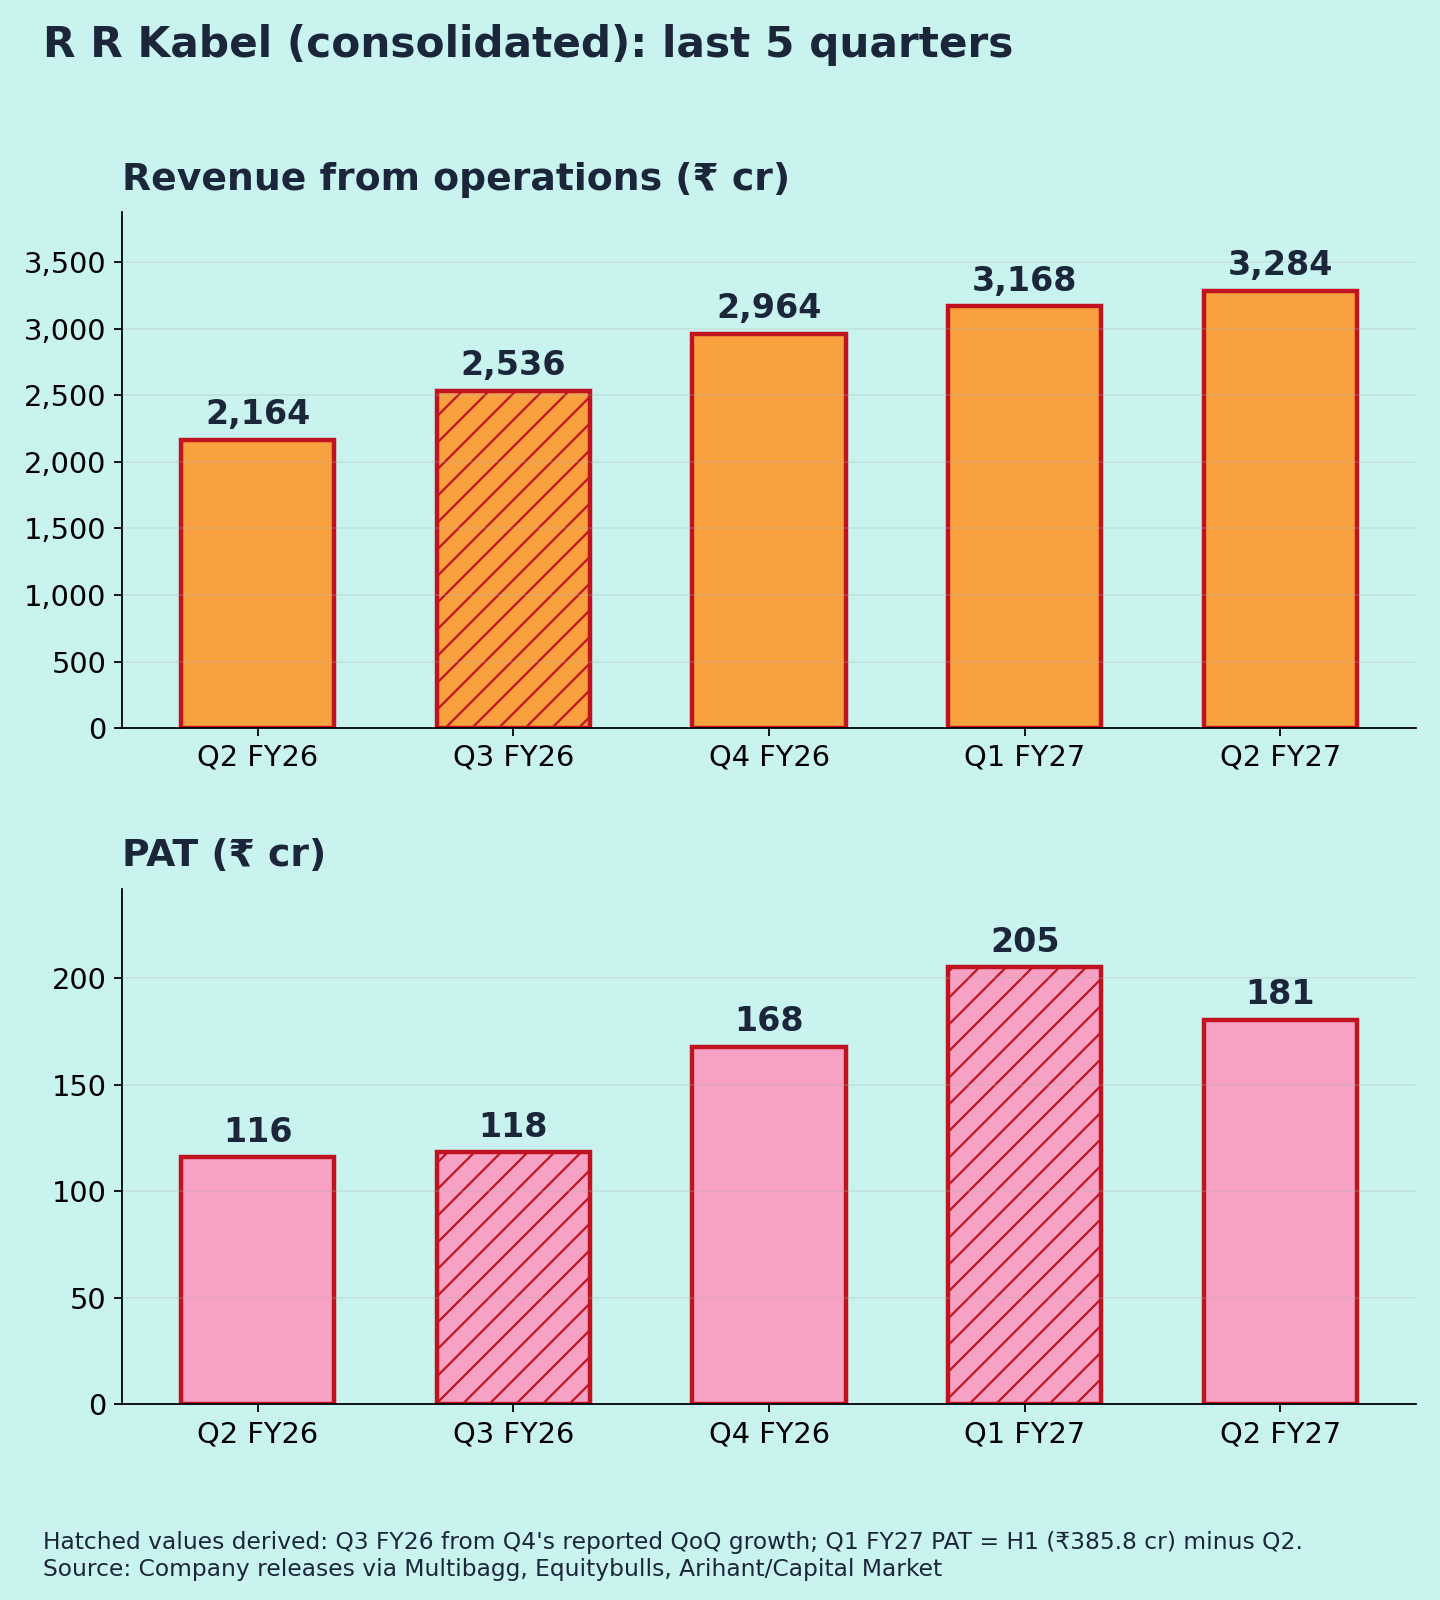
All figures consolidated, ₹ crore unless stated. Results released after market close on 28 Oct 2026. YoY/QoQ % and margins are my calculations from reported numbers.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 3,284 | +51.8% | +3.7% |
| EBITDA | 283 | +60.8% | −1.9% |
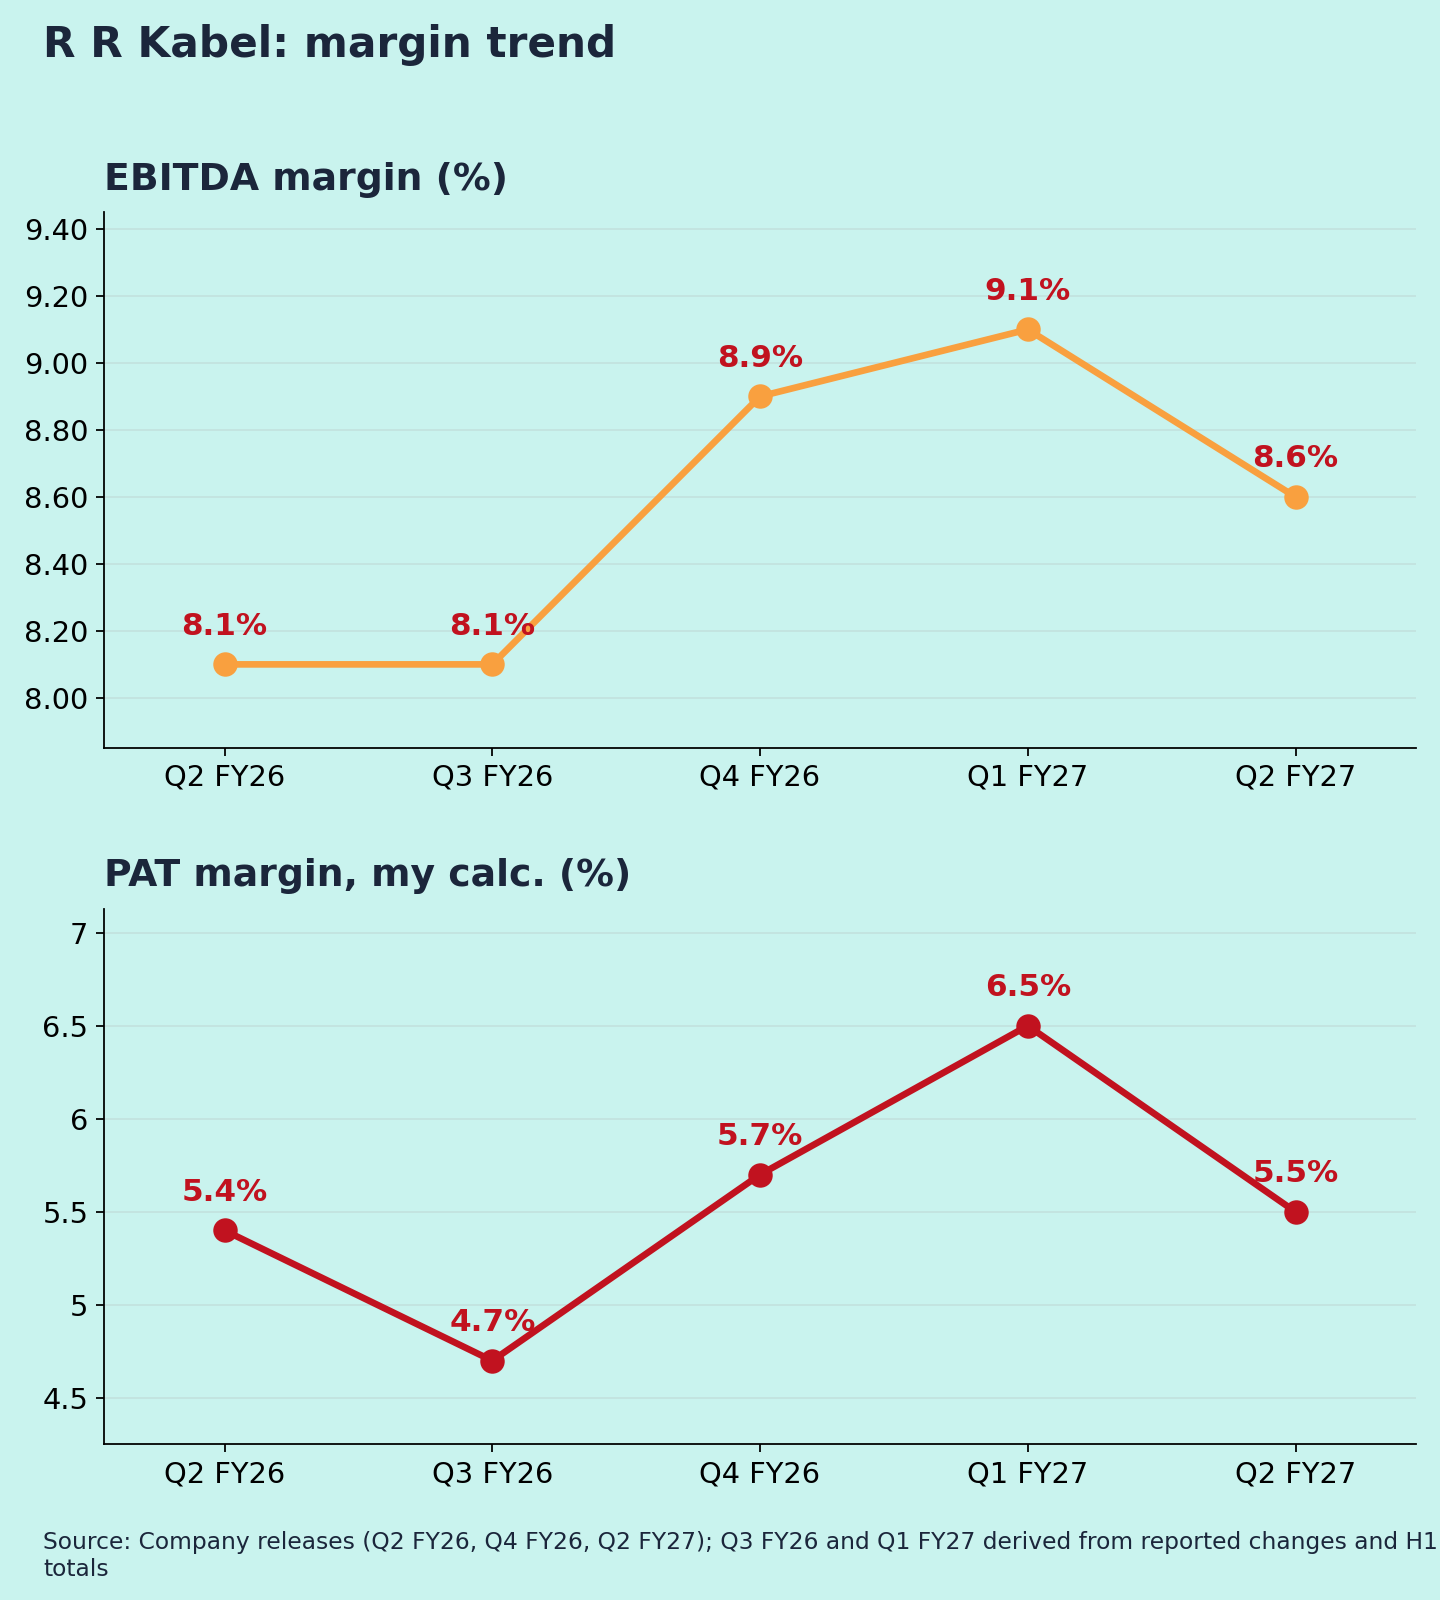
| EBITDA margin | 8.6% | 8.1% | 9.1% |
| PAT | 180.6 | +55.7% | −12.0% |
| PAT margin | 5.5% | 5.4% | 6.5% |
| Other income / PBT | n.a.* | – | – |
For margin rows, the YoY and QoQ columns show the prior-period value. Q1 FY27 EBITDA and PAT are derived as H1 minus Q2. *Quarterly PBT wasn't in the coverage.
Quality of earnings
Growth is operational and led by wires and cables (W&C):
- W&C: H1 revenue +55%, with segment profit +78% and margins up 124 bps [1].
- What drove it: both higher volumes and higher realisations. Copper-linked price pass-through inflates revenue growth (my reading).
- FMEG (fans, lights, switches, appliances): the loss margin narrowed to 2.2% from 4.5% [1].
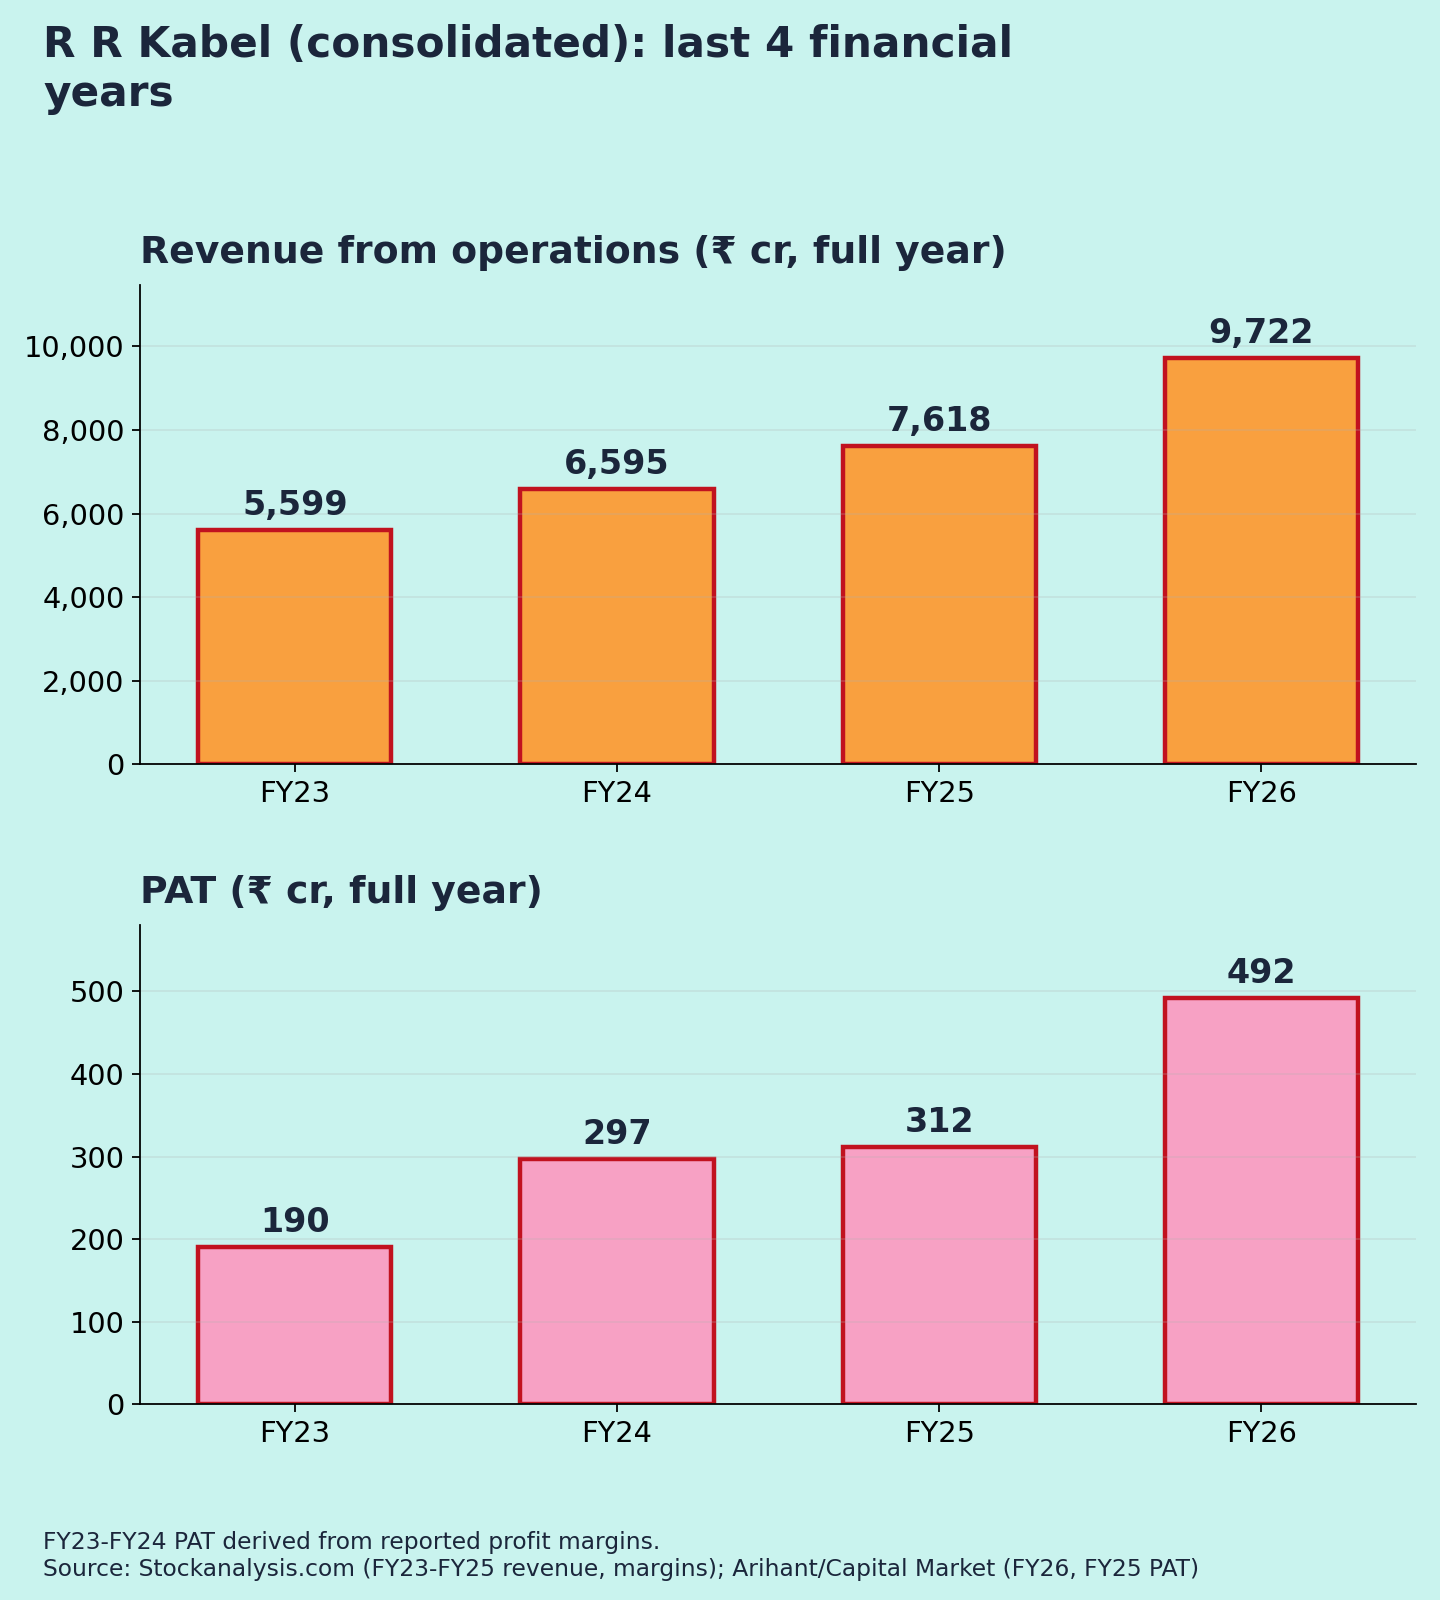
The weak spot is cash. H1 operating cash flow was only ₹121 cr on 53% revenue growth [4]. FY26 cash from operations had already fallen to ₹448 cr from ₹591 cr [6]. So working capital is absorbing much of the growth (my view).
QoQ is softer. Revenue grew only 3.7%, EBITDA margin dipped 50 bps, and PAT fell 12% from a record Q1 (my calculation).
Base effect: Q2 FY26 was a normal quarter (8.1% margin) [1], so YoY growth isn't flattered by a weak base.
Margins (Chart 3)
EBITDA margin over five quarters: 8.1% → ~8.1% → 8.9% → ~9.1% → 8.6%. It is higher than a year ago but slipped from Q1's peak.
Our Power & Grid sector note flagged cable margins under pressure from new entrants and copper volatility. RR Kabel's YoY margin has held up so far.
Guidance: what changed
- At Q4 FY26 (per PL Capital): FY27 volume growth of ~16–18%, W&C EBIT margin up ~300 bps to ~9.5% in FY27 and ~10.5% by FY28, and FMEG value growth of 20–25% [7].
- Now: management reiterated FMEG operating break-even for FY27.
- Capex and deals:₹1,200 cr capex programme over FY26–28
- Roorkee capacity expansion [1]
- ₹200 cr of land in Rajasthan [5]
- ₹77 cr acquisition of U M Cables' optical-cable business [5]
- Dividend: interim ₹6.50 per share [1].
- Risks flagged: Middle East was ~40% of FY26 exports [7], and EPR (extended producer responsibility) rules remain uncertain [5].
Positives
- Record half-year revenue, EBITDA and PAT
- W&C margins expanding; FMEG losses narrowing
- Capacity and acquisitions support growth
Concerns
- Weak cash conversion: ₹121 cr operating cash flow in H1 [4]
- QoQ profit and margin dip [1]
- Export exposure to the Middle East [7]
- Rising competition in cables (sector view) [10]
Things to track in Q3 FY27
- Operating cash flow and receivables
- EBITDA margin vs the W&C margin targets
- FMEG reaching break-even
- Export trends amid the West Asia disruption
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Multibagg – Q2 FY27 · [2] Equitybulls – Q2 FY27 · [3] Investywise – H1 FY27 · [4] ScanX – Q2 FY27 · [5] Whalesbook – dividend, acquisition · [6] Arihant/Capital Market – Q4 FY26 · [7] PL Capital – Q4 FY26 update · [8] Investywise – Q4 FY26 · [9] Stockanalysis – annual · [10] Power & Grid sector deep dive (26 Oct 2026)
Charts: (1) last 5 quarters revenue & PAT [1][6] (Q3 FY26 and Q1 FY27 partly derived); (2) FY23–FY26 revenue & PAT [6][9] (FY23–FY24 PAT derived from reported margins); (3) EBITDA and PAT margin [1][6] (own calc.).