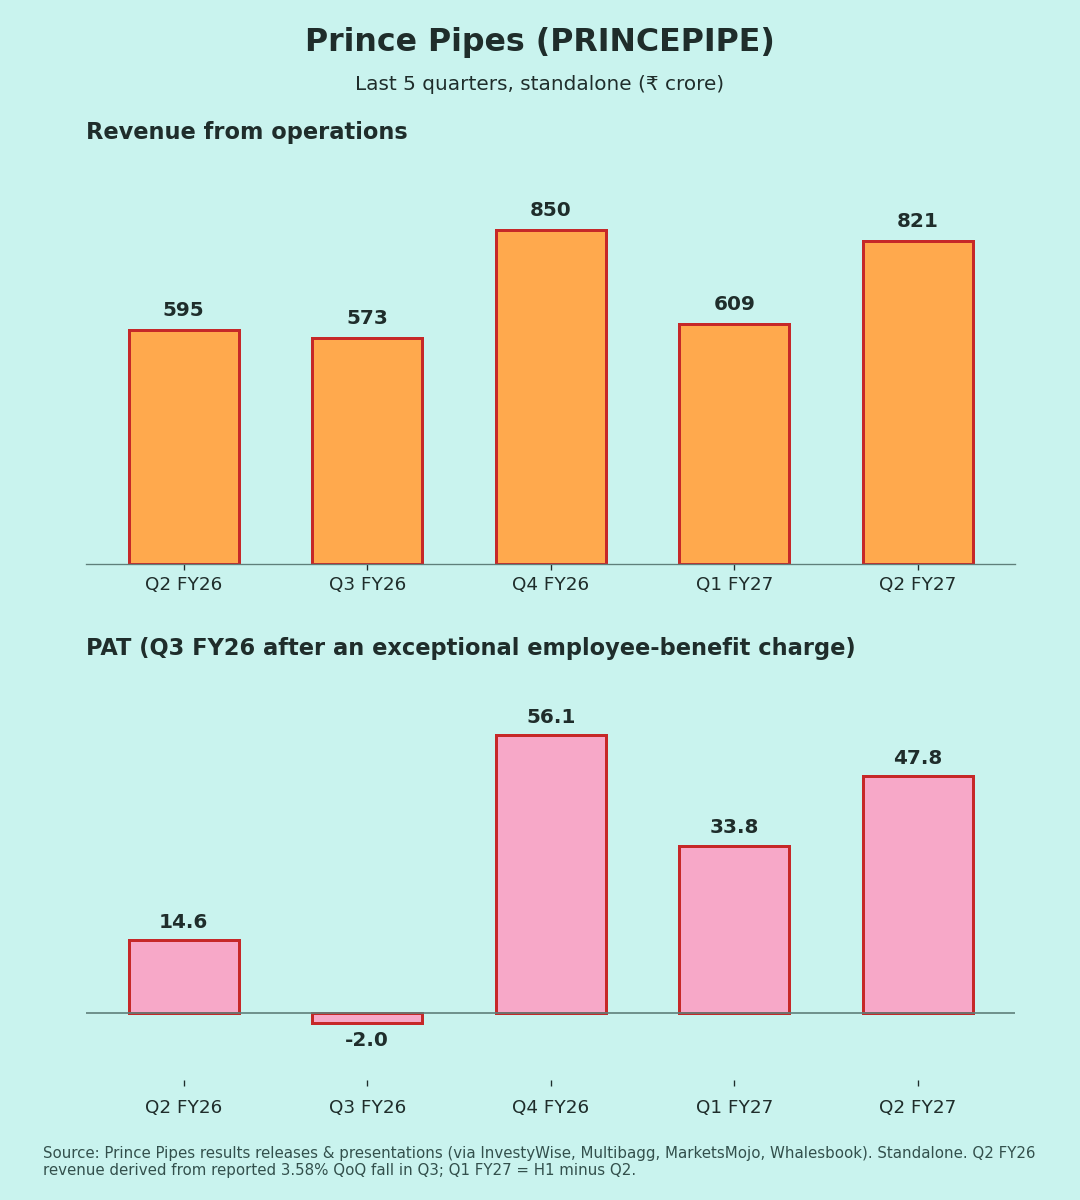
Standalone figures, ₹ crore. Results are declared today. Q2 FY26 revenue (₹594.6 cr) is derived from the reported Q3 FY26 QoQ change. YoY/QoQ %, margins and ratios are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
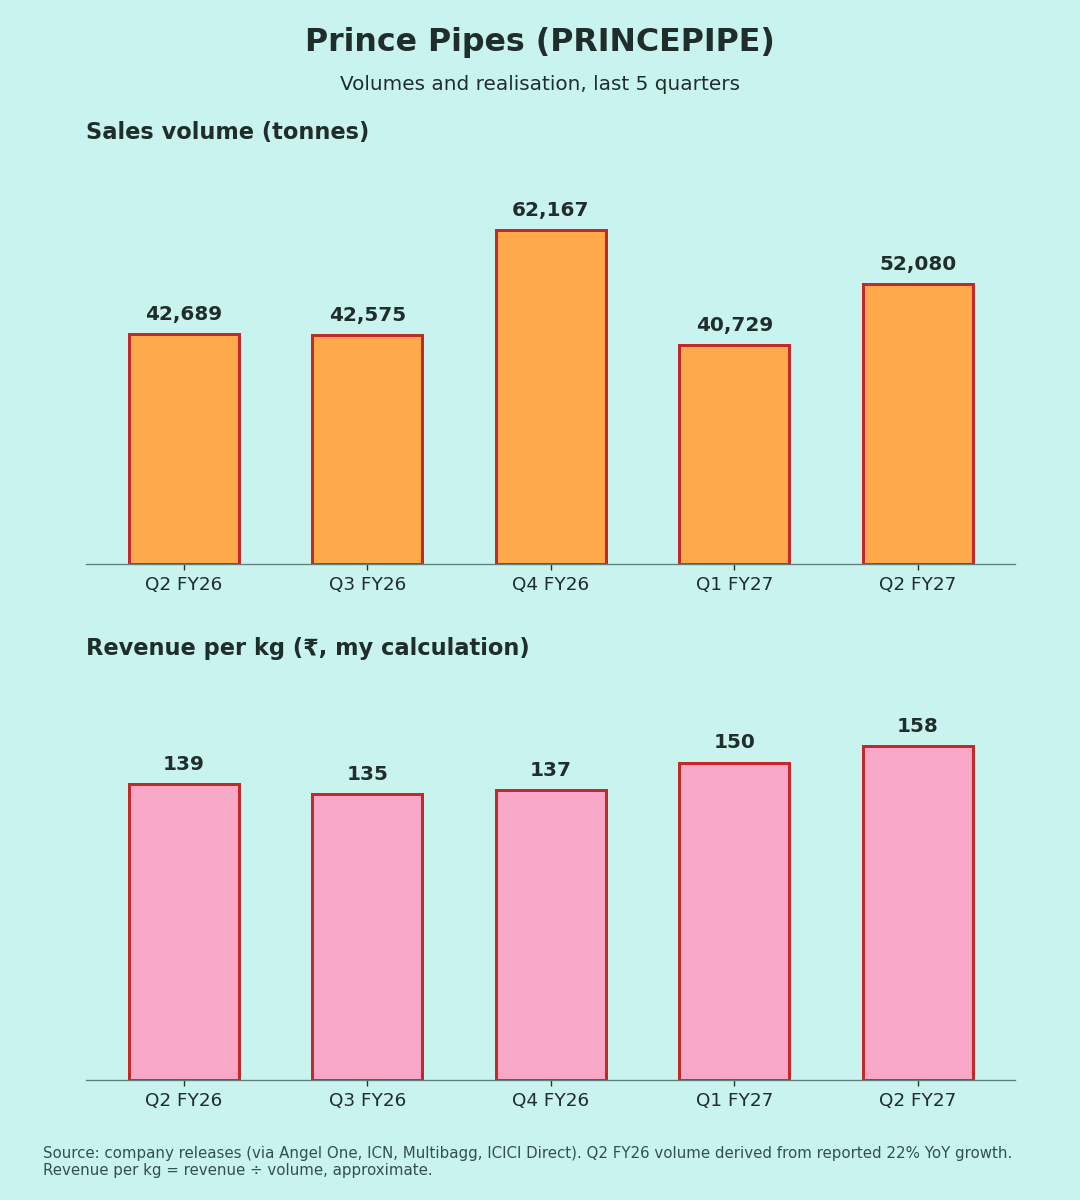
| Sales volume (tonnes) | 52,080 | +22% | +27.9% |
| Revenue from ops | 820.8 | +38.1% | +34.7% |
| EBITDA | 100 | +82.3% | +29.9% |
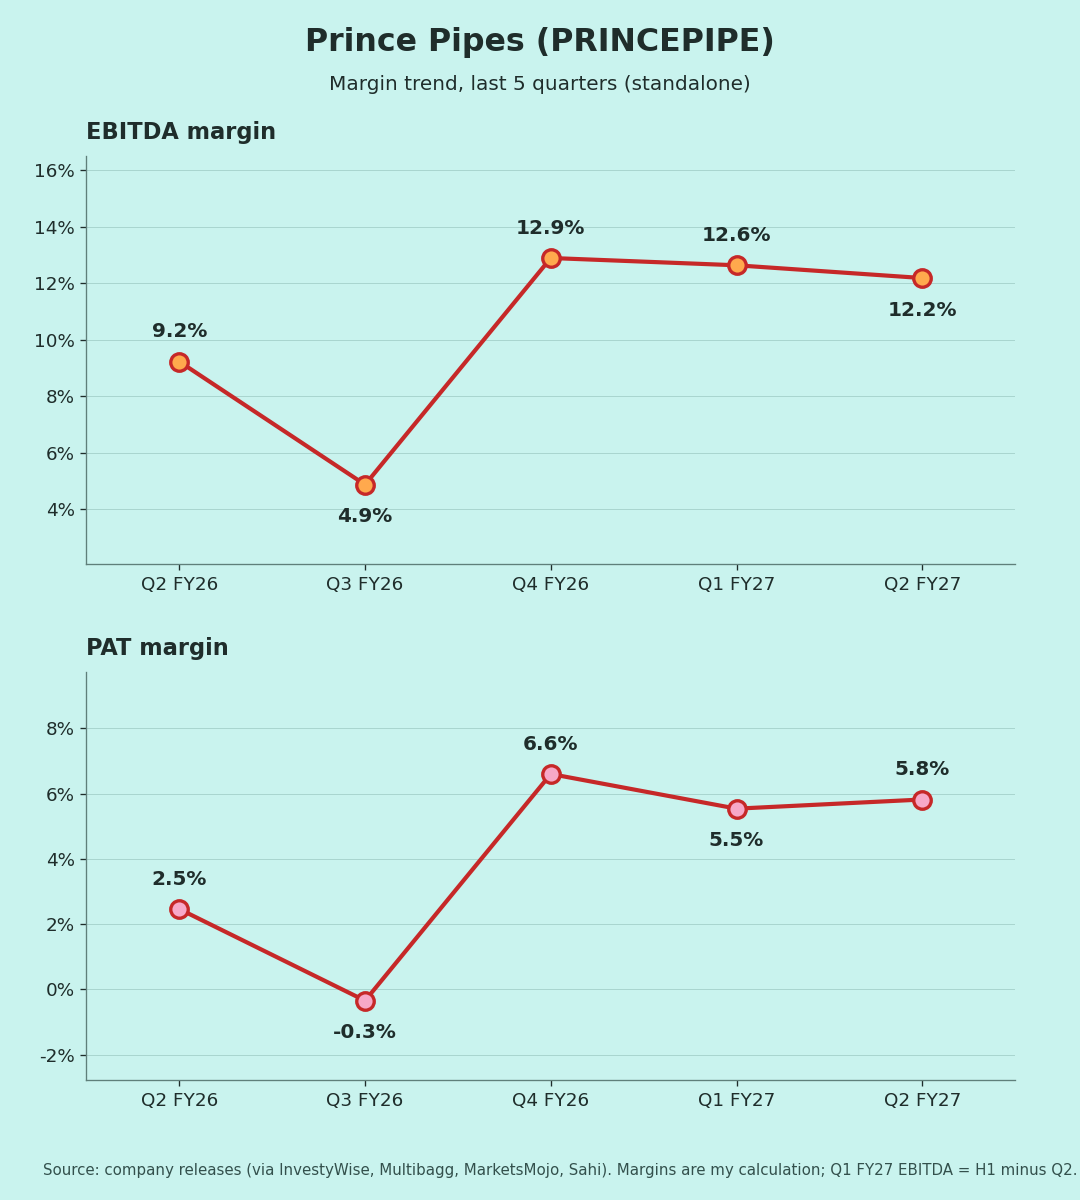
| EBITDA margin | 12.2% | 9.2% | 12.6% |
| PAT | 47.8 | +226.5% | +41.5% |
| PAT margin | 5.8% | 2.5% | 5.5% |
| Other income | ~3.1 | ~1.6 | – |
Margin rows show the year-ago and last-quarter values.
Quality of earnings
Growth is operational. Other income is only about ₹3 cr against EBITDA of ₹100 cr (total income minus revenue, my calculation from [2]).
Two drivers:
- Volume: up 22% YoY.
- Price: revenue per kg rose to about ₹158 from about ₹139 a year ago (my calculation). That points to higher PVC prices and a better product mix (interpretation).
Base effect: Q2 FY26 was a weak quarter, with a 9.2% EBITDA margin and a 2.5% PAT margin. So the +226% PAT growth is heavily flattered by a low base. QoQ (+41.5%) is the fairer read.
Cash flow is the weak spot. H1 operating cash flow was ₹46 cr vs ₹200 cr a year ago.
Margins (Chart 3)
EBITDA margin over five quarters: 9.2% → 4.9% → 12.9% → 12.6% → 12.2% [3][5][6]. Margins have held above 12% for three quarters. But they slipped slightly QoQ even as volumes rose.
In Q1, the improvement came from gross margin: raw-material cost fell even as revenue grew [7].
Guidance: what changed
- FY27 guidance (May): EBITDA margin 11–13%, volume growth 12–15%.
- Margin: H1 EBITDA margin is ~12.4% (₹177 cr on ₹1,430 cr [3]), inside the range.
- Volume: H1 volume growth is only 7% (92,809 tonnes) [2]. To hit 12–15% for the year, H2 volumes must grow roughly 16–22% (my calculation from FY26 volume of 1,91,238 tonnes [6]).
- Earnings call: scheduled for 4 Nov, 11:30 AM [9], so no updated guidance yet.
- Management: Rajat Mishra appointed Chief Business Officer; Ashok Mehra has retired; the 2017 ESOP scheme has been terminated [4].
Positives
- Volume +22% YoY and +28% QoQ
- EBITDA margin within guidance for three quarters
- Net cash at end-FY26 (net debt −₹137 cr)
Concerns
- PAT growth is mostly a low-base effect (my view)
- H1 volume growth lags the guidance
- Operating cash flow fell sharply in H1
- Bathware is still loss-making (₹5 cr loss on ₹16 cr revenue in Q4 FY26)
Things to track in Q3 FY27
- Volume growth vs the 12–15% target
- EBITDA margin vs the 11–13% band as PVC prices move
- Working capital and cash flow
- guidance from the 4 Nov (tomorrow call)
Not a buy/sell recommendation.Facts are sourced; opinions are labelled.
Sources [1] Whalesbook – Q2 FY27 filing, 3 Nov 2026 · [2] Angel One – Q2 FY27 results · [3] InvestyWise – Q2 FY27 presentation · [4] InvestyWise – board outcome · [5] MarketsMojo – Q3 FY26 · [6] Multibagg – Q4 FY26 · [7] Multibagg – Q1 FY27 · [8] ScanX – FY26 results & FY27 guidance · [9] Multibagg – Q2 call schedule · [10] Multibagg – Q3 FY26 · [11] Prince Pipes – Q4 FY25 presentation · [12] AlphaStreet – Q4 FY23 call
Charts:
(1) last 5 quarters revenue & PAT
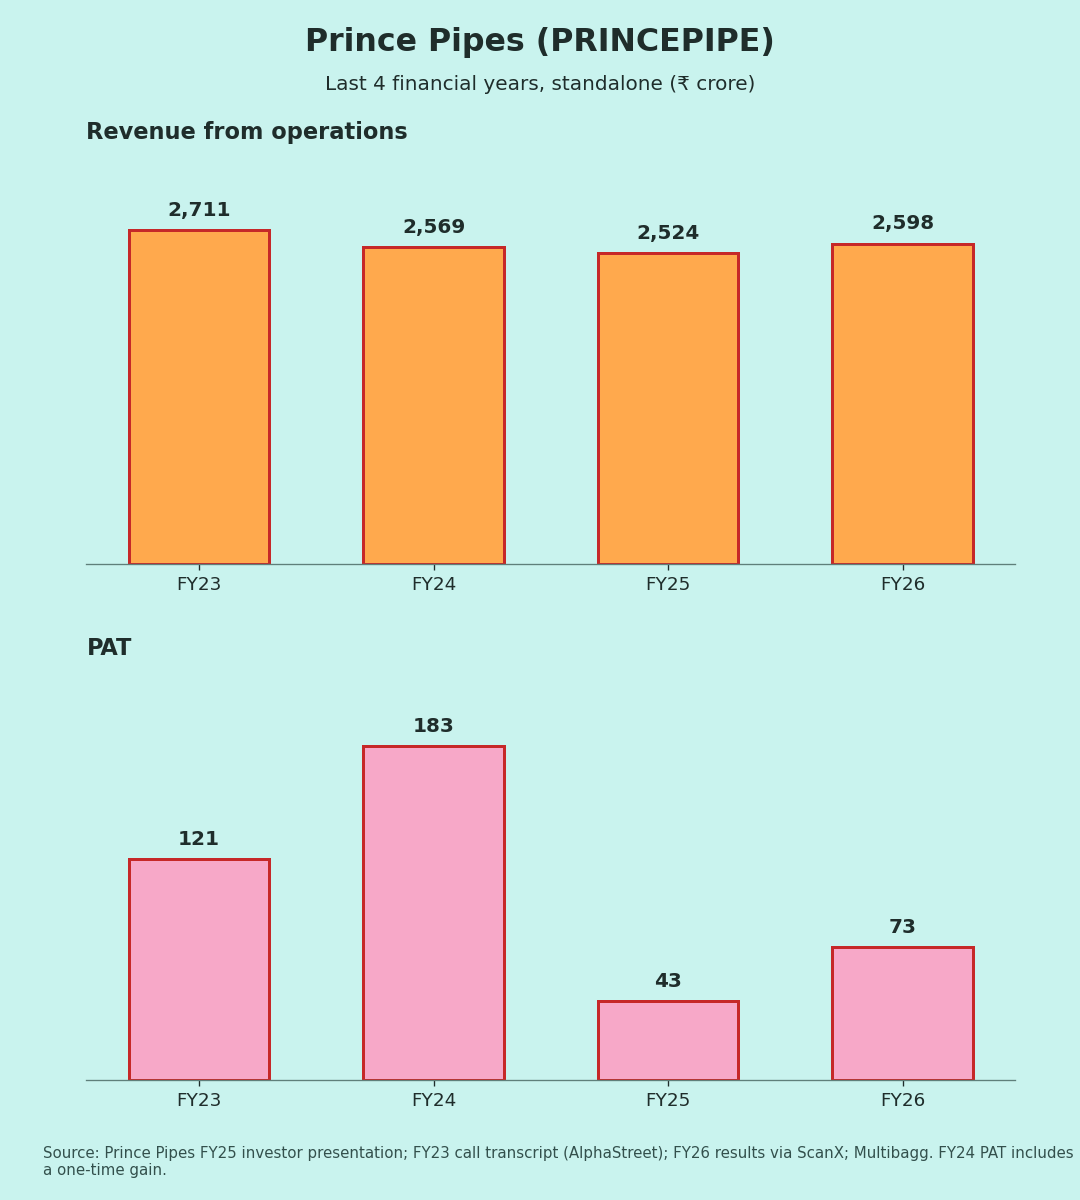
(2) FY23–FY26 revenue & PAT
(3) EBITDA and PAT margin (own calc.)
(4) volumes and revenue per kg (own calc.).