Consolidated figures, ₹ crore, from the company's earnings presentation unless stated.
Results were filed on 3 Nov 2026 . YoY/QoQ % are my calculations.
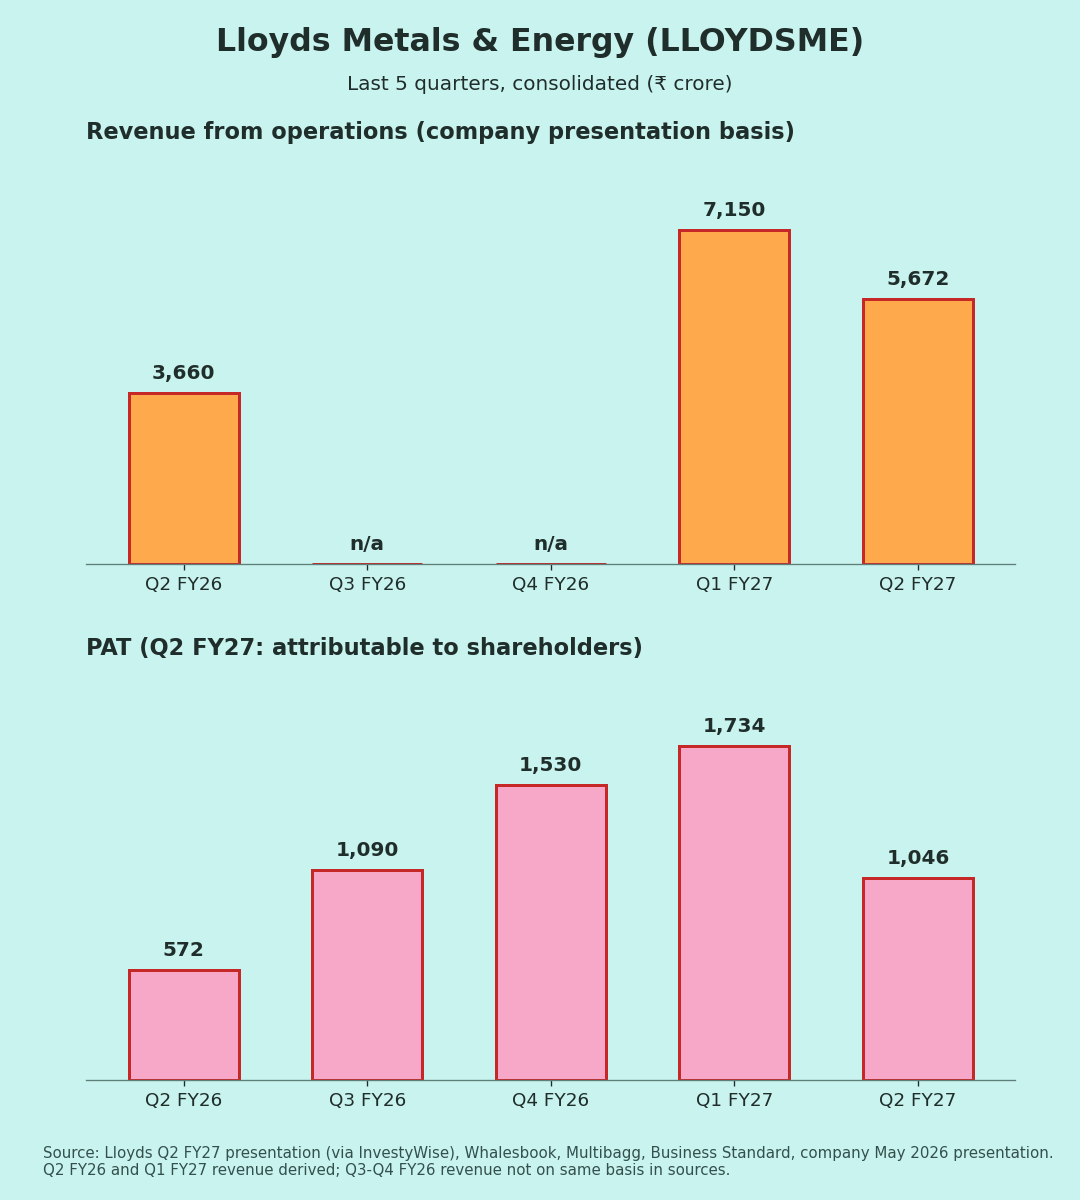
Q2 FY26 revenue is derived from the reported +55%, and Q1 FY27 figures are H1 minus Q2.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 5,672.5 | +55% | −20.7% |
| EBITDA | 1,803.5 | +75% | −35.4% |
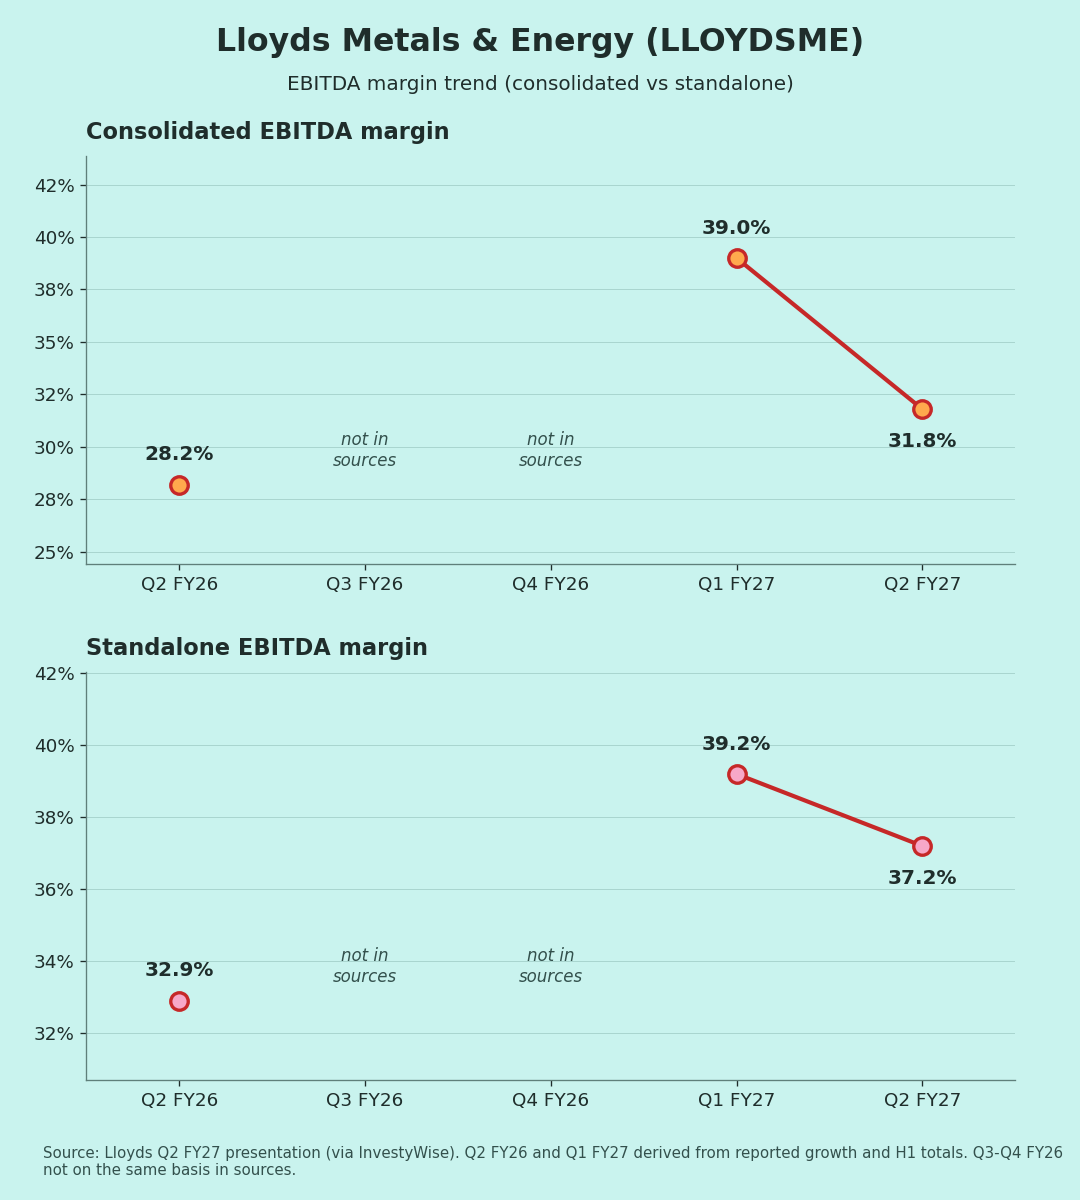
| EBITDA margin | 31.8% | 28.2% | 39.0% |
| PAT | 1,045.6 | +82.7% | −39.7% |
| Standalone EBITDA margin | 37.2% | 32.9% | 39.2% |
Margin rows show the year-ago and last-quarter values.
Read YoY and QoQ together
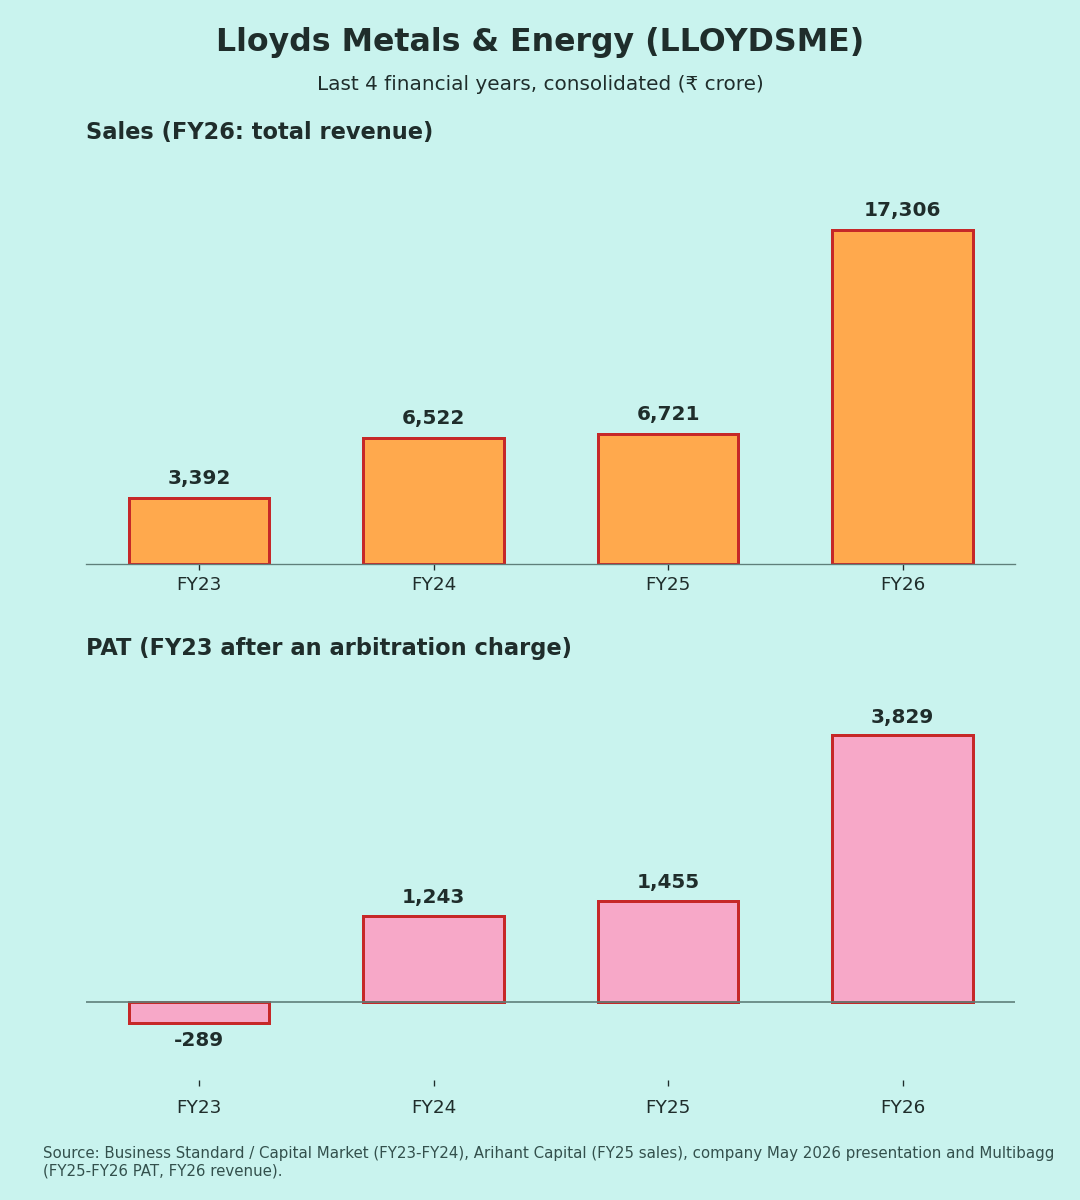
Iron ore output roughly doubled in FY26, and a second pellet plant started in May 2026.
But the quarter itself was softer than Q1. Revenue fell 21% QoQ, EBITDA 35% and PAT 40%. Standalone revenue also fell, to ₹4,132 cr from about ₹5,413 cr (my calculation from [1]). The sources don't explain the drop yet. Iron ore mining usually slows in the monsoon quarter (interpretation).
Quality of earnings
- Standalone vs consolidated: standalone EBITDA margin (37.2%) is well above consolidated (31.8%) [1]. So the subsidiaries earn lower margins (my reading).
- No exceptional items are reported. Other income and tax lines weren't in my sources.
- Debt: net debt is about ₹9,316 cr after heavy capex [7]. The board also approved raising up to USD 300 mn [2].
Margins (Chart 3)
Consolidated EBITDA margin: 28.2% a year ago, 39.0% in Q1 and 31.8% in Q2 [1]. Q3–Q4 FY26 margins on the same basis weren't in my sources.
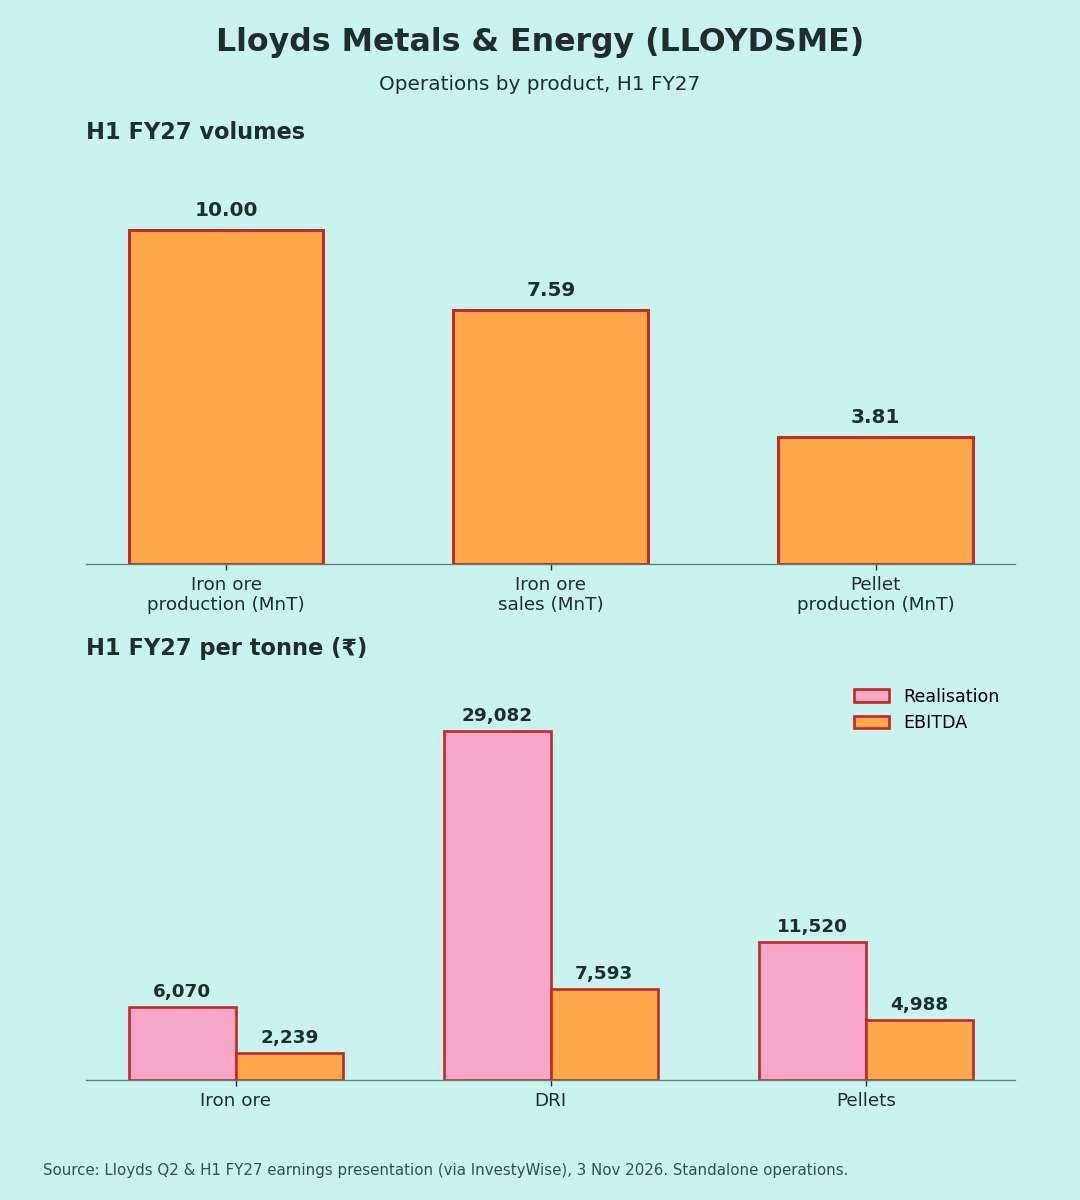
H1 per-tonne economics for the standalone business [1]:
| Product | Realisation | EBITDA per tonne |
| Iron ore | ₹6,070 | ₹2,239 |
| DRI | ₹29,082 | ₹7,593 |
| Pellets | ₹11,520 | ₹4,988 |
Guidance: what changed
- FY27 targets (May): 26 MnT iron ore, 7.75–8 MnT pellets and 825 kt DRI [5].
- H1 actual: iron ore production of 10.00 MnT (+35% YoY), about 38% of the target, so H2 needs ~16 MnT (my calculation). Pellet production of 3.81 MnT is about half the target [1].
- New capex: a 360 MW thermal power plant at Konsari (₹3,240 cr) and stakes of up to 30% in renewable projects for captive use [2][8].
- Pipeline: a 1.2 MnT steel plant and BHQ beneficiation are under way, with a 195 km slurry pipeline and Pellet Plant 3 planned [1].
Positives
- Revenue +55% and EBITDA +75% YoY [1]
- Second pellet plant running since May [1]
- Pellets and DRI add value beyond raw ore [1]
Concerns
- Sharp QoQ fall in revenue, margin and profit [1][3]
- H2 must deliver ~62% of the FY27 iron ore target (my calculation)
- Rising debt and large new capex [2][7]
Things to track in Q3 FY27
- Iron ore production run-rate vs 26 MnT
- EBITDA margin: back toward Q1's 39%?
- Net debt as capex and the USD 300 mn raise progress
- Management's explanation of the Q2 dip (call on 4 Nov)
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – Q2 & H1 FY27 earnings presentation · [2] Whalesbook – Q2 FY27 PAT, capex, fund raise · [3] Multibagg – Q1 FY27 figures, call date · [4] Business Standard – Q2 FY26 · [5] Multibagg – FY26 results & FY27 guidance · [6] Multibagg – Q2 call schedule · [7] Groww – results summary, net debt · [8] InvestyWise – board approvals · [9] NSE – May 2026 presentation · [10] HDFC Sec / Capital Market – FY23–FY24 · [11] Arihant Capital – annual sales
Charts: (1) last 5 quarters revenue & PAT , Q3–Q4 FY26 revenue not on the same basis in sources; (2) FY23–FY26 sales & PAT , FY26 uses total revenue and FY23 includes an arbitration charge; (3) consolidated vs standalone EBITDA margin [1]; (4) H1 volumes and per-tonne economics [1].