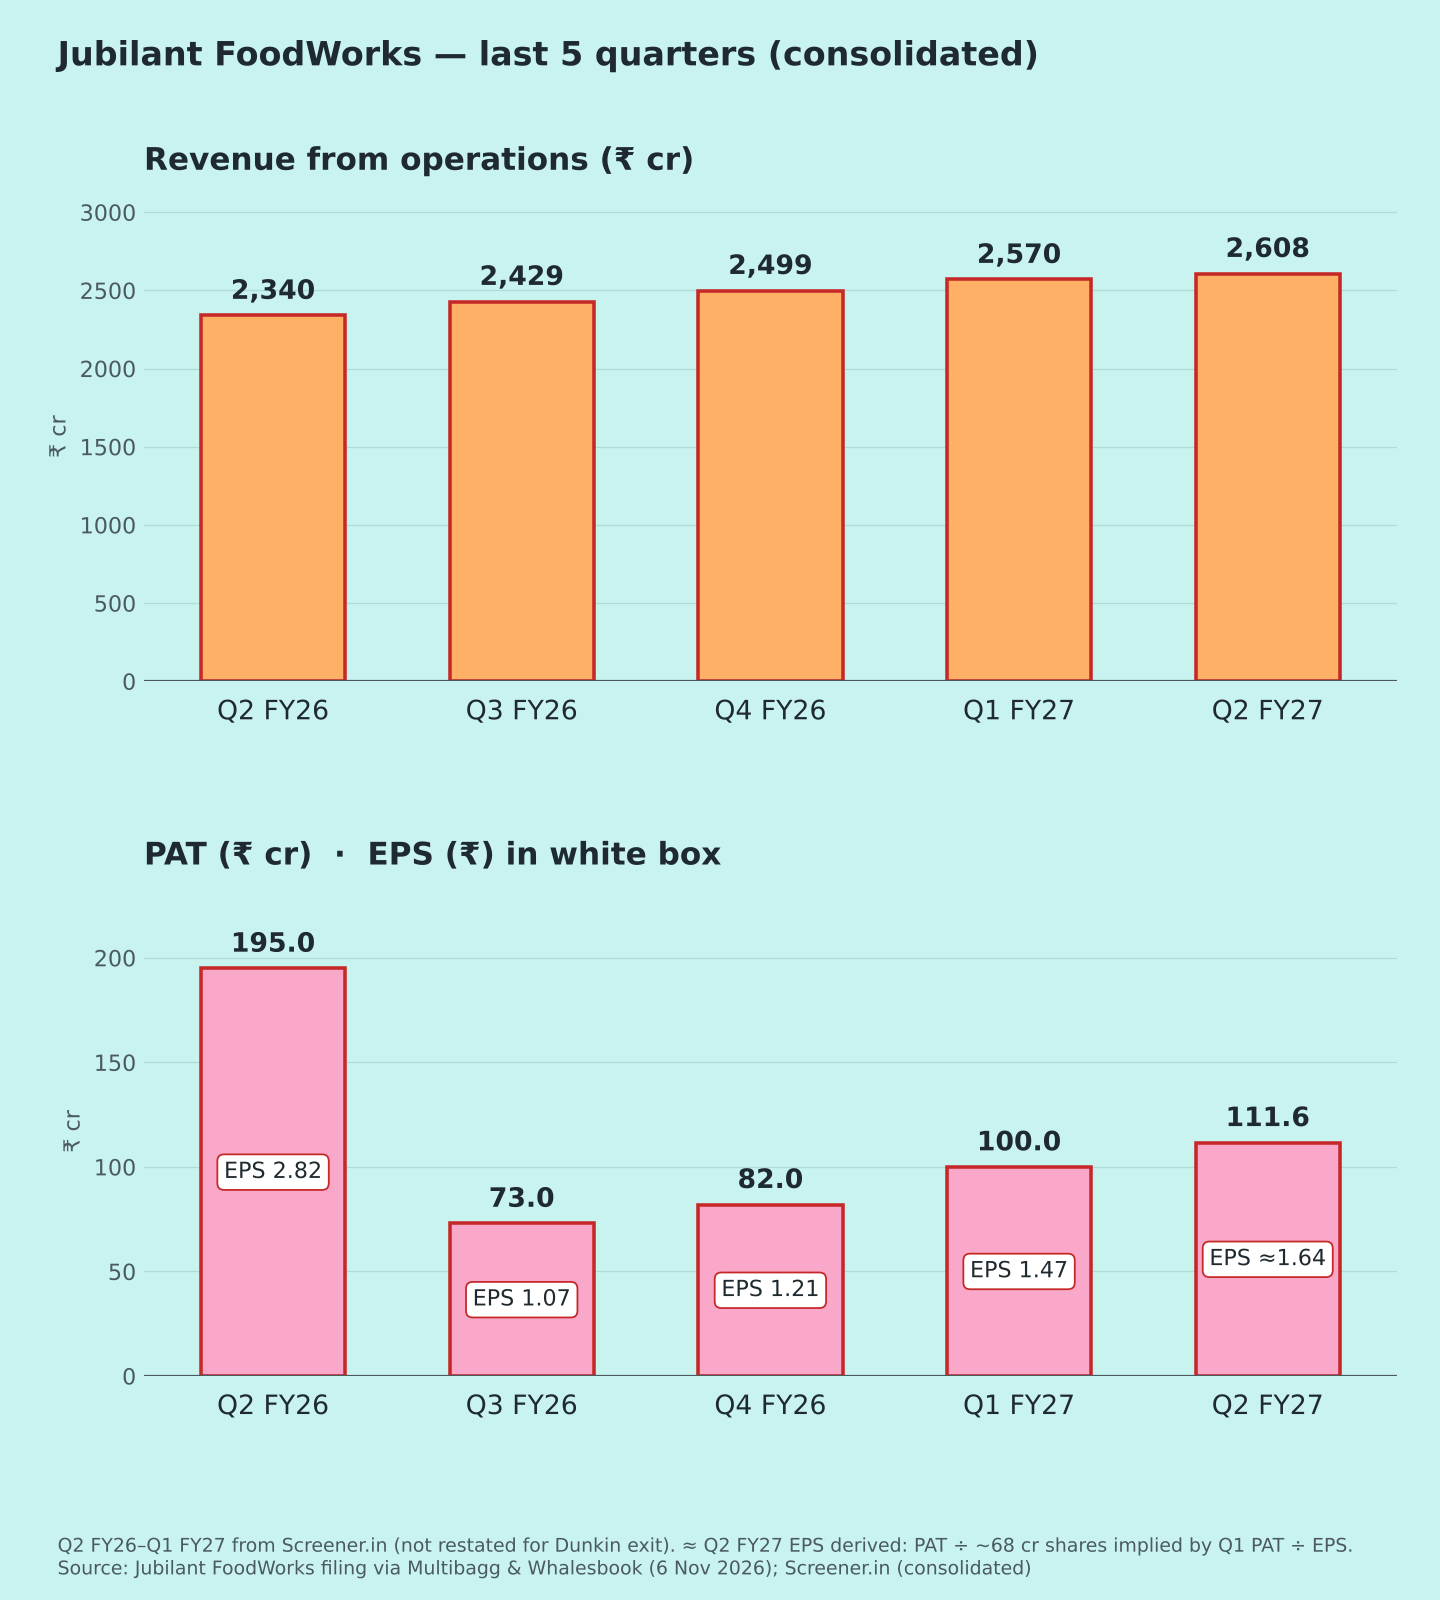
Consolidated figures, ₹ crore. Results announced 6 Nov 2026. Dunkin' is now reported as discontinued, and the company restated Q2 FY26 [1]. "Total PAT" is all profit including discontinued operations [2]; "continuing PAT" excludes Dunkin' and exceptional items [1]. EBITDA is post Ind AS 116 and excludes other income. Q2 EPS is derived.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 2,607.9 | +11.8% | +1.5% |
| EBITDA | 513.1 | +7.3% | +1.8% |
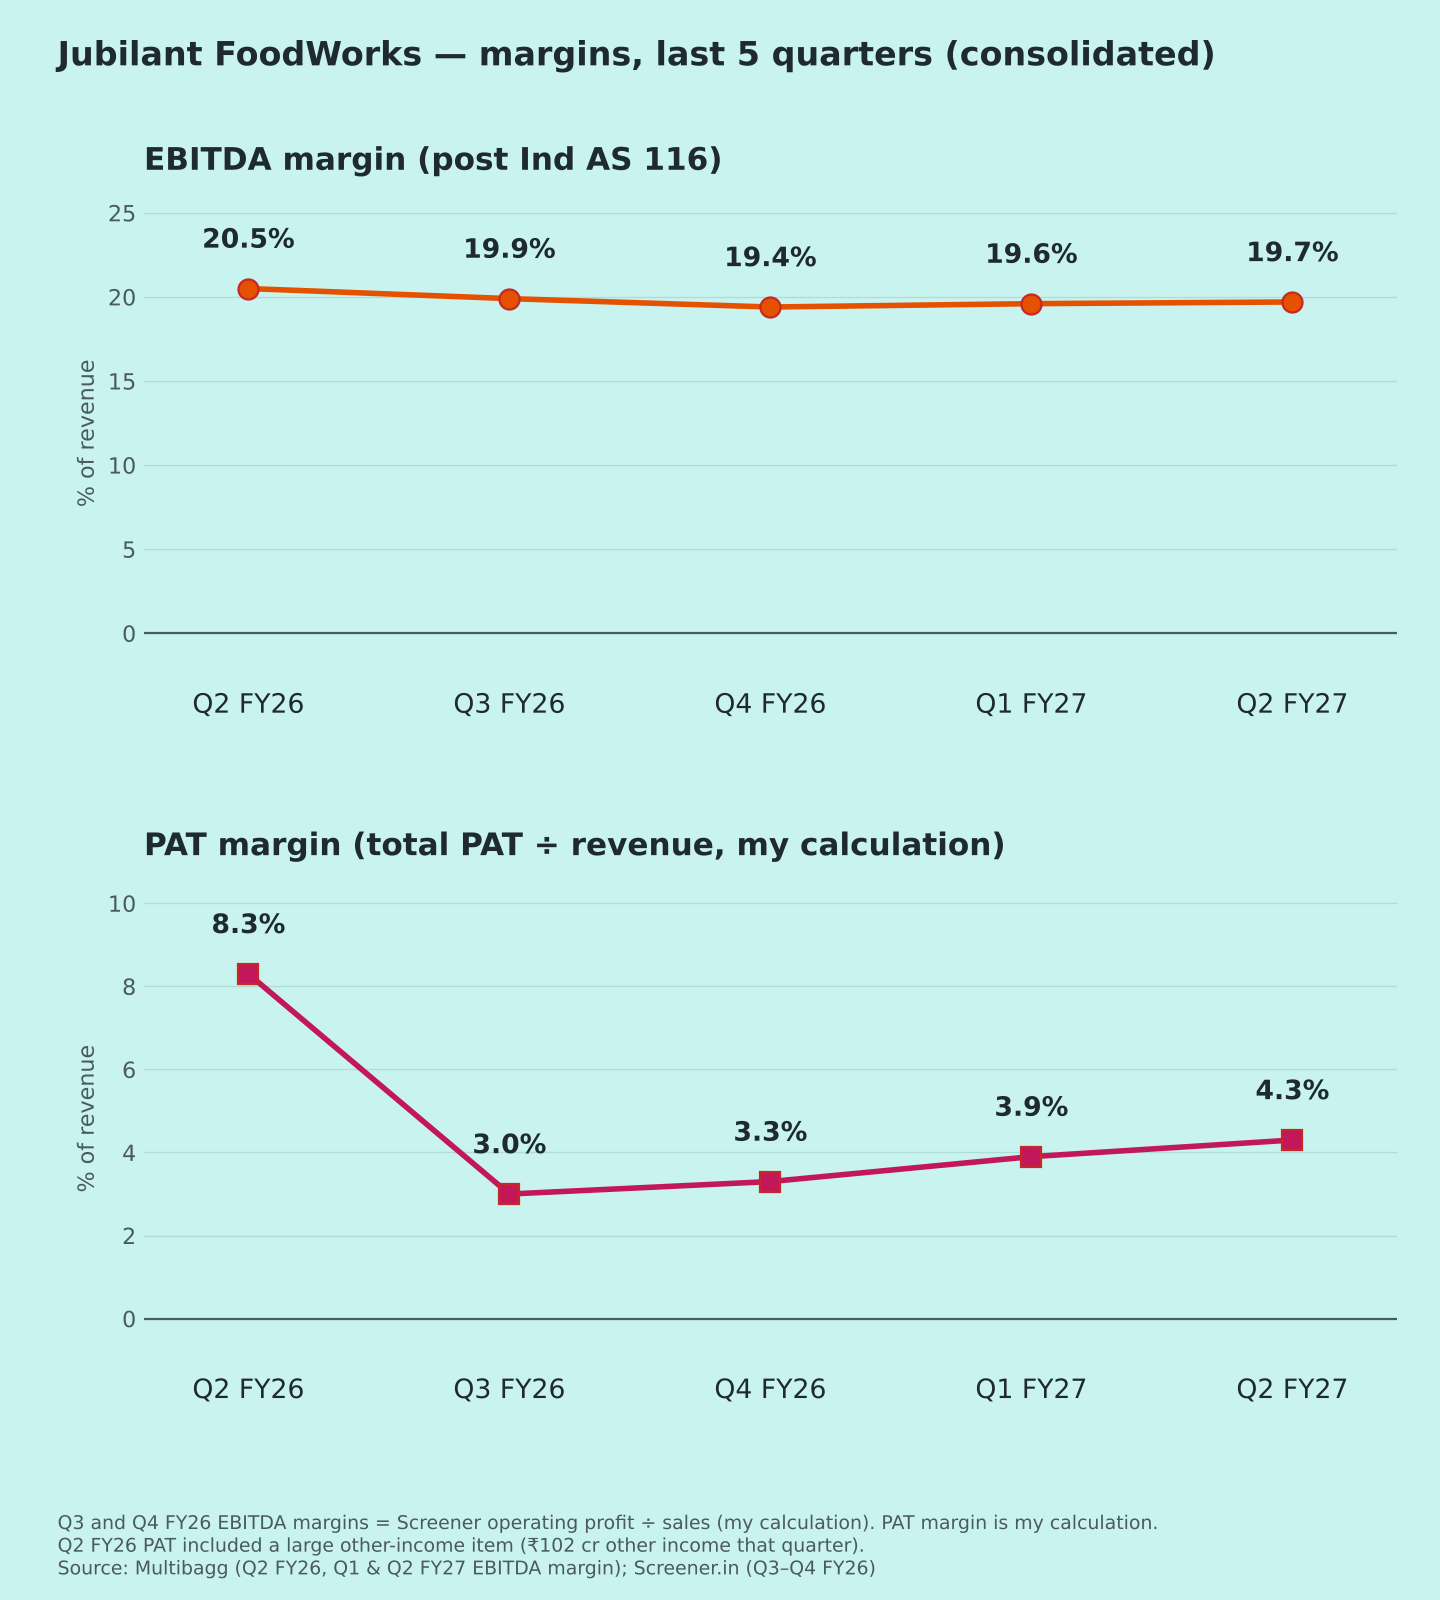
| EBITDA margin | 19.7% | 20.5% | 19.6% |
| Continuing PAT (before exceptional) | 113.9 | +0.4% | +10.4% |
| Total PAT | 111.6 | −42.7% | +11.6% |
| PAT margin (total) | 4.3% | 8.3% | 3.9% |
| EPS (₹, ≈ derived) | ≈1.64 | 2.82 → ≈1.64 | 1.47 → ≈1.64 |
Margin rows show year-ago and last-quarter values. ≈ EPS = total PAT ÷ ~68 cr shares (implied by Q1 PAT ÷ Q1 EPS on Screener). % changes and margins are my calculations.
Source notes: Revenue of ₹2,608.7 cr was the 8 Oct business update [4]. The final figure is ₹2,607.9 cr [1].
Quality of earnings
- The YoY profit fall is mostly a base effect. Q2 FY26 total PAT of ₹194.6 cr was ~₹81 cr above its continuing PAT of ₹113.4 cr [1][2]. That quarter also had ₹102 cr of other income [3]. On a continuing basis, profit was flat (+0.4%), and that is the fairer read.
- Costs below EBITDA are rising with the store build-out. Q1 depreciation was ₹255 cr vs ₹230 cr, and interest ₹120 cr vs ₹106 cr [3].
- Turkey's hyperinflation accounting pulled DP Eurasia's EBITDA down 2.4% [1].
Margins (Chart 3)
EBITDA margin: 20.5% → 19.9% → 19.4% → 19.6% → 19.7% [1][3]. It has been broadly stable after the dip. Management attributed the YoY fall to the hyperinflation adjustments in DP Eurasia [1].
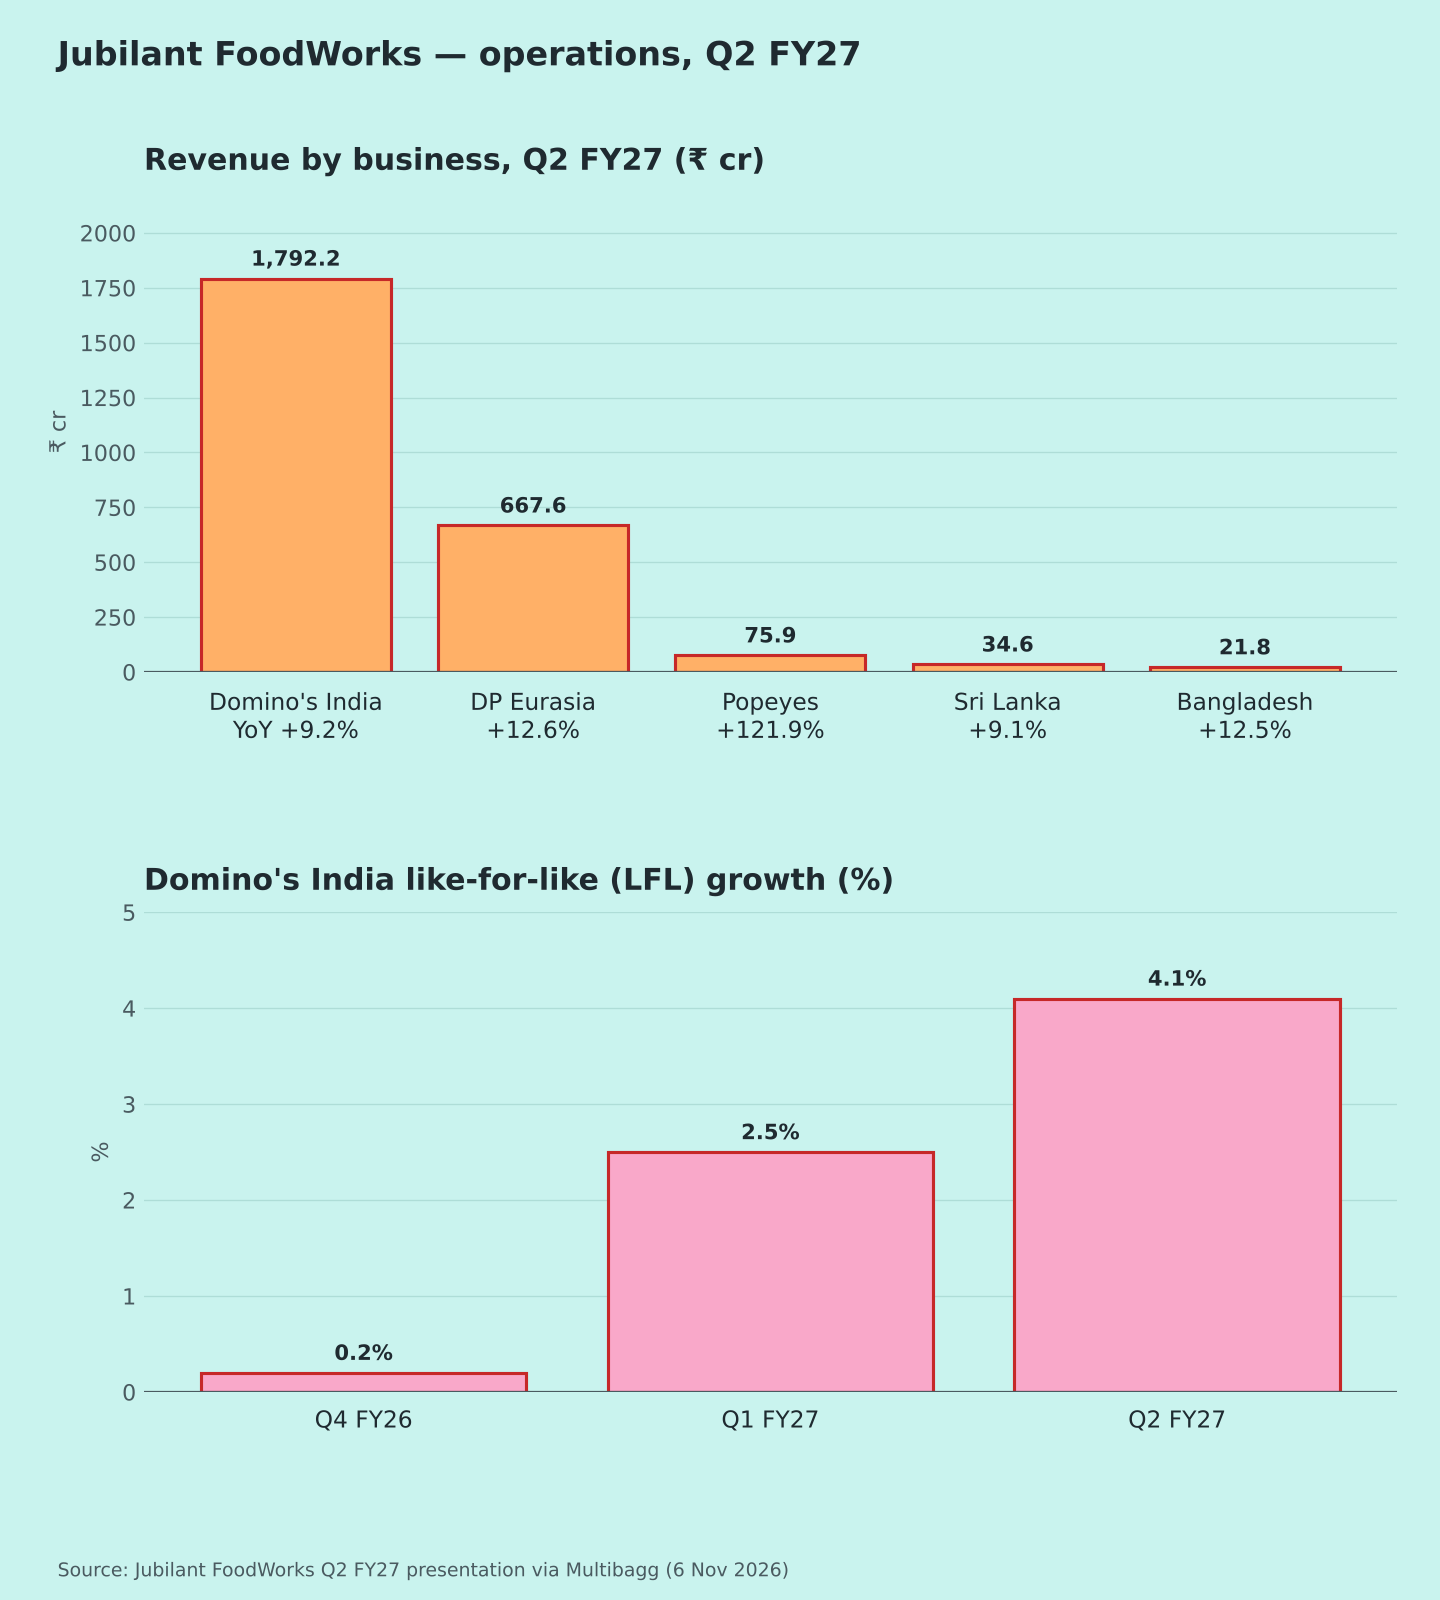
Businesses (Chart 4) [1]
- Domino's India: revenue ₹1,792.2 cr, +9.2%. Like-for-like (LFL) growth was 4.1%, up from 2.5% in Q1 and 0.2% in Q4 FY26. Orders +6.3%. Added 88 stores (total 2,601). Gross margin 75.8%.
- Popeyes: revenue ₹75.9 cr, +121.9%; LFL +53%; 99 stores.
- DP Eurasia: revenue ₹667.6 cr, +12.6%. Turkey LFL was −2.1% after inflation adjustment.
- Sri Lanka: ₹34.6 cr, +9.1%. Bangladesh: ₹21.8 cr, +12.5%.
No updated store or margin guidance was found in coverage. The call was at 5 pm on 6 Nov [1].
Positives
- Domino's India LFL improving for three quarters [1]
- Popeyes scaling fast [1]
Concerns
- Continuing profit is flat despite 12% revenue growth [1]
- Hyperinflation noise in Turkey [1]
Things to track in Q3 FY27
- Domino's India LFL in the festive quarter
- Depreciation and interest vs EBITDA
- Popeyes store-level returns
- DP Eurasia after inflation accounting
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Multibagg – Q2 results & presentation · [2] Whalesbook – Q2 consolidated profit · [3] Screener.in – consolidated · [4] Kotak Neo – 8 Oct business update
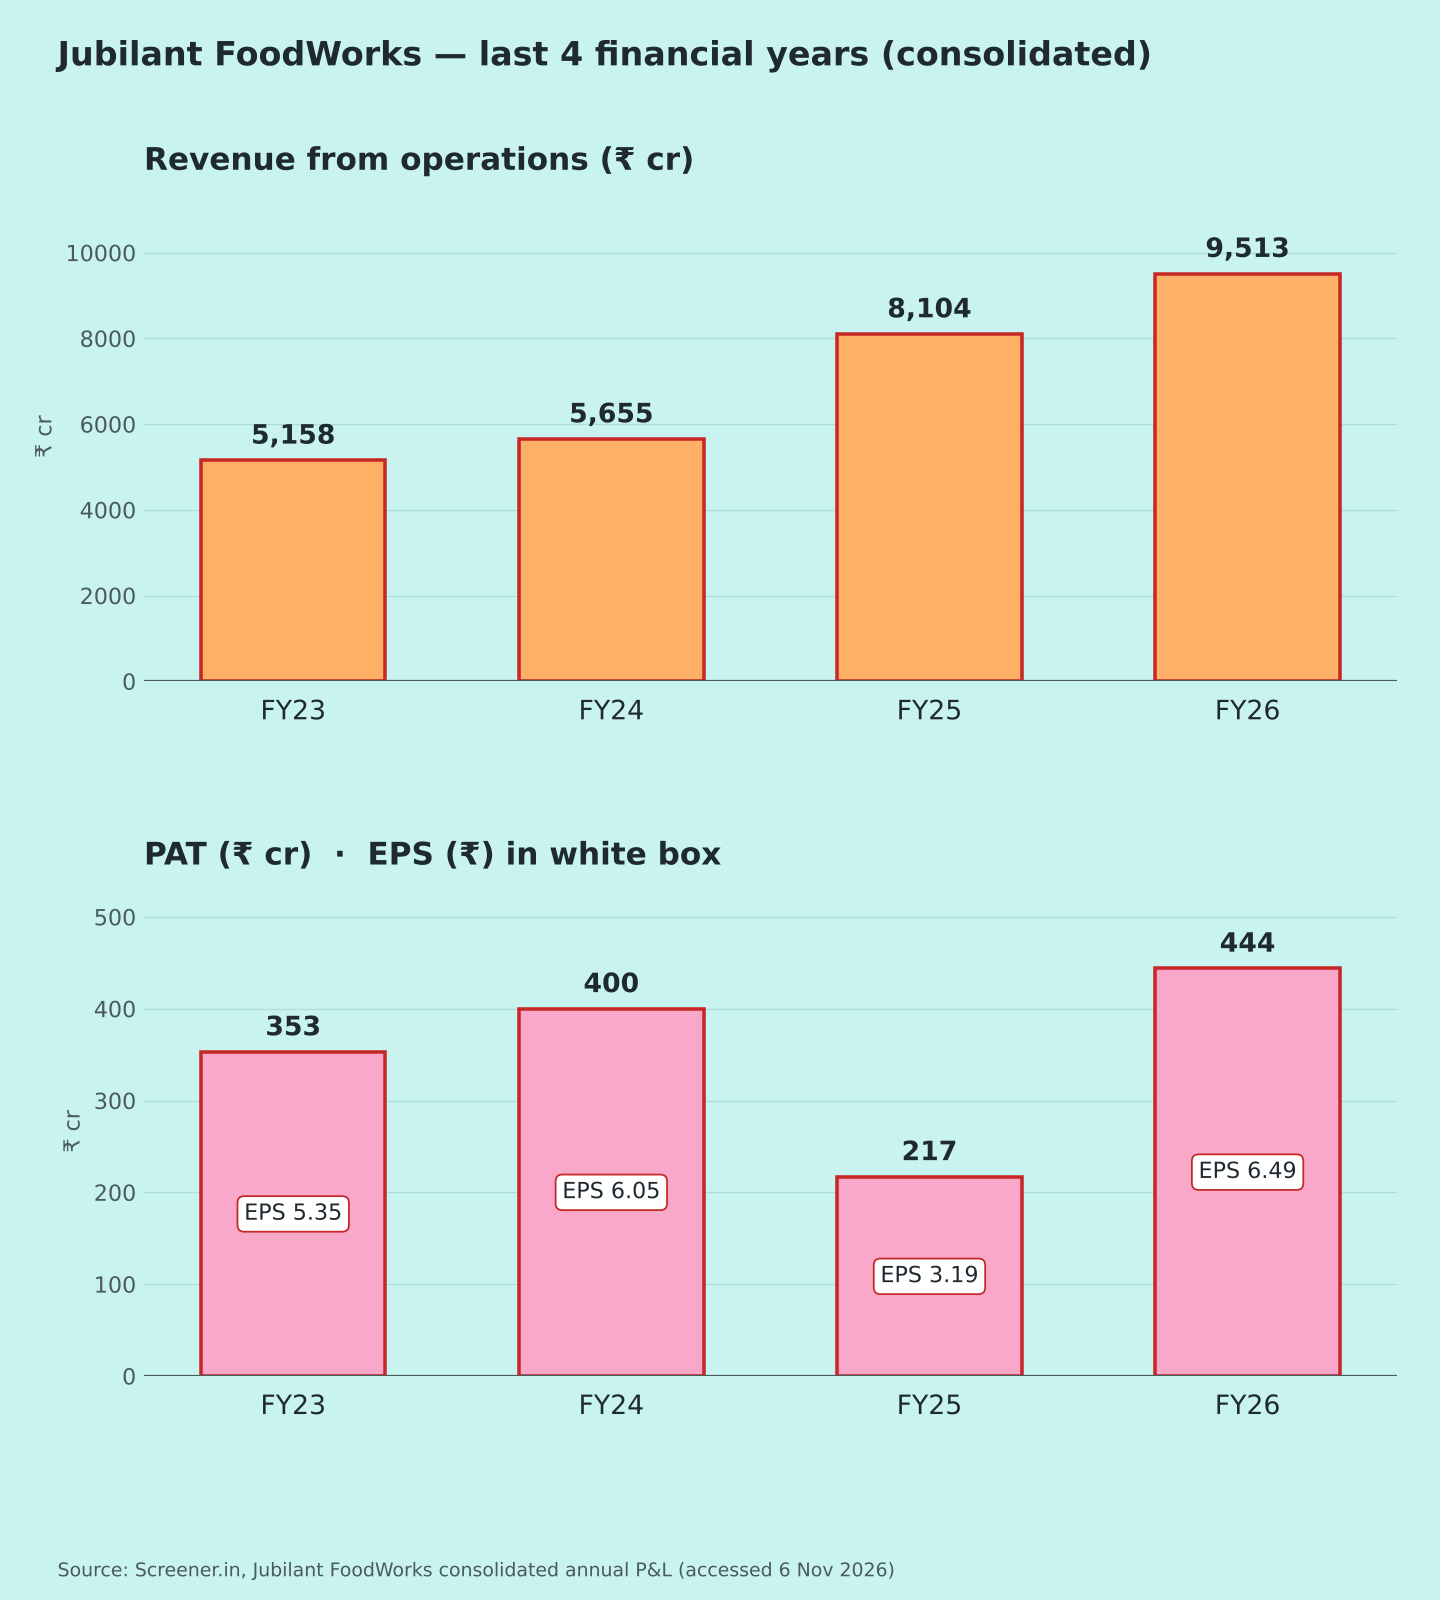
Charts: (1) 5 quarters revenue & PAT with EPS; (2) FY23–FY26 [3]; (3) margins; (4) businesses & LFL