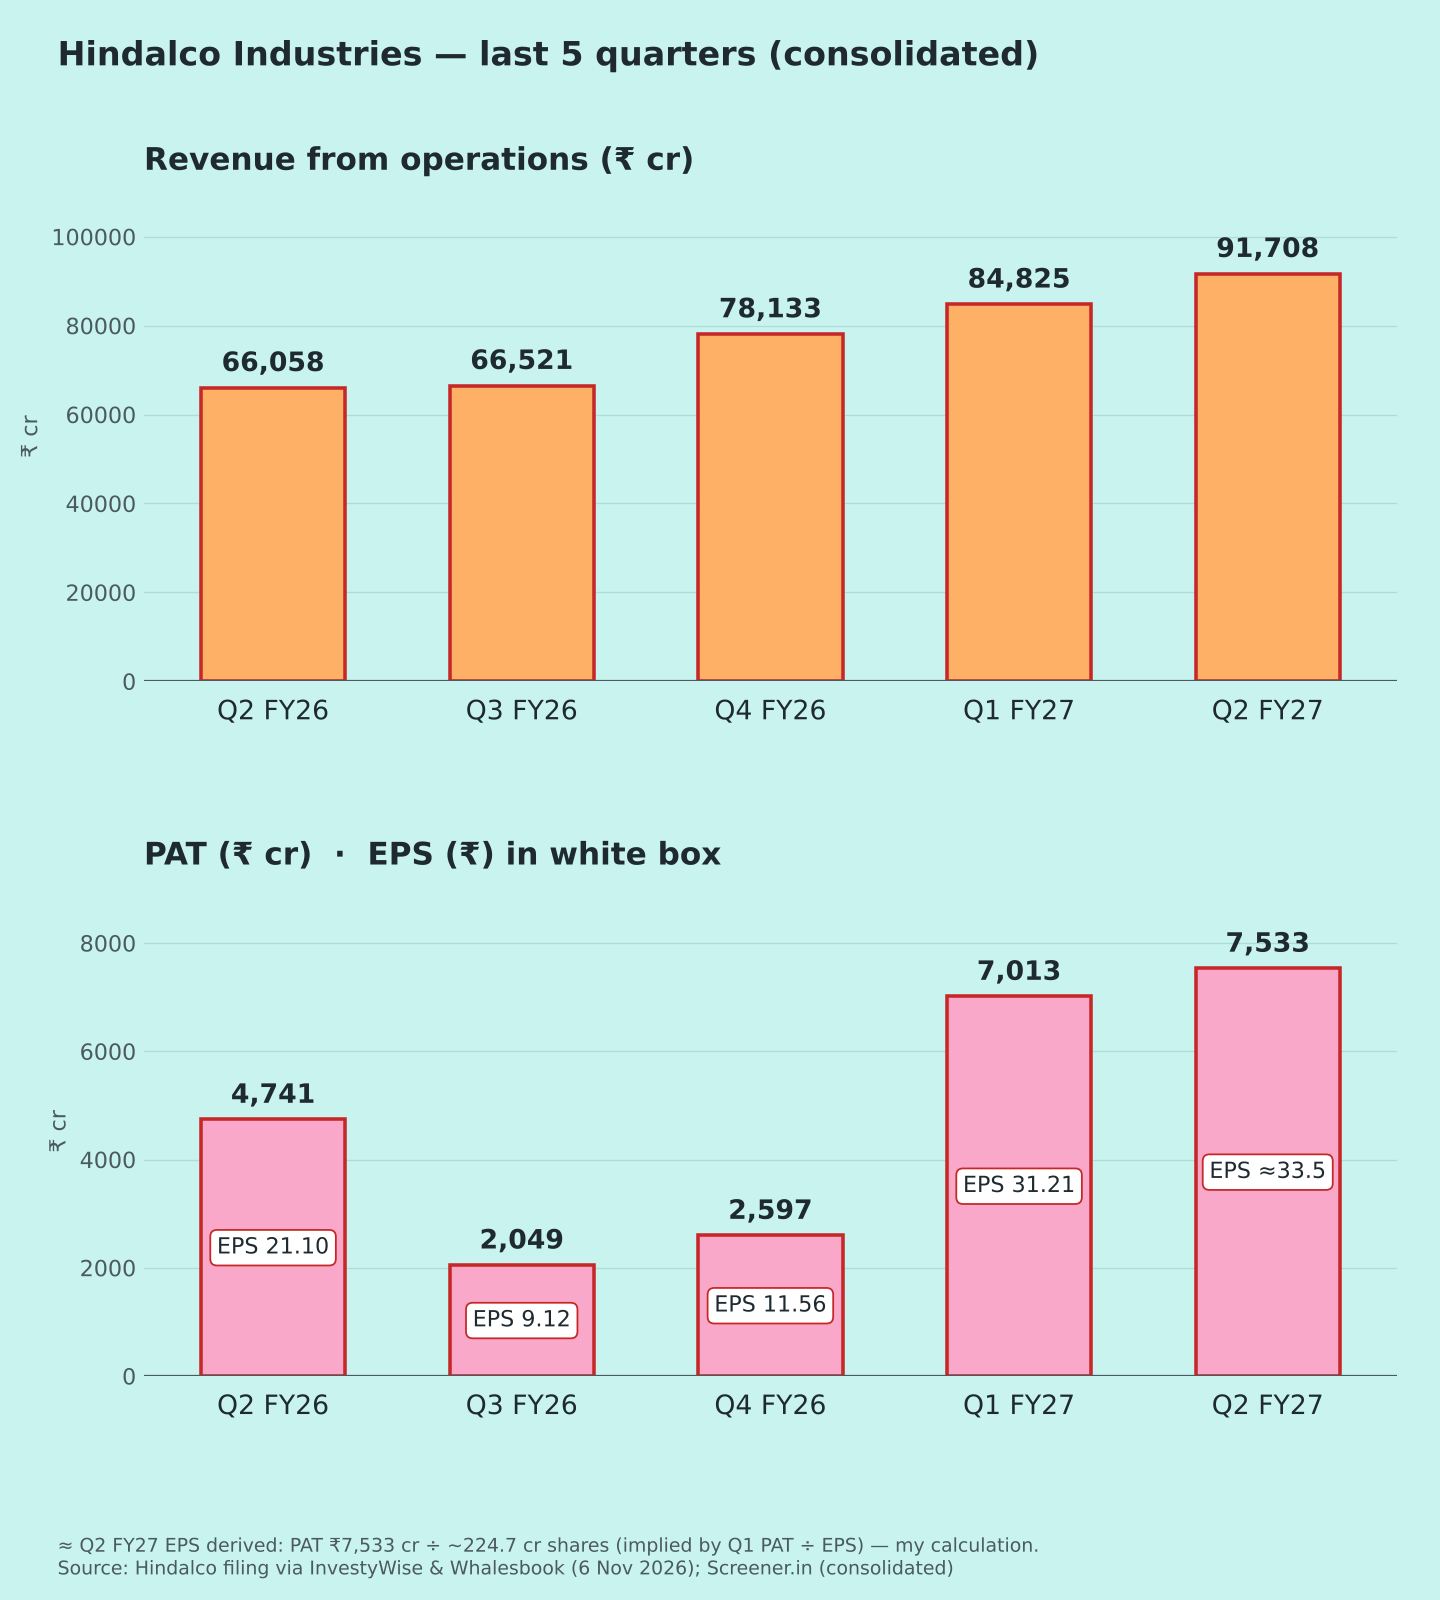
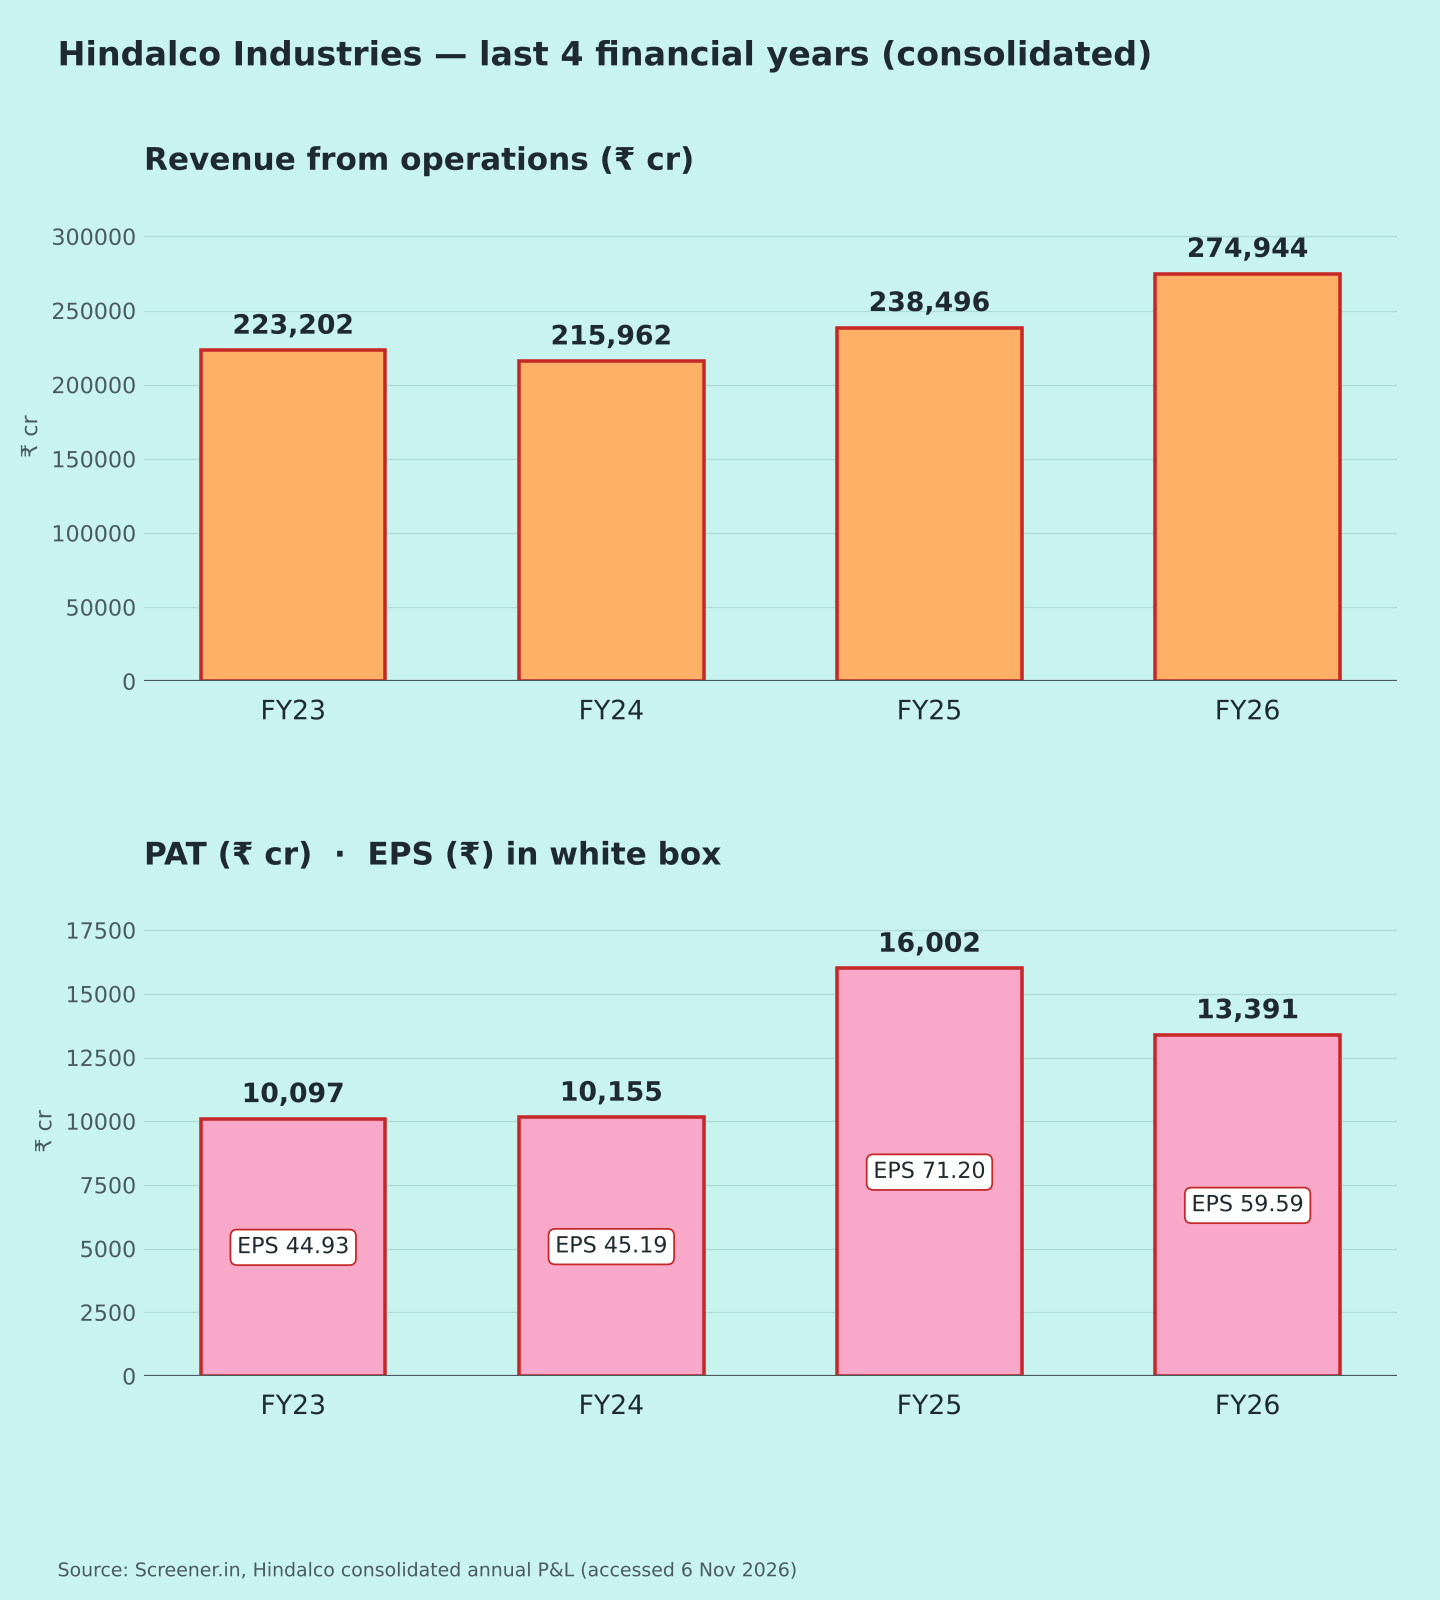
Consolidated figures, ₹ crore. Results announced 6 Nov 2026. PAT is the headline consolidated PAT. EPS is derived.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 91,708 | +38.8% | +8.1% |
| EBITDA | 13,757 | +42% | — |
| EBITDA margin | 15.0% | ≈14.7% | — |
| PAT | 7,533 | +58.9% | +7.4% |
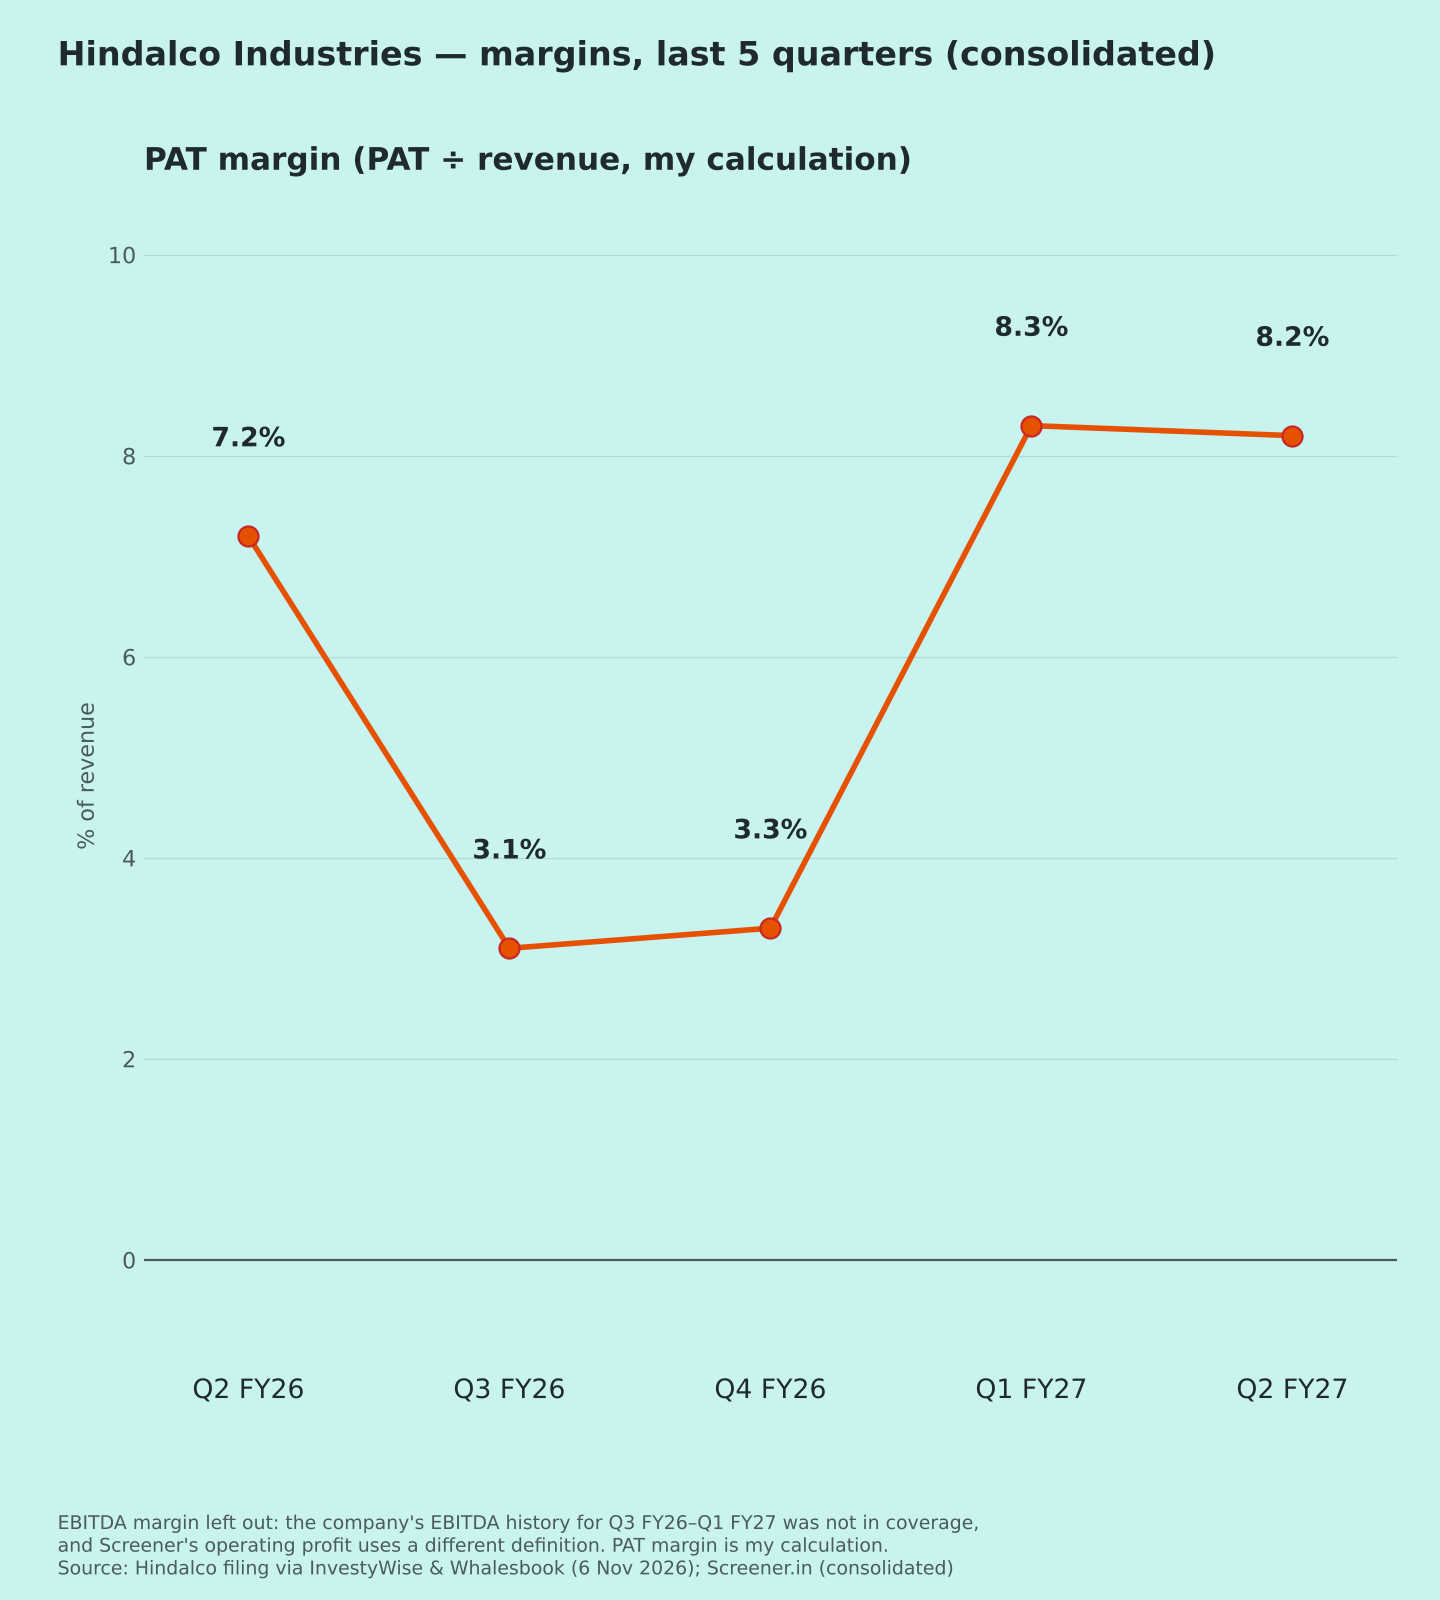
| PAT margin | 8.2% | 7.2% | 8.3% |
| EPS (₹, ≈ derived) | ≈33.5 | 21.10 → ≈33.5 | 31.21 → ≈33.5 |
| Net debt / EBITDA | 1.80x | 1.23x | — |
Margin and ratio rows show year-ago and last-quarter values. "—" = Q1 company figure not in coverage. ≈ derived: year-ago EBITDA margin worked back from +42%; EPS = PAT ÷ ~224.7 cr shares (Q1 PAT ÷ Q1 EPS). QoQ % and margins are my calculations.
Source notes: The live blog gives PAT of ₹7,532 cr [6]; other coverage gives ₹7,533 cr [1][3]. One site reports "profit up 7.4%" [7]. That is the QoQ change; the YoY change is +59%.
Quality of earnings
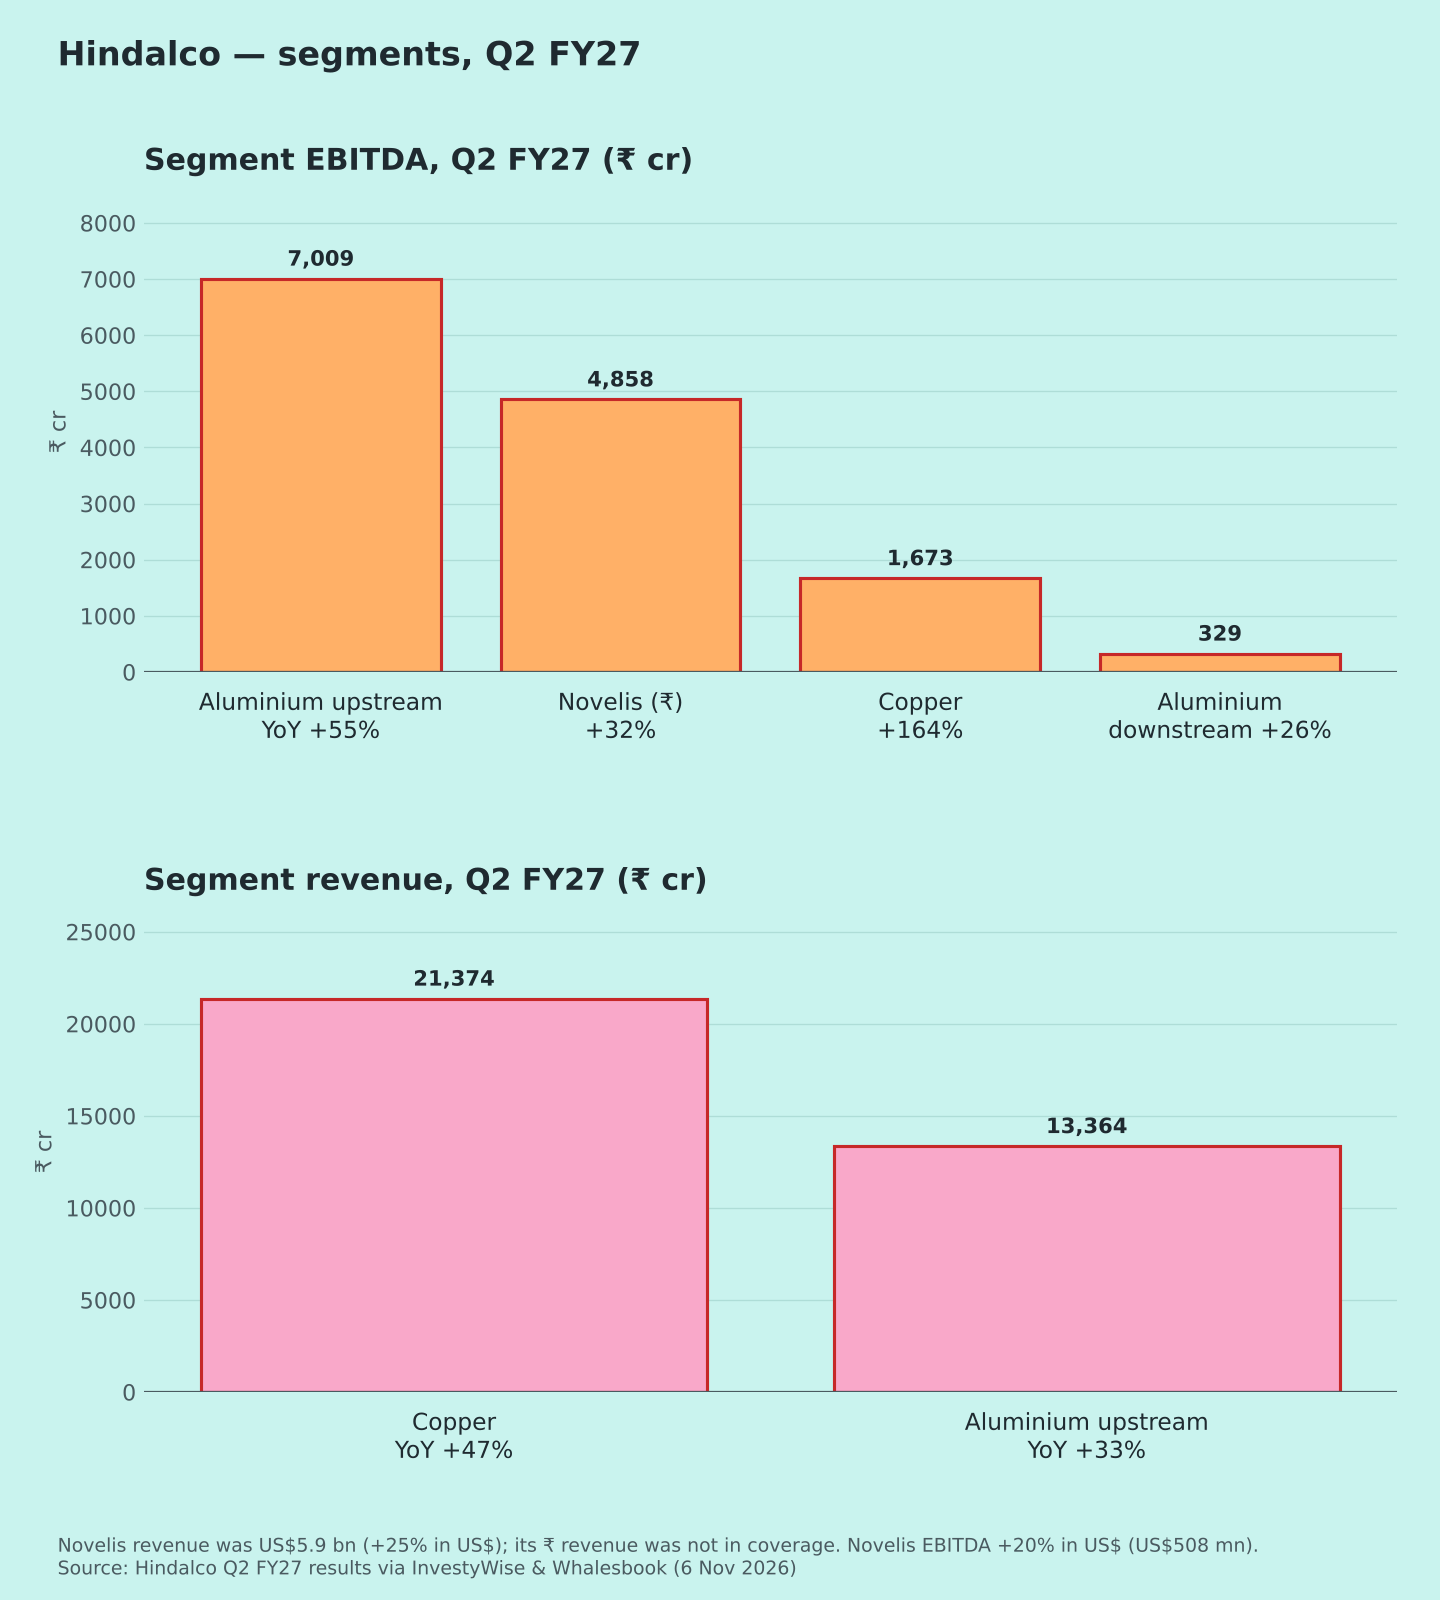
The jump is operational: EBITDA rose 42% on revenue up 39% [1]. Copper EBITDA rose 164% and aluminium upstream EBITDA 55% [1].
Part of the revenue growth is likely metal-price pass-through. Copper revenue was +47% and upstream +33%, and Q2 volumes were not in coverage (my view).
Screener shows negative other income in the last three quarters, against +₹532 cr in Q2 FY26 [5]. Q2 FY27's other income, tax and exceptional items aren't out yet, so I can't separate one-offs. QoQ (+7.4%) is the cleaner read.
Margins (Chart 3)
PAT margin: 7.2% → 3.1% → 3.3% → 8.3% → 8.2% (my calculation). It has held near Q1's level. EBITDA history on the company's definition wasn't in coverage, so it isn't charted.
Segments (Chart 4)
- Novelis: revenue US$5.9 bn (+25%); adjusted EBITDA US$508 mn (+20%), or ₹4,858 cr (+32%). The Oswego hot mill is back to normal.
- Aluminium upstream: EBITDA ₹7,009 cr (+55%), margin ~52%.
- Aluminium downstream: EBITDA ₹329 cr (+26%).
- Copper: EBITDA ₹1,673 cr (+164%) on revenue of ₹21,374 cr (+47%).
Outlook and projects (per coverage)
- Bay Minette (US) commercial shipments are expected by Q1 FY28.
- Aditya smelter phase 2 metal production is expected in FY28.
- 173 MW of renewables were commissioned in Q2, taking the total to 643 MW [2].
I found no change versus earlier timelines in coverage. MD Satish Pai called it the "strongest-ever quarterly performance" [1].
Positives
- All four segments grew EBITDA [1]
- Novelis recovering [1]
Concerns
- Net debt/EBITDA rose to 1.80x from 1.23x as capex continues [2]
- Profits are tied to metal prices (my view)
Things to track in Q3 FY27
- Novelis EBITDA per tonne and Bay Minette progress
- Copper margins after this quarter's jump
- Net debt and capex
- Other income and one-offs once the full filing is covered
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] InvestyWise – Hindalco record Q2 FY27 · [2] InvestyWise – revenue, net debt · [3] Whalesbook – Q2 profit · [4] TaxGuru – results summary · [5] Screener.in – consolidated · [6] Upstox – results live blog · [7] 10bmnews
Charts: (1) 5 quarters revenue & PAT with EPS [1][5]; (2) FY23–FY26 [5]; (3) PAT margin [1][5]; (4) headline [1][5][6]; (5) segments [1][2][3].