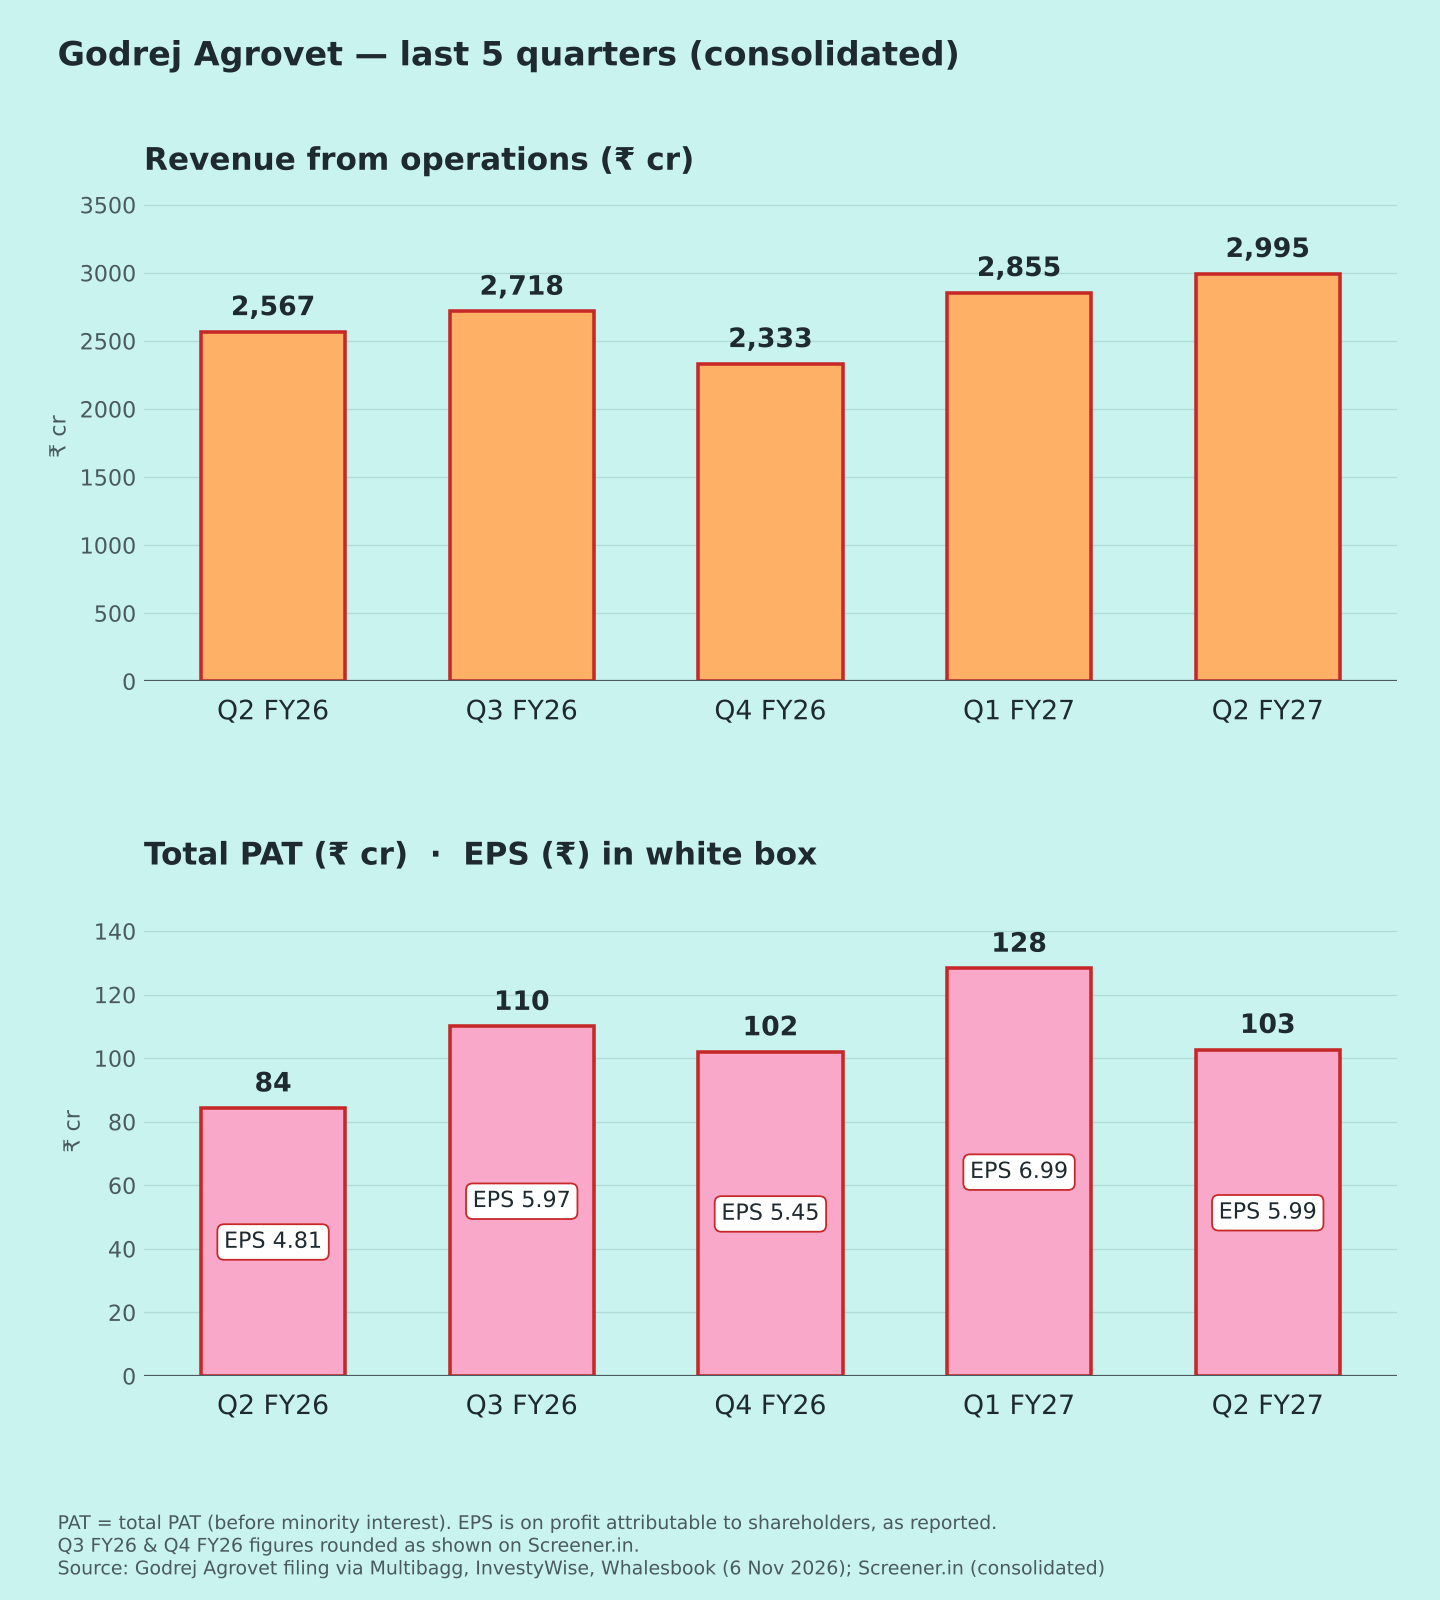
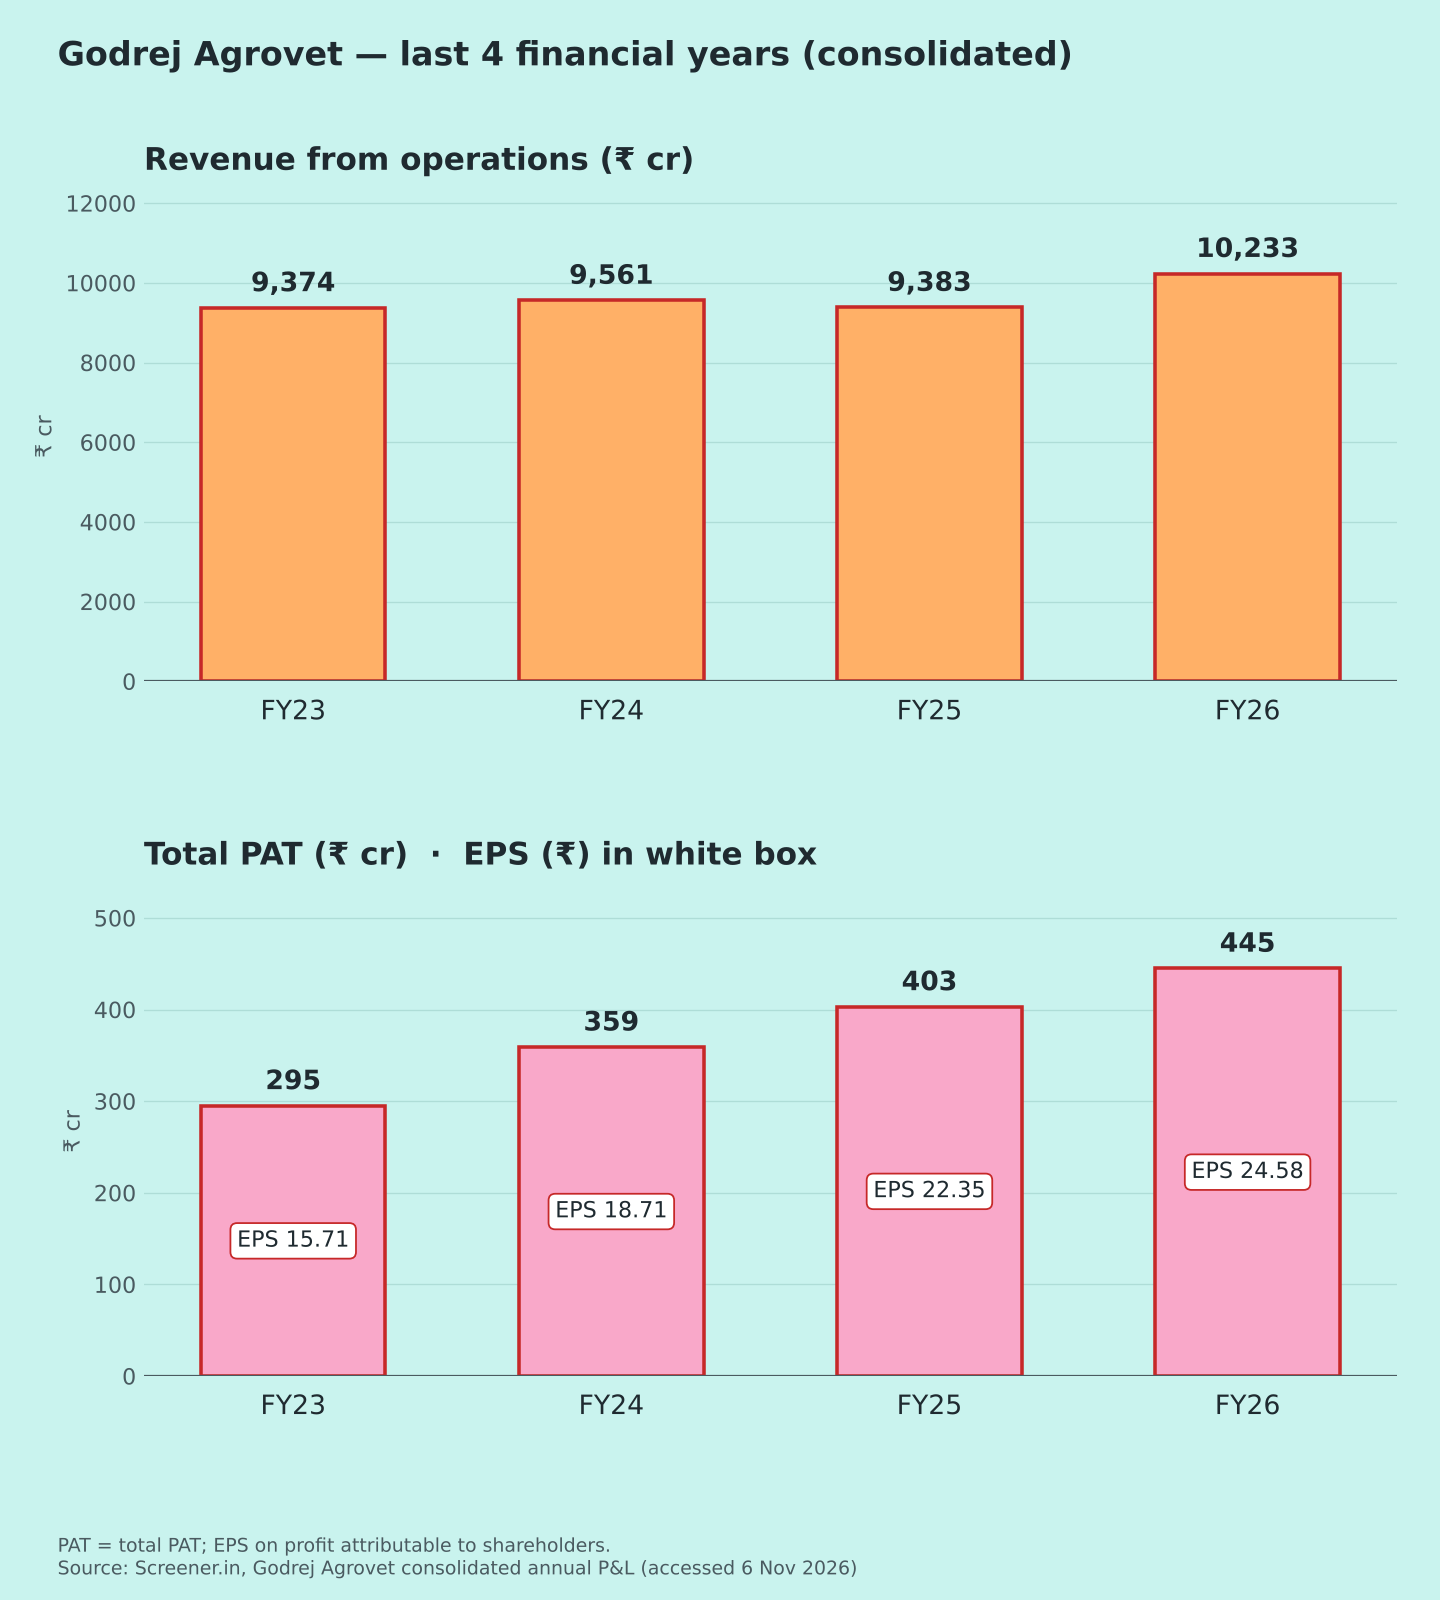
Consolidated figures, ₹ crore unless stated. Results approved by the board on 6 Nov 2026. PAT = total PAT (before minority interest); EPS is on PAT attributable to shareholders, as reported.
The company's EBITDA includes other income. YoY/QoQ % and margins are my calculations unless stated.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 2,995.0 | +16.7% | +4.9% |
| EBITDA (company, incl. other income) | 222 | +0.5% | −14.3% |
| EBITDA margin (company) | 7.4% | 8.6% | 9.1% |
| PBT (incl. JV share) | 143.2 | +6.1% | −20.9% |
| Total PAT | 102.8 | +21.8% | −19.9% |
| PAT attributable to shareholders | 115.2 | +24.4% | −14.3% |
| PAT margin (total PAT) | 3.4% | 3.3% | 4.5% |
| EPS (₹) | 5.99 | +24.5% | −14.3% |
| Other income / PBT | 15.2% | 5.8% | 8.2% |
Margin and ratio rows show the year-ago and last-quarter values, not % change. Q1 EBITDA (₹259 cr, 9.1%) is from the Q1 presentation [10].
Quality of earnings
PAT growth (+22%) came from below the operating line:
- Other income nearly tripled to ₹21.8 cr from ₹7.8 cr [1]. Excluding it, PBT fell ~5% (my calculation).
- Lower tax rate: ~28% vs ~38% a year ago (my calculation from [1][7]). The high-tax base quarter flatters YoY.
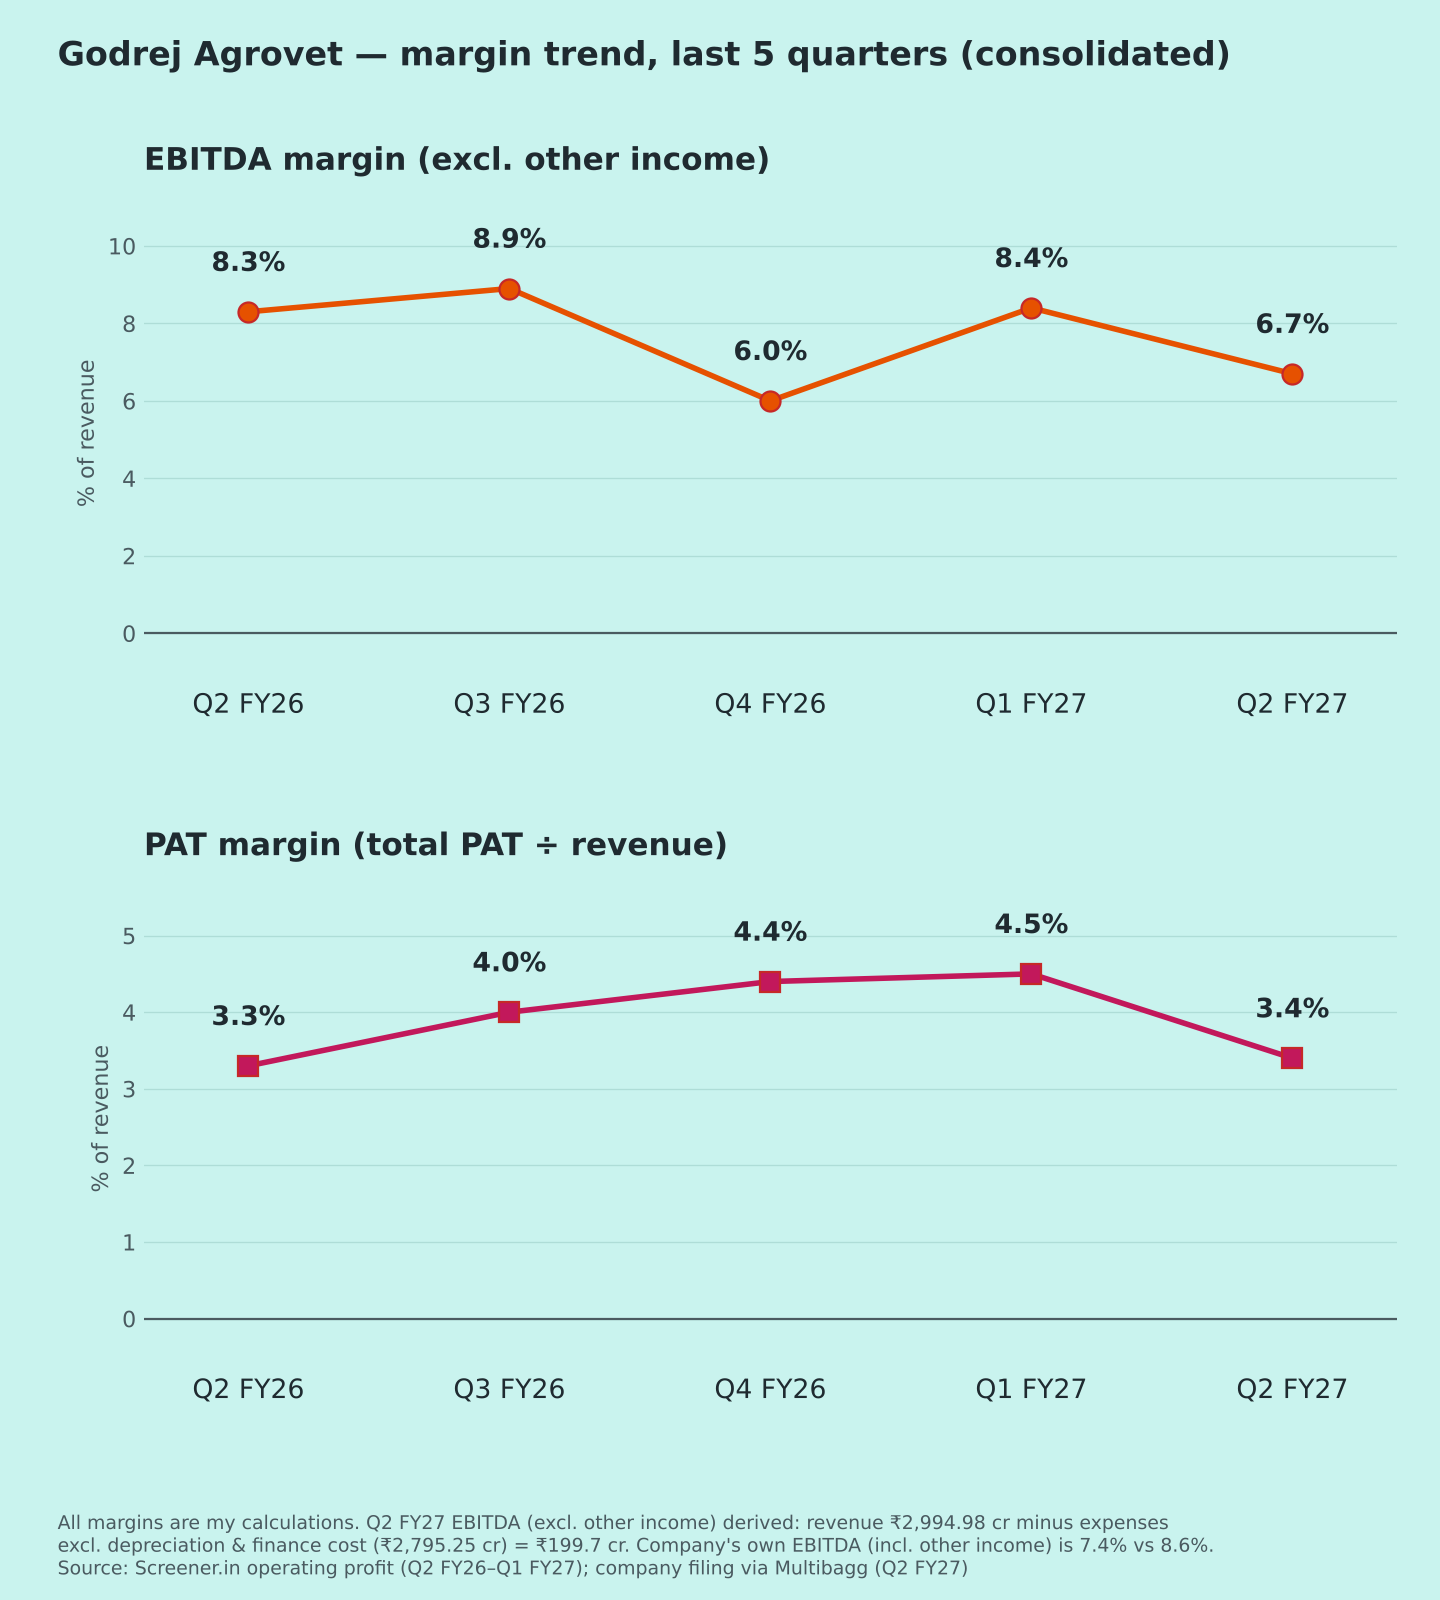
- Core EBITDA fell: Excluding other income, EBITDA was ~₹200 cr vs ₹213 cr, down ~6% (derived; see Chart 3).
- Minority interest: Attributable PAT is higher than total PAT, so subsidiaries with outside shareholders (e.g., Astec, 67% owned) made losses [2][3].
Revenue growth is largely price-led commodity pass-through: vegetable-oil revenue +26% with CPO realisation +23% [11]; feed volumes +3% with realisation +11% [12]. QoQ is the fairer read on profit.
Margins (Chart 3)
EBITDA margin, excluding other income: 8.3% → 8.9% → 6.0% → 8.4% → 6.7% [9]. Management blamed input-cost inflation (milk, packaging, feed), a monsoon ~13% short and El Niño [3][6].
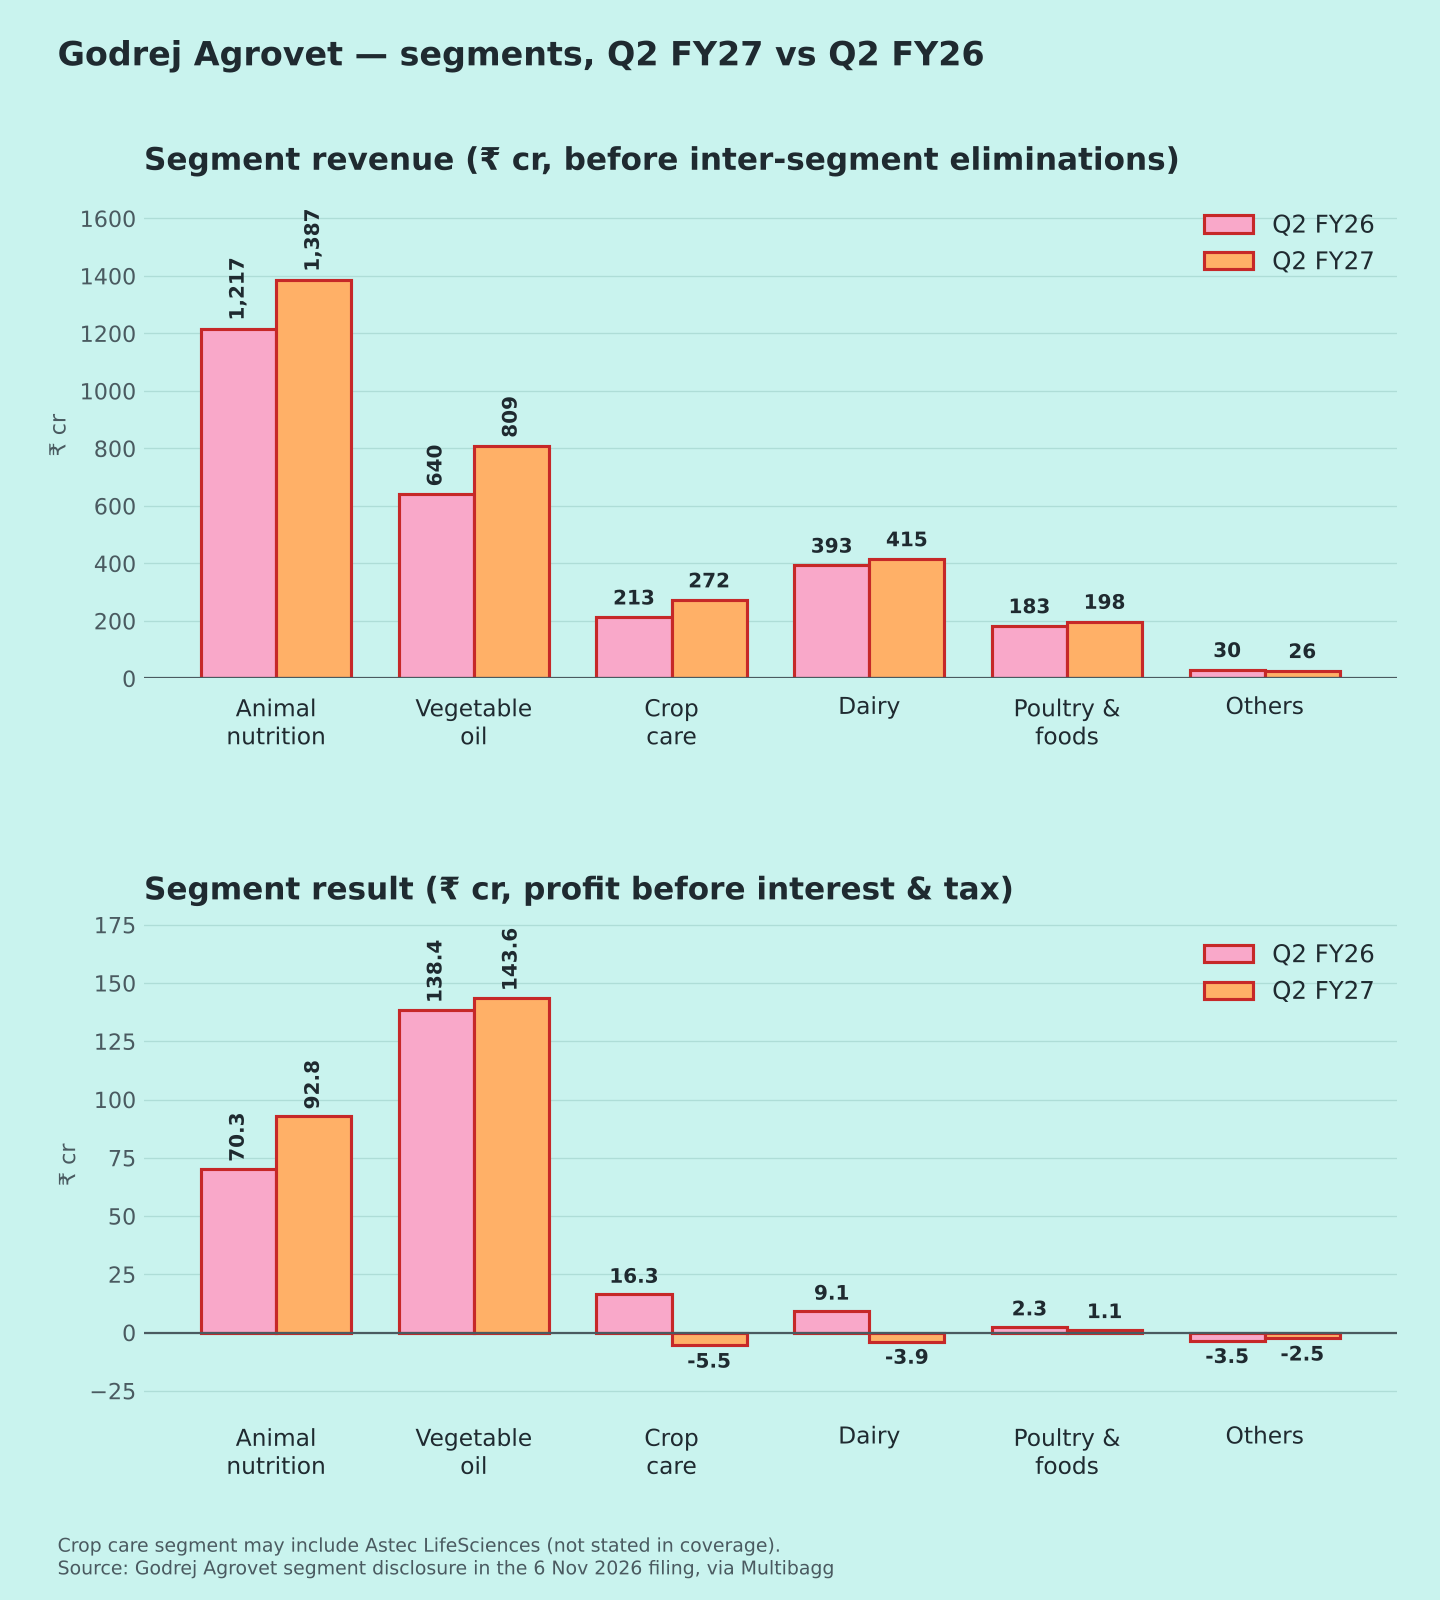
Segments (Chart 5) [4]
- Animal nutrition: revenue +14%; result ₹92.8 cr vs ₹70.3 cr. EBIT per tonne was ₹2,254 [12], above the guided ₹2,050–2,200 [10].
- Vegetable oil: revenue +26%; result only +4%. Oil extraction was lower in dry weather [11].
- Crop care: swung to a loss of ₹5.6 cr from a ₹16.3 cr profit.
- Dairy (Creamline): loss of ₹3.9 cr vs a ₹9.1 cr profit.
- Poultry & foods result fell to ₹1.2 cr from ₹2.3 cr. Others narrowed its loss to ₹2.5 cr.
Guidance check (Q1, Aug 2026 [10])
- FY27 growth: "Double-digit" growth was guided. H1 revenue is +12.9% (₹5,850 cr vs ₹5,182 cr) [2].
- Astec: Over 20% growth was guided. Q2 revenue fell 3% [3].
- Updated view promised by end-Q2: None in coverage yet; crop care H2 called "muted" [3].
Cash and debt: H1 operating cash flow was −₹142 cr vs +₹332 cr last year. Inventory rose to ₹1,826 cr from ₹1,358 cr in March [5]. Total borrowings rose ~₹232 cr to ~₹1,701 cr (my calculation from [5]).
Positives
- Animal nutrition profit +32%, EBIT/tonne above guidance [4][12]
Concerns
- PAT growth relies on other income and tax (my view)
- Crop care and dairy in losses [4]
- Working-capital build-up and higher debt [5]
Things to track in Q3 FY27
- Crop care recovery in the rabi season
- Milk costs and dairy margins
- Inventory and borrowings
- Revised FY27 guidance
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Multibagg – Q2 FY27 results · [2] Multibagg – owner profit & H1 · [3] Multibagg – presentation: margins, businesses · [4] Multibagg – segment table · [5] Multibagg – cash flow & borrowings · [6] InvestyWise – results & CEO comment · [7] Whalesbook – Q2 net profit · [8] Sahi – Q2 profit · [9] Screener.in – consolidated · [10] Investing.com – Q1 FY27 slides & guidance · [11] Multibagg – oil palm · [12] Multibagg – animal nutrition
Charts:
(1) last 5 quarters revenue & PAT with EPS
(2) FY23–FY26 revenue & PAT with EPS [9];
(3) EBITDA & PAT margin [1][9]; (4) headline Q2 FY26 / Q1 FY27 / Q2 FY27 [
(4) segment revenue & results [4].