Gillette India Ltd (GILLETTE): Q2 FY27 results
Gillette India (GILLETTE) 1 reply Share on X Share on WhatsApp

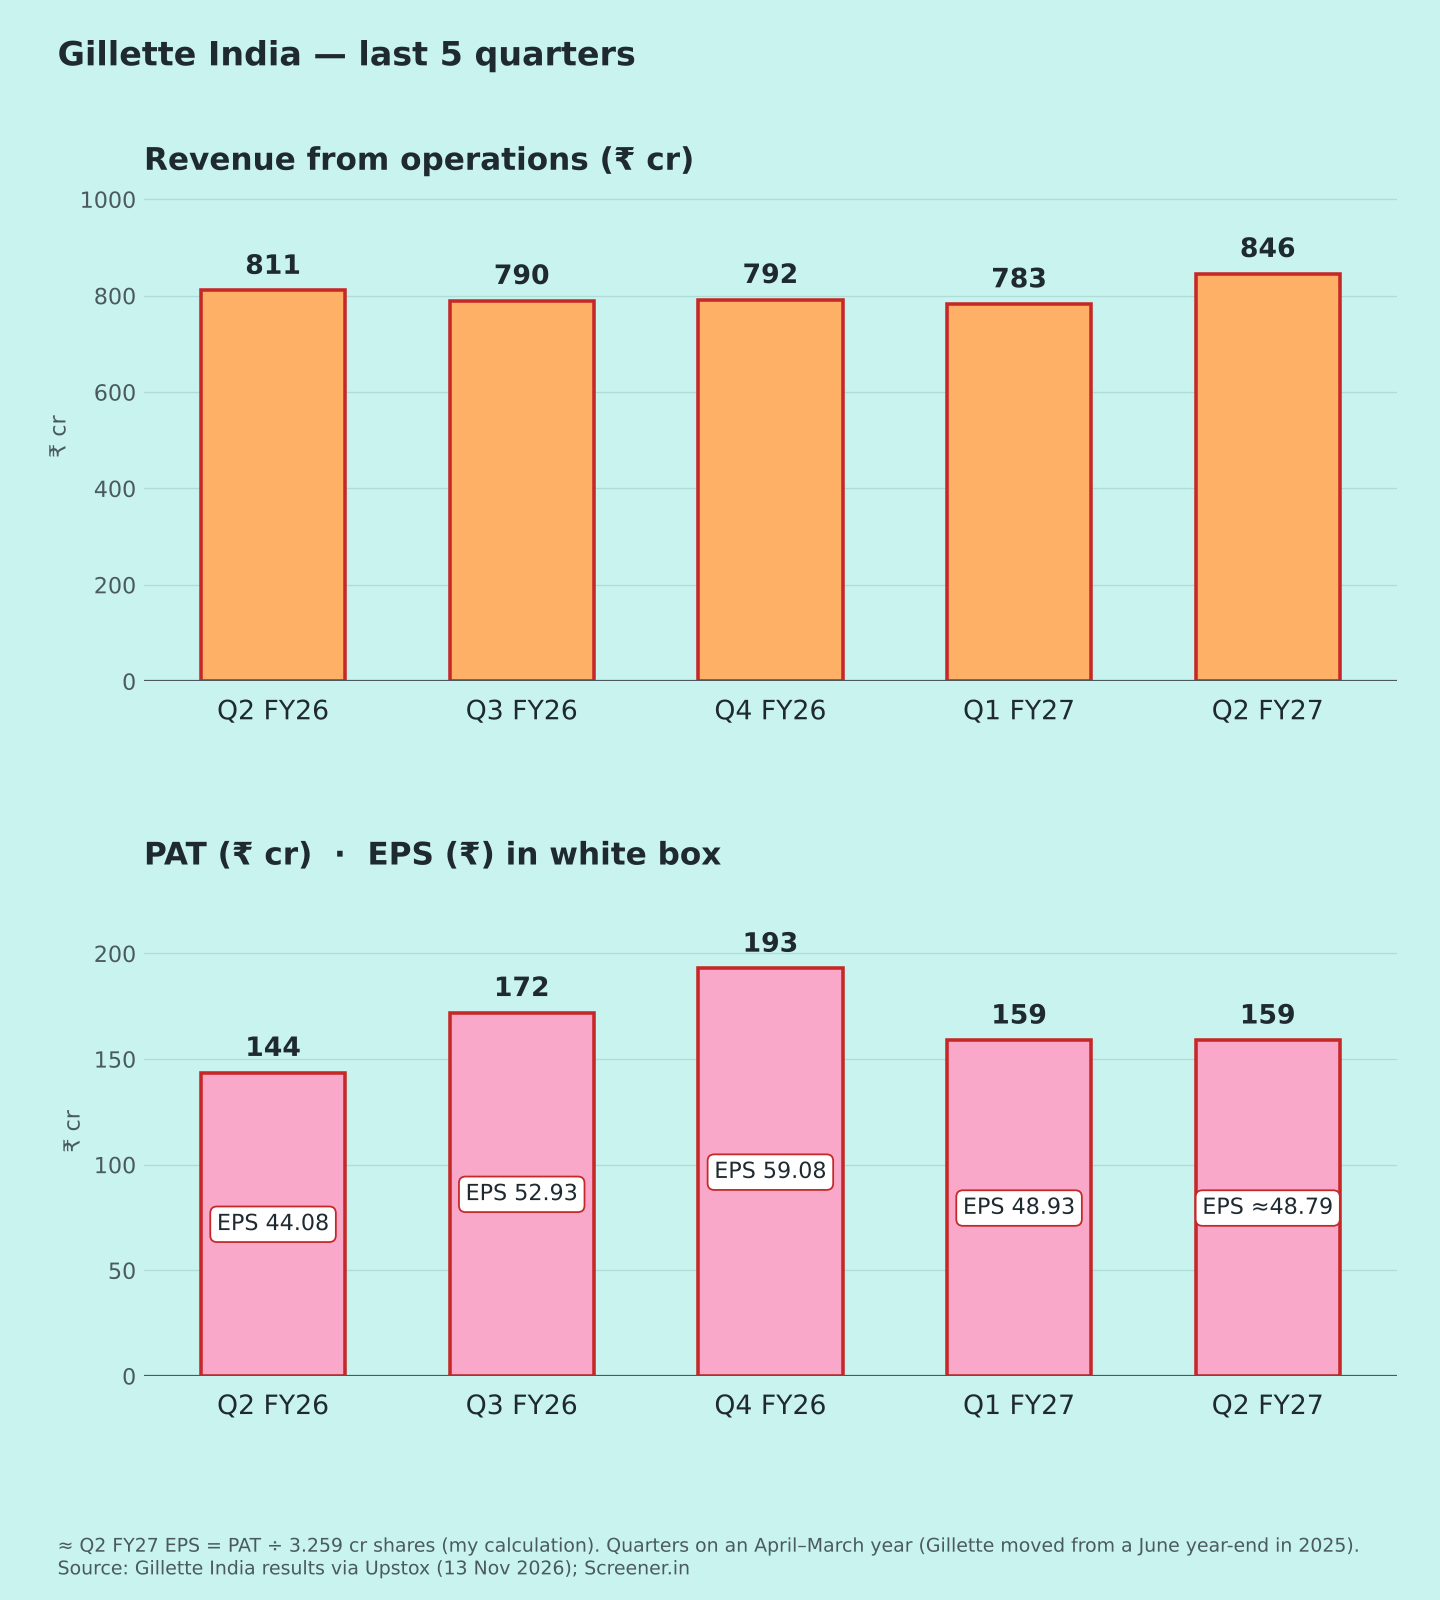
Quality of earnings
- Profit grew faster than sales. Revenue +4%, EBITDA +9%, PAT +11%. Margins improved YoY even though the company mentioned commodity headwinds (my view: price increases or cost savings may explain it).
- Sales growth is slow at 4% YoY. H1 revenue grew 7% to ₹1,629 cr; H1 PAT ₹319 cr vs ₹289 cr.
- Oral care: the power oral-care business (electric toothbrushes) grew double digits and launched Oral-B iO2 [1]. No segment numbers given.
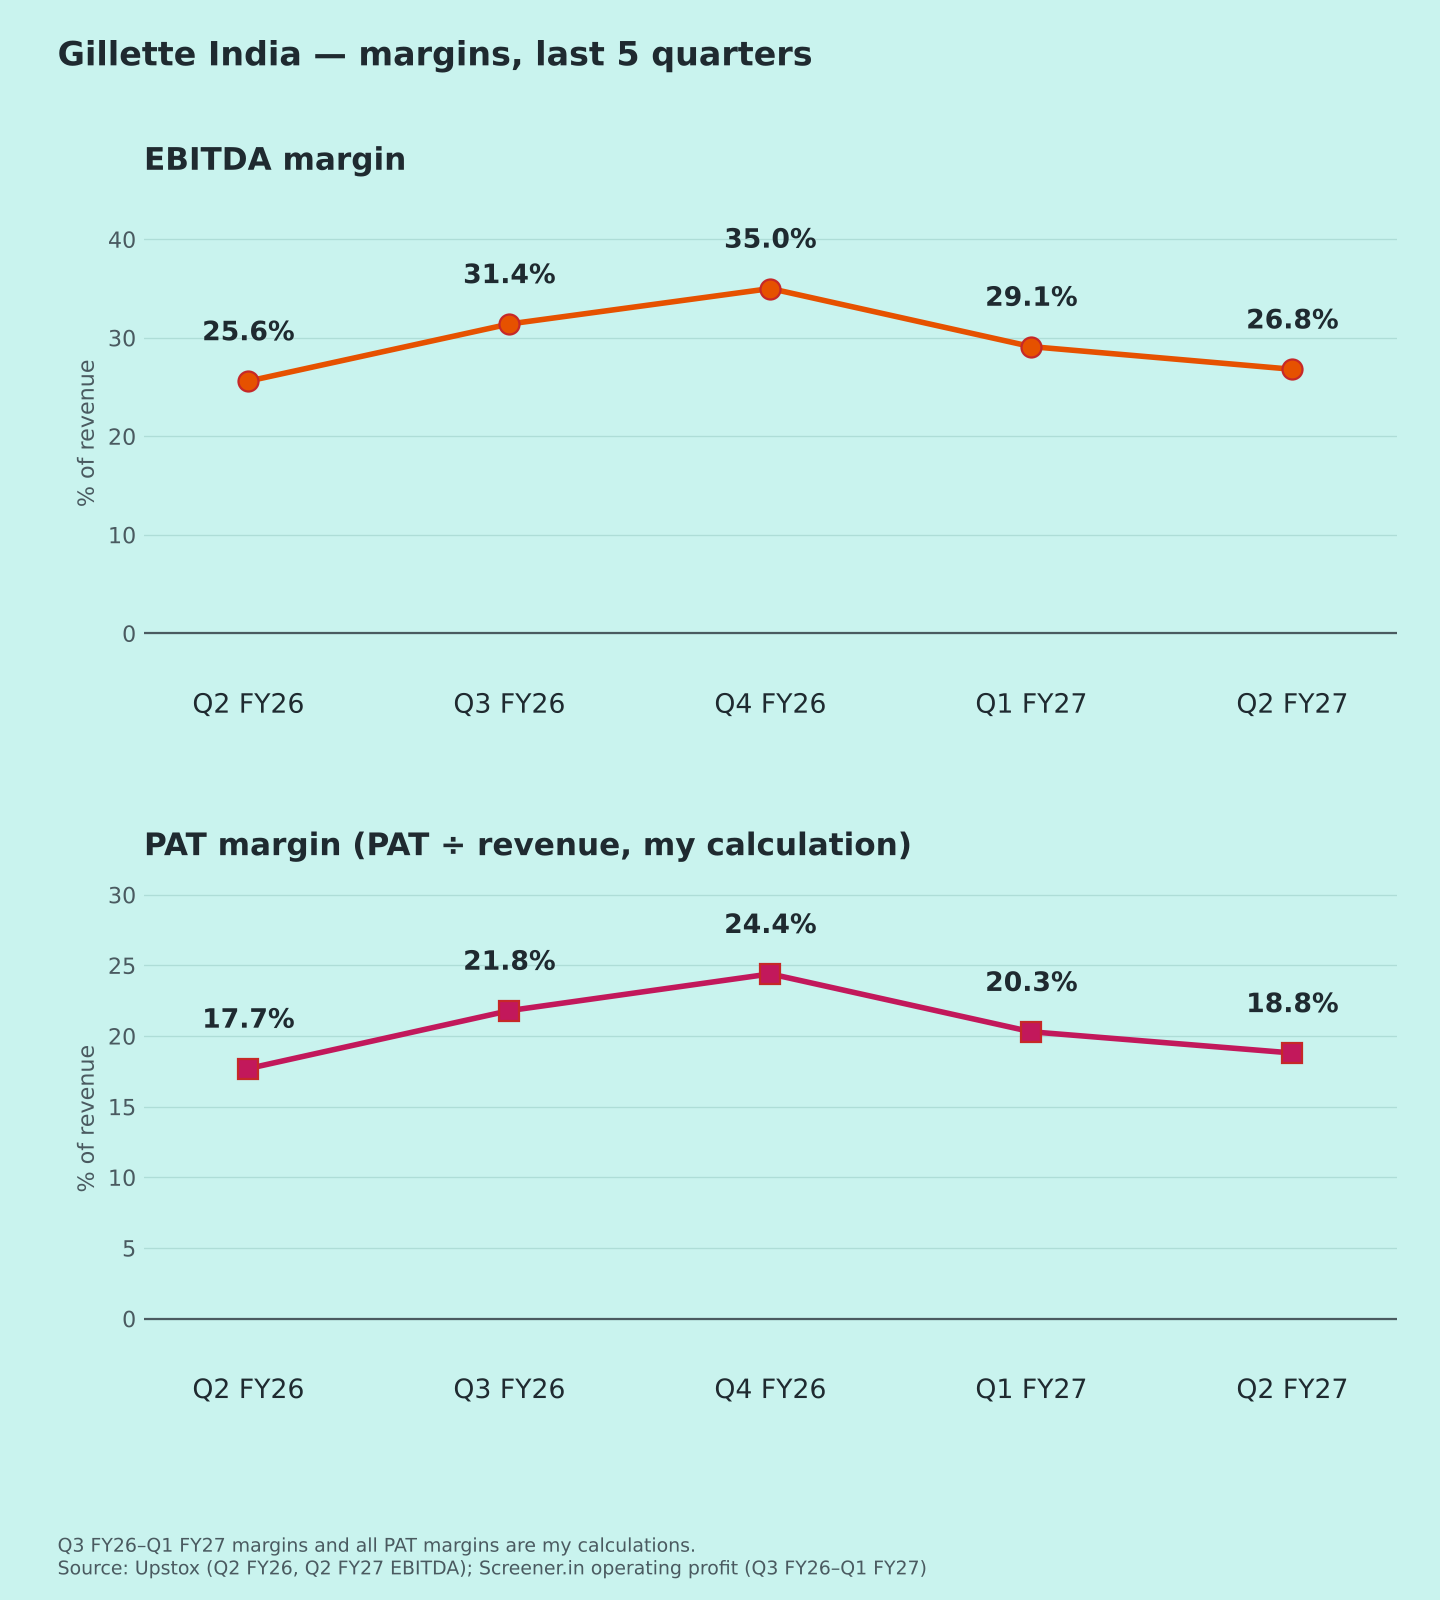
- QoQ: margin was lower than Q1's 29.1%.
Margins (Chart 3)
EBITDA margin: 25.6% → 31.4% → 35.0% → 29.1% → 26.8% [1][3]. Below the H2 FY26 peak.
No dividend in coverage.
Positives
- EBITDA +9%, PAT +11%
- Margin up YoY
Concerns
- Revenue growth only 4%
- Margin down from Q1 and the FY26 peak
Things to track in Q3 FY27
- Sales growth
- EBITDA margin vs ~27%
- Grooming vs oral care split
- Commodity cost pressure
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Posts are members’ own views and are not investment advice. Holdings shown are what each member disclosed when posting. Research notes are by SEBI-registered analysts under their own registration; Mudraa hosts them and does not endorse them.
To take part, Log in or Join. Members verify their email and phone and agree to the community rules.