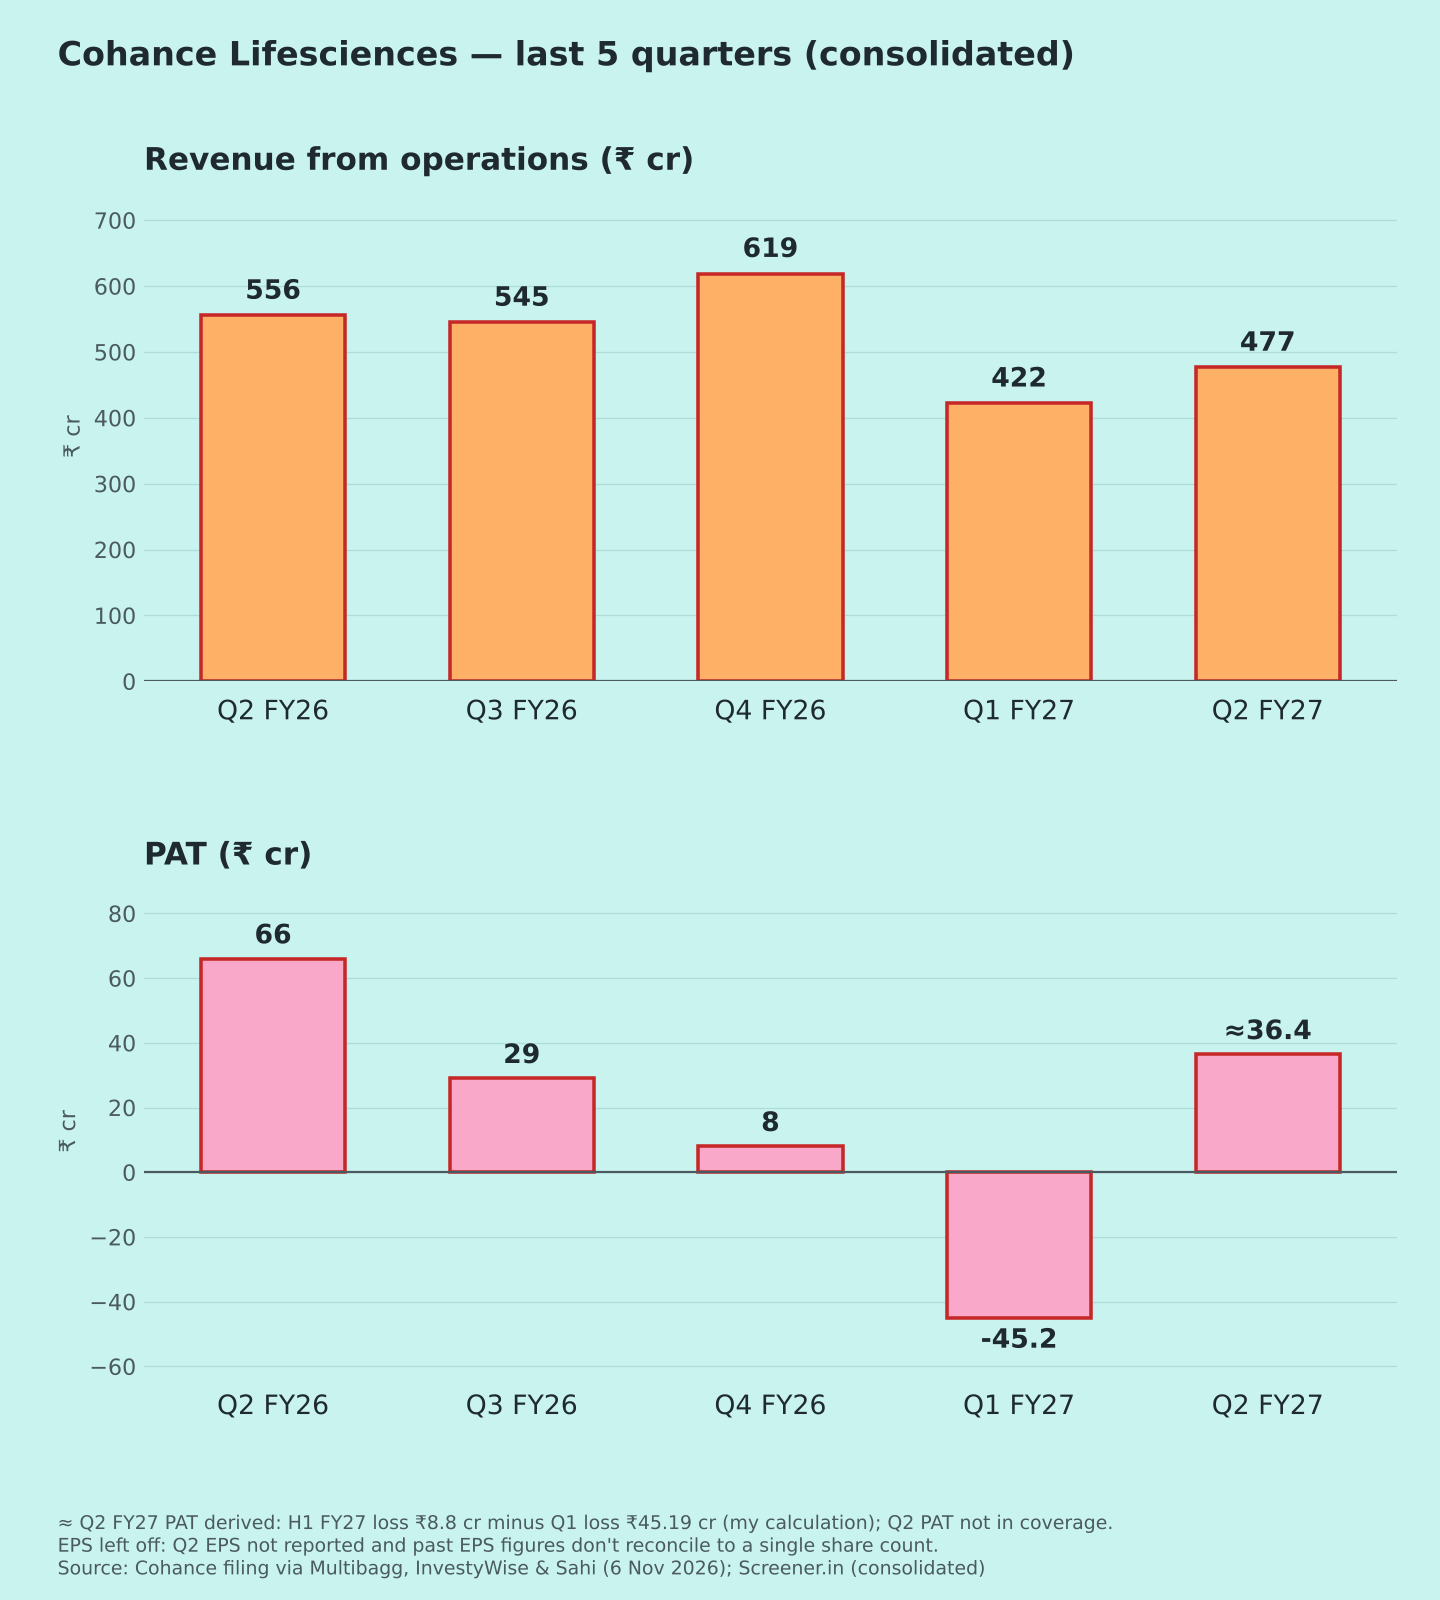
Consolidated figures, ₹ crore. Results are announced today 6 Nov 2026.
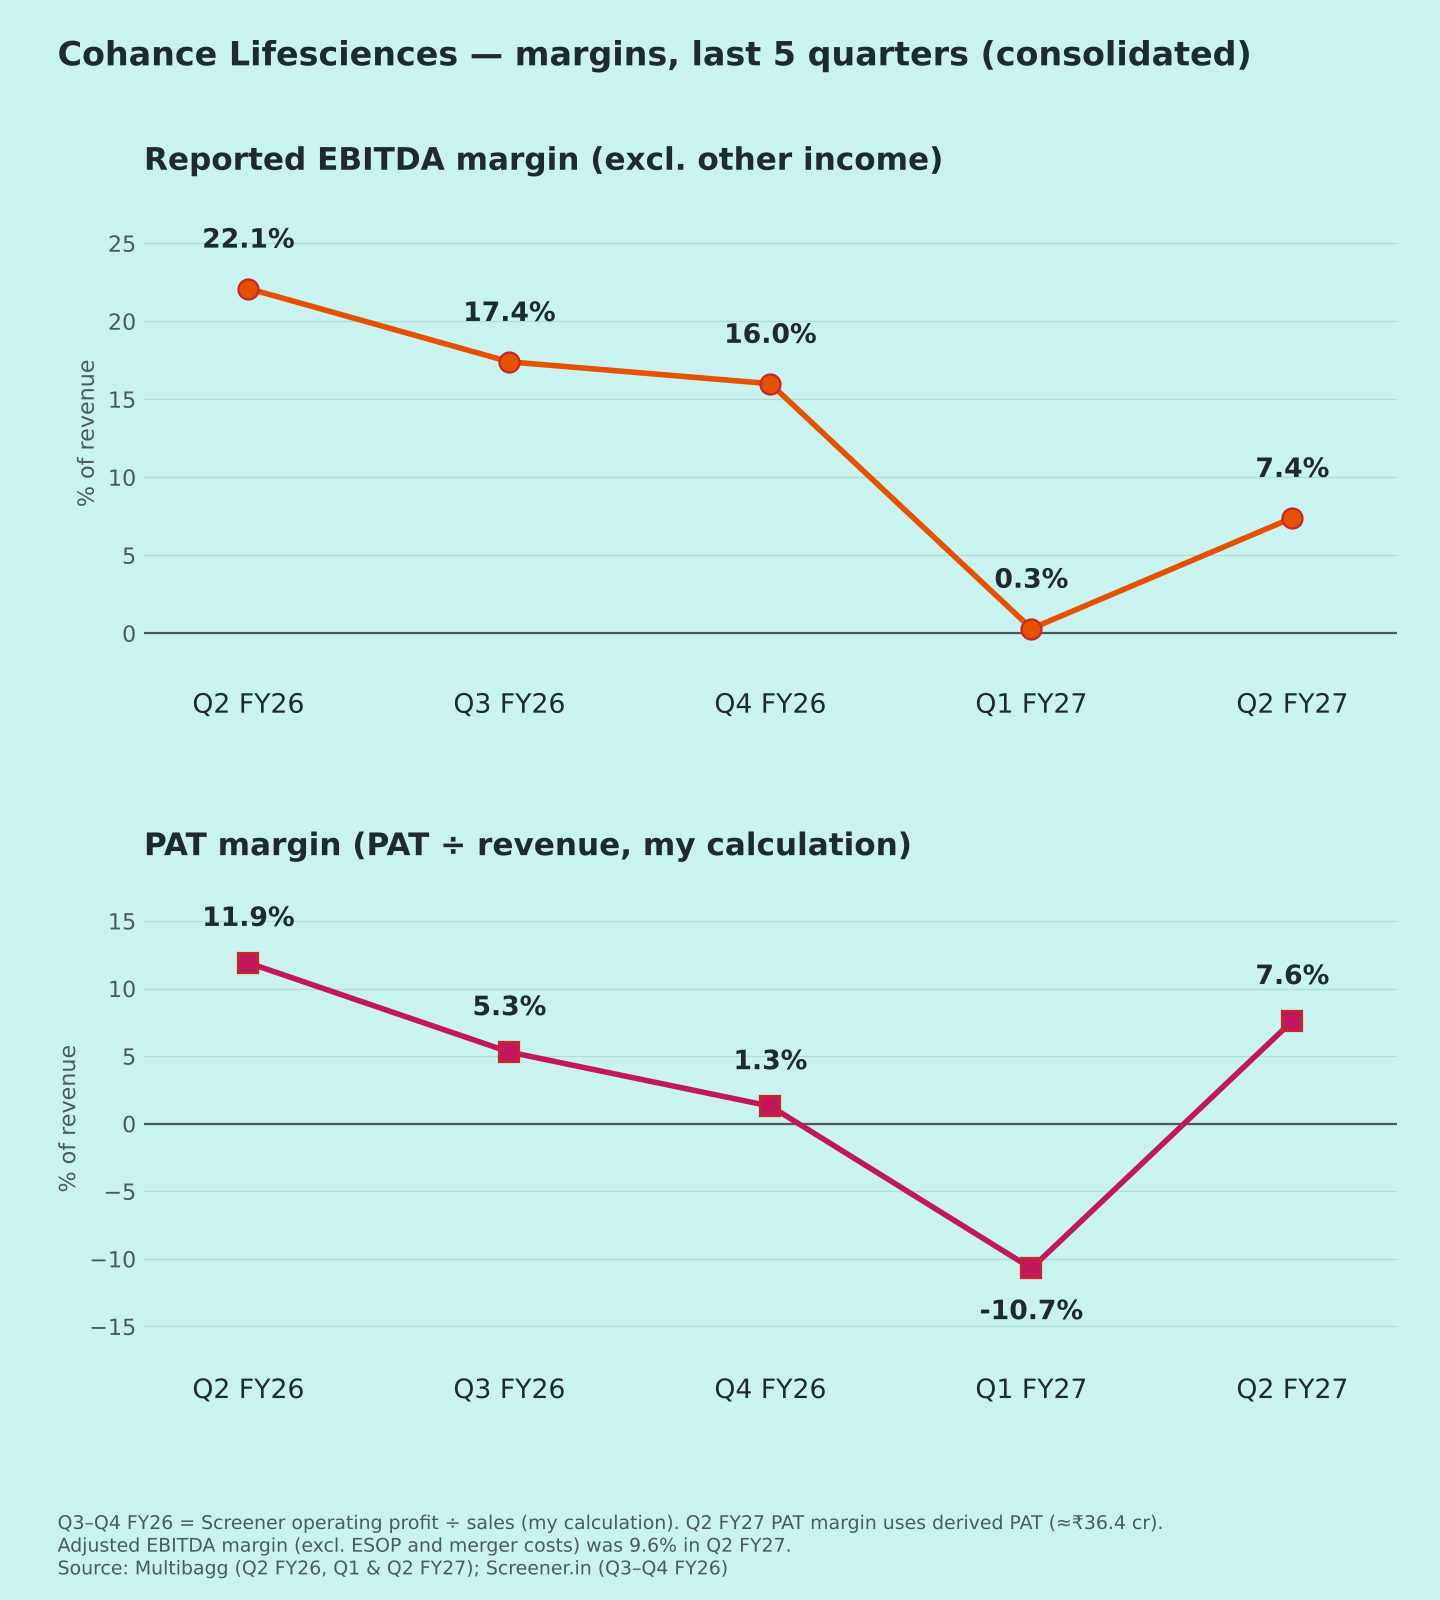
Coverage gives revenue, EBITDA and H1 figures, but not the full Q2 P&L. Q2 PAT is derived (H1 minus Q1), and reported Q2 EPS, depreciation, tax and other income are left out. The company's "adjusted EBITDA" excludes ESOP and merger costs; "reported EBITDA" excludes other income [1].
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 476.6 | −14.2% | +12.9% |
| Reported EBITDA | 35.5 | −71.0% | from ₹1.2 cr |
| Reported EBITDA margin | 7.4% | 22.1% | 0.3% |
| Adjusted EBITDA margin | 9.6% | — | 2.2% |
Margin rows show year-ago and last-quarter values; "—" = not in coverage.
Quality of earnings
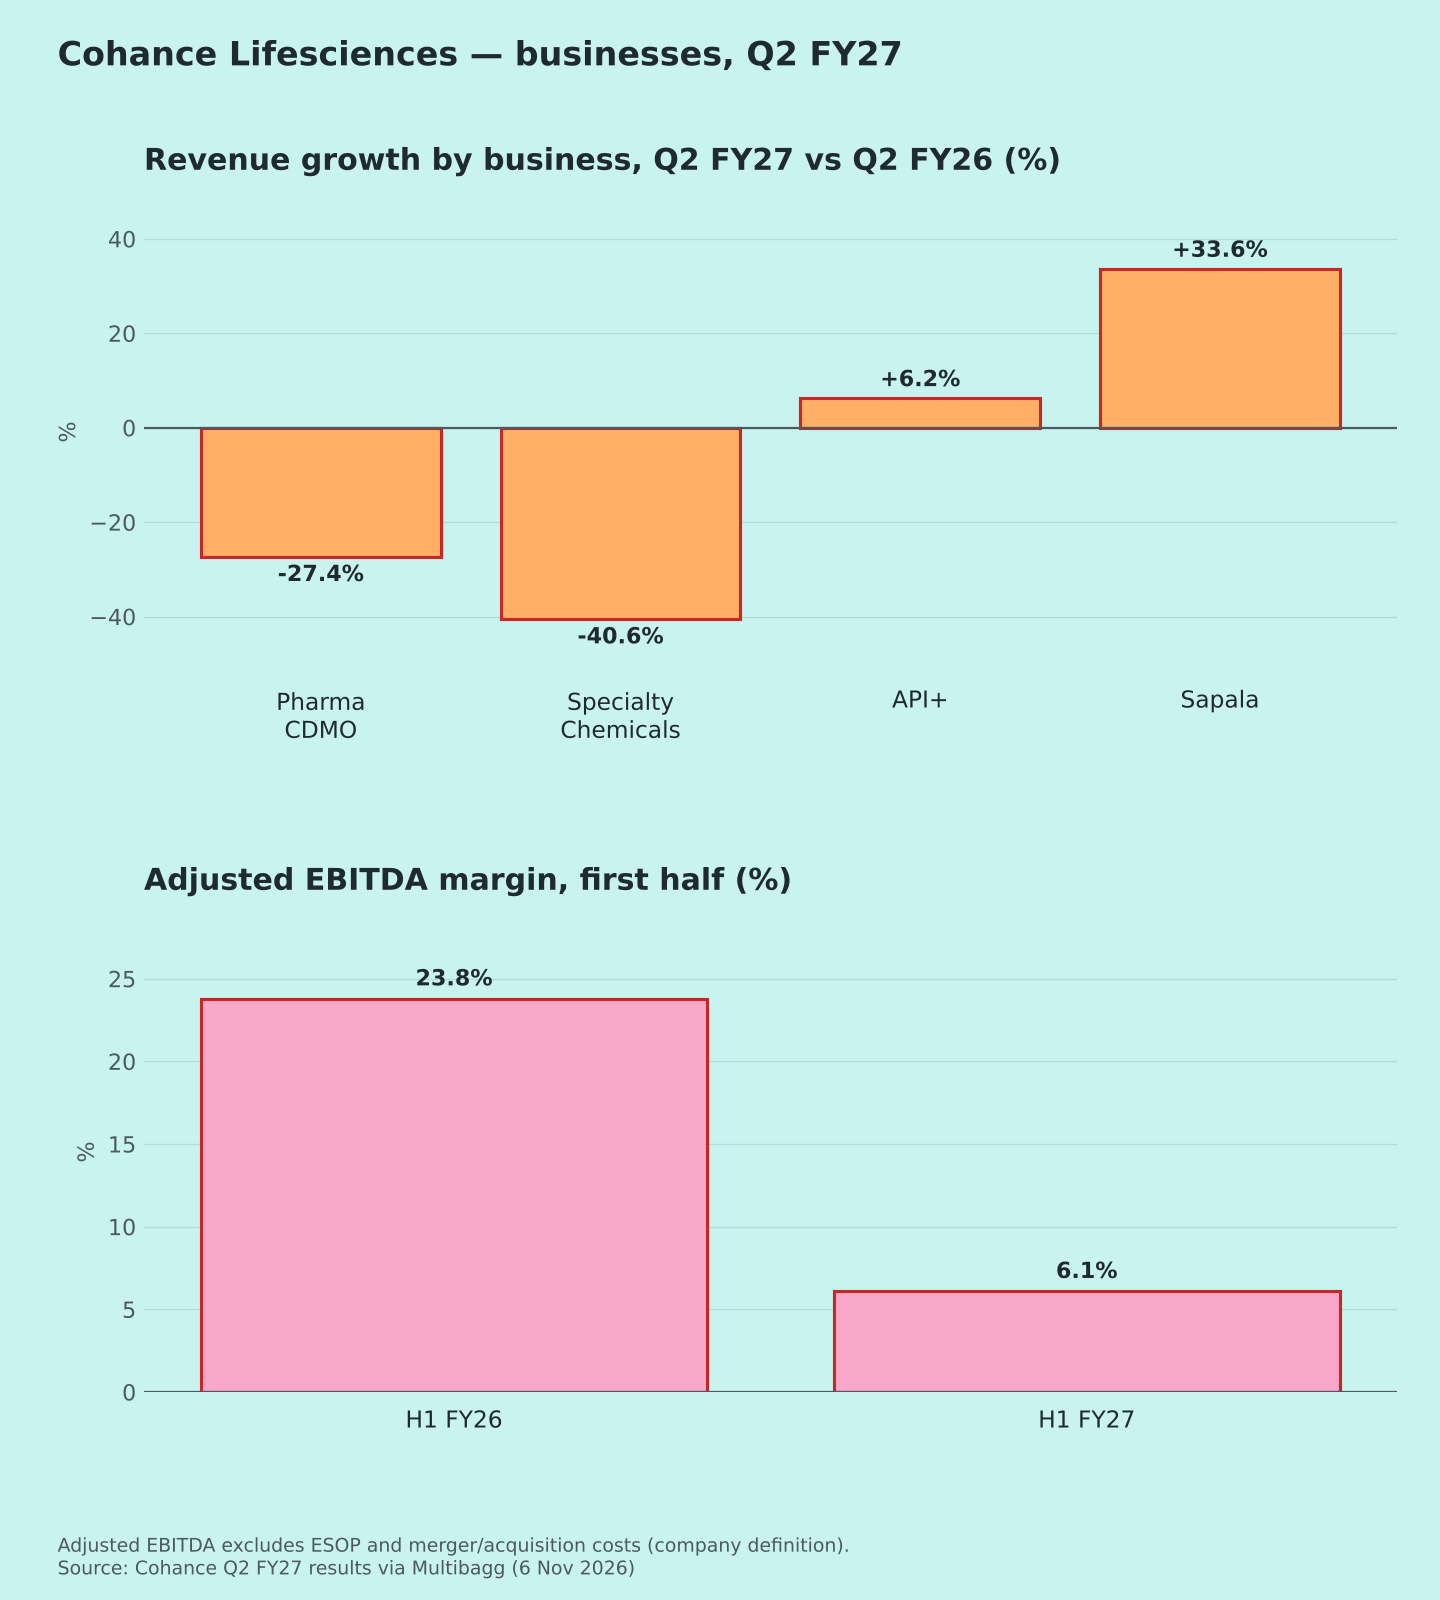
- Revenue fell across the main businesses [1]:Pharma CDMO (contract manufacturing for drug makers): −27.4%
- Specialty Chemicals: −40.6%, on lower agrochemical volumes and pricing pressure
- API+: +6.2%
- Sapala (nucleic-acid building blocks): +33.6%
- Margins collapsed. H1 adjusted EBITDA margin was 6.1% vs 23.8% [1]. Gross margin fell ~3.8 points.
- The Q2 "profit" can't be read yet. The reported-vs-adjusted gap points to a one-off item, still to be confirmed in the filing.
Margins (Chart 3)
Reported EBITDA margin: 22.1% → 17.4% → 16.0% → 0.3% → 7.4% [1][5]. There is some recovery from Q1, but it remains far below last year.
Guidance
Management expects H2 FY27 revenue and EBITDA to grow year on year. It said small-molecule orders for Q3–Q4 "improved materially" and that CDMO results are lumpy [1]. No numbers were given.
Other items
- Screener's announcement list shows a BSE filing that the state pollution board ordered closure of the Suryapet plant after an industrial accident in which an employee died [5]. Please verify the details in the filing.
- The company had net cash of ₹66.6 cr [1].
- Screener flags that promoters have pledged 94.6% of their shares [5].
Positives
- Sapala and API+ growing [1]
- Net cash balance sheet [1]
Concerns
- Core CDMO and chemicals revenue down sharply [1]
- Plant closure order and high promoter pledge [5]
Things to track in Q3 FY27
- Whether H2 growth starts in Q3
- Suryapet plant status
- Adjusted EBITDA margin
- The full Q2 P&L and the one-off item
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Multibagg – H1 revenue, EBITDA & outlook · [2] InvestyWise – board outcome · [3] Sahi – Q2 revenue · [4] Multibagg – Q2 preview · [5] Screener.in – consolidated
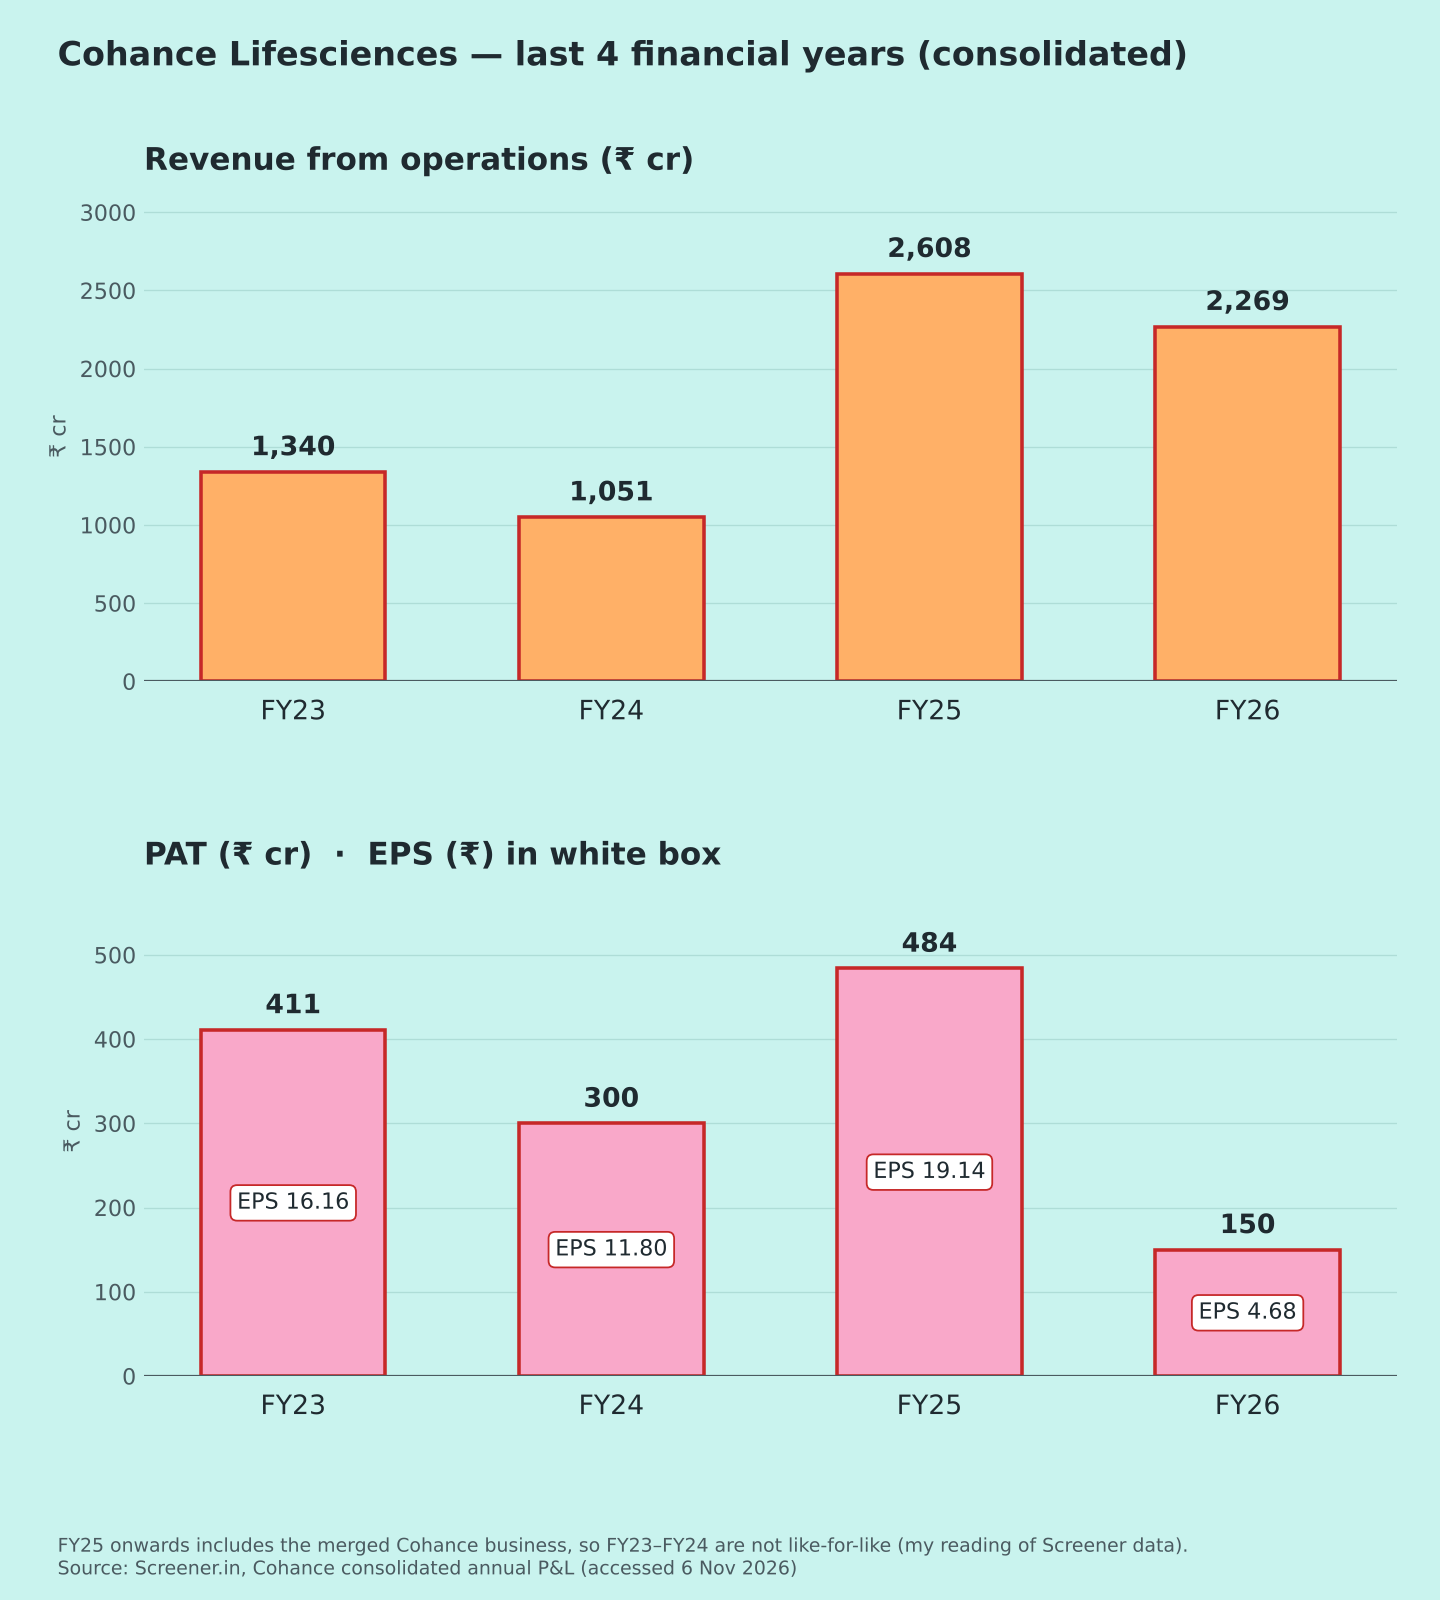
Charts: (1) 5 quarters revenue & PAT [1][5]; (2) FY23–FY26 with EPS [5]; (3) margins [1][5]; (4) headline [1][5]; (5) businesses [1]. EPS is left off the quarterly charts because Q2 EPS wasn't reported.