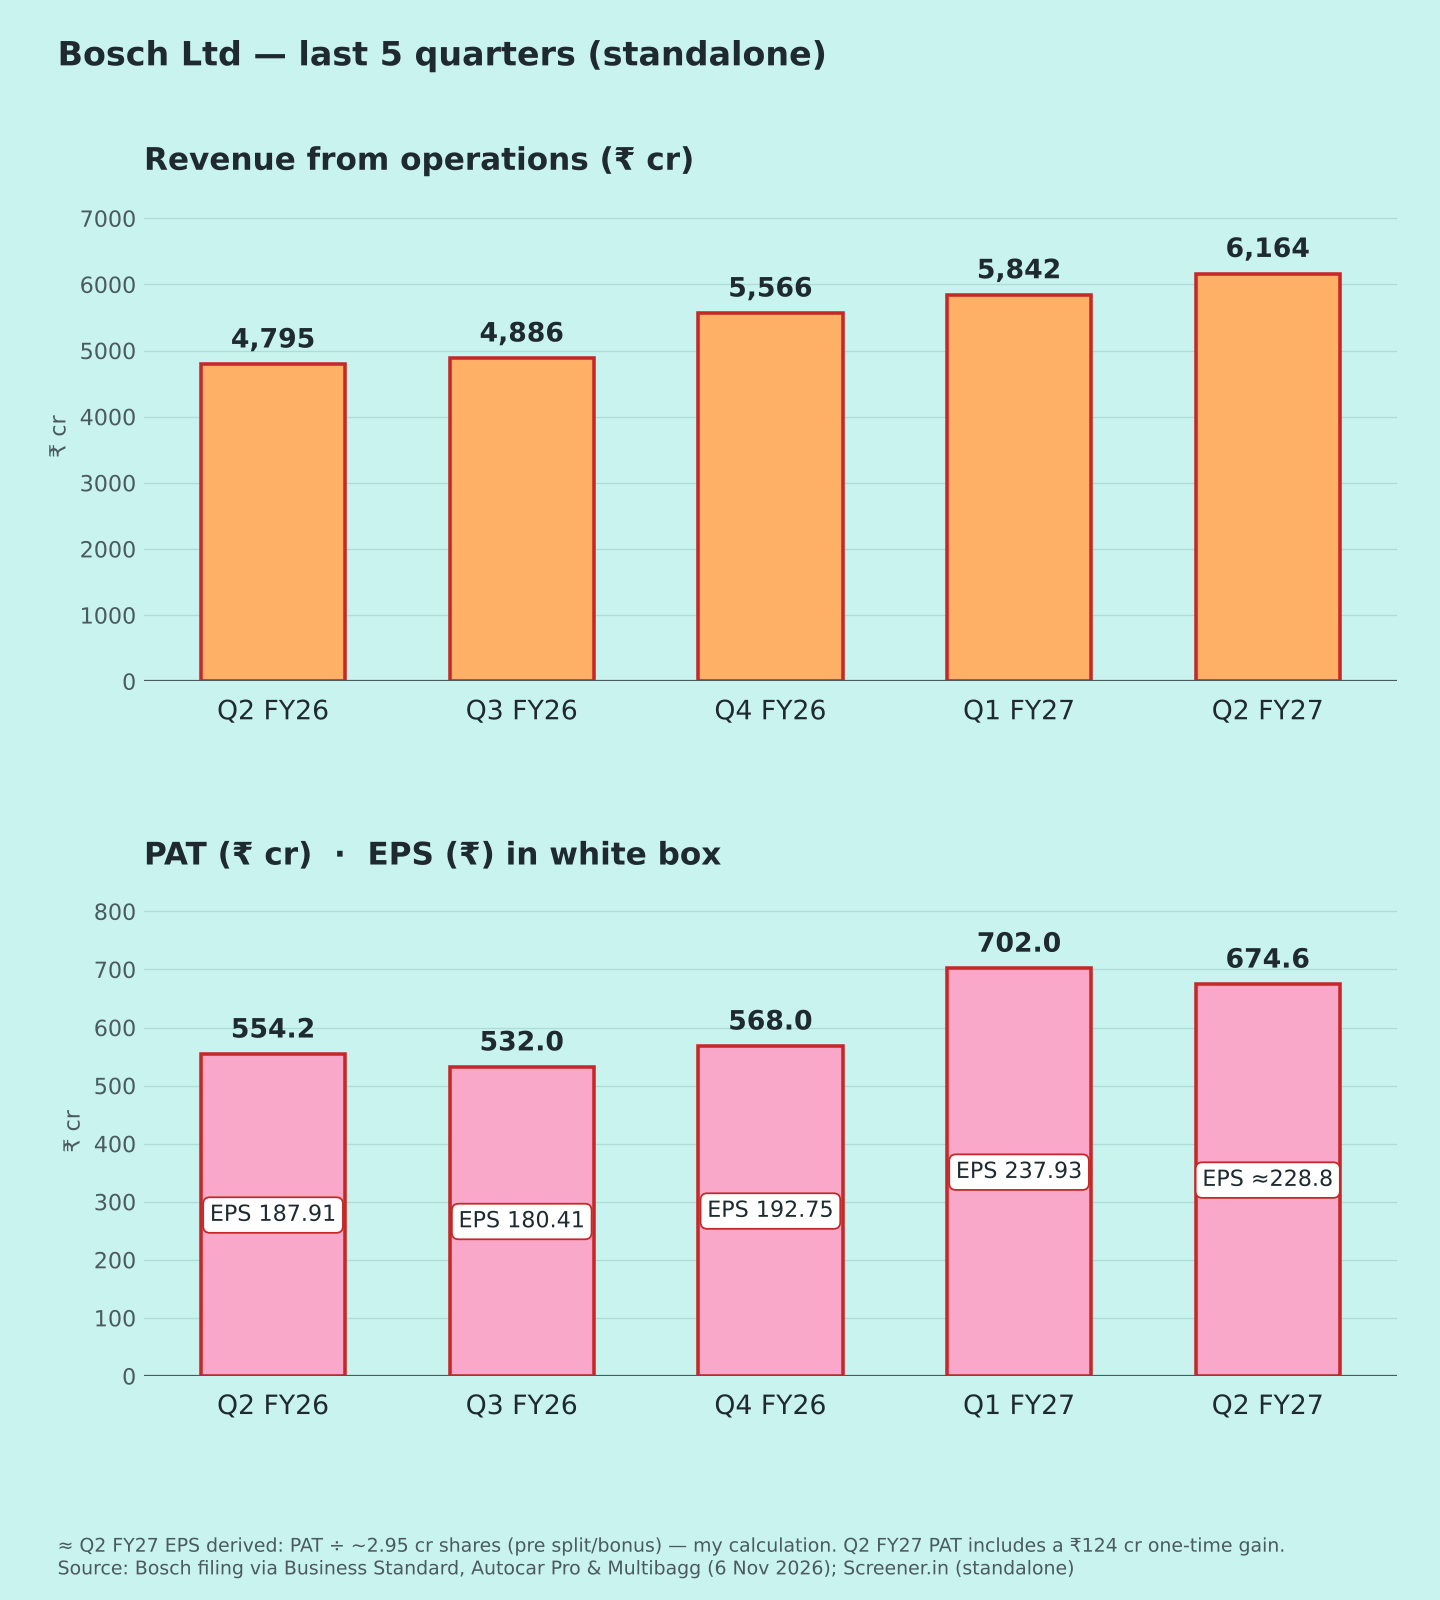
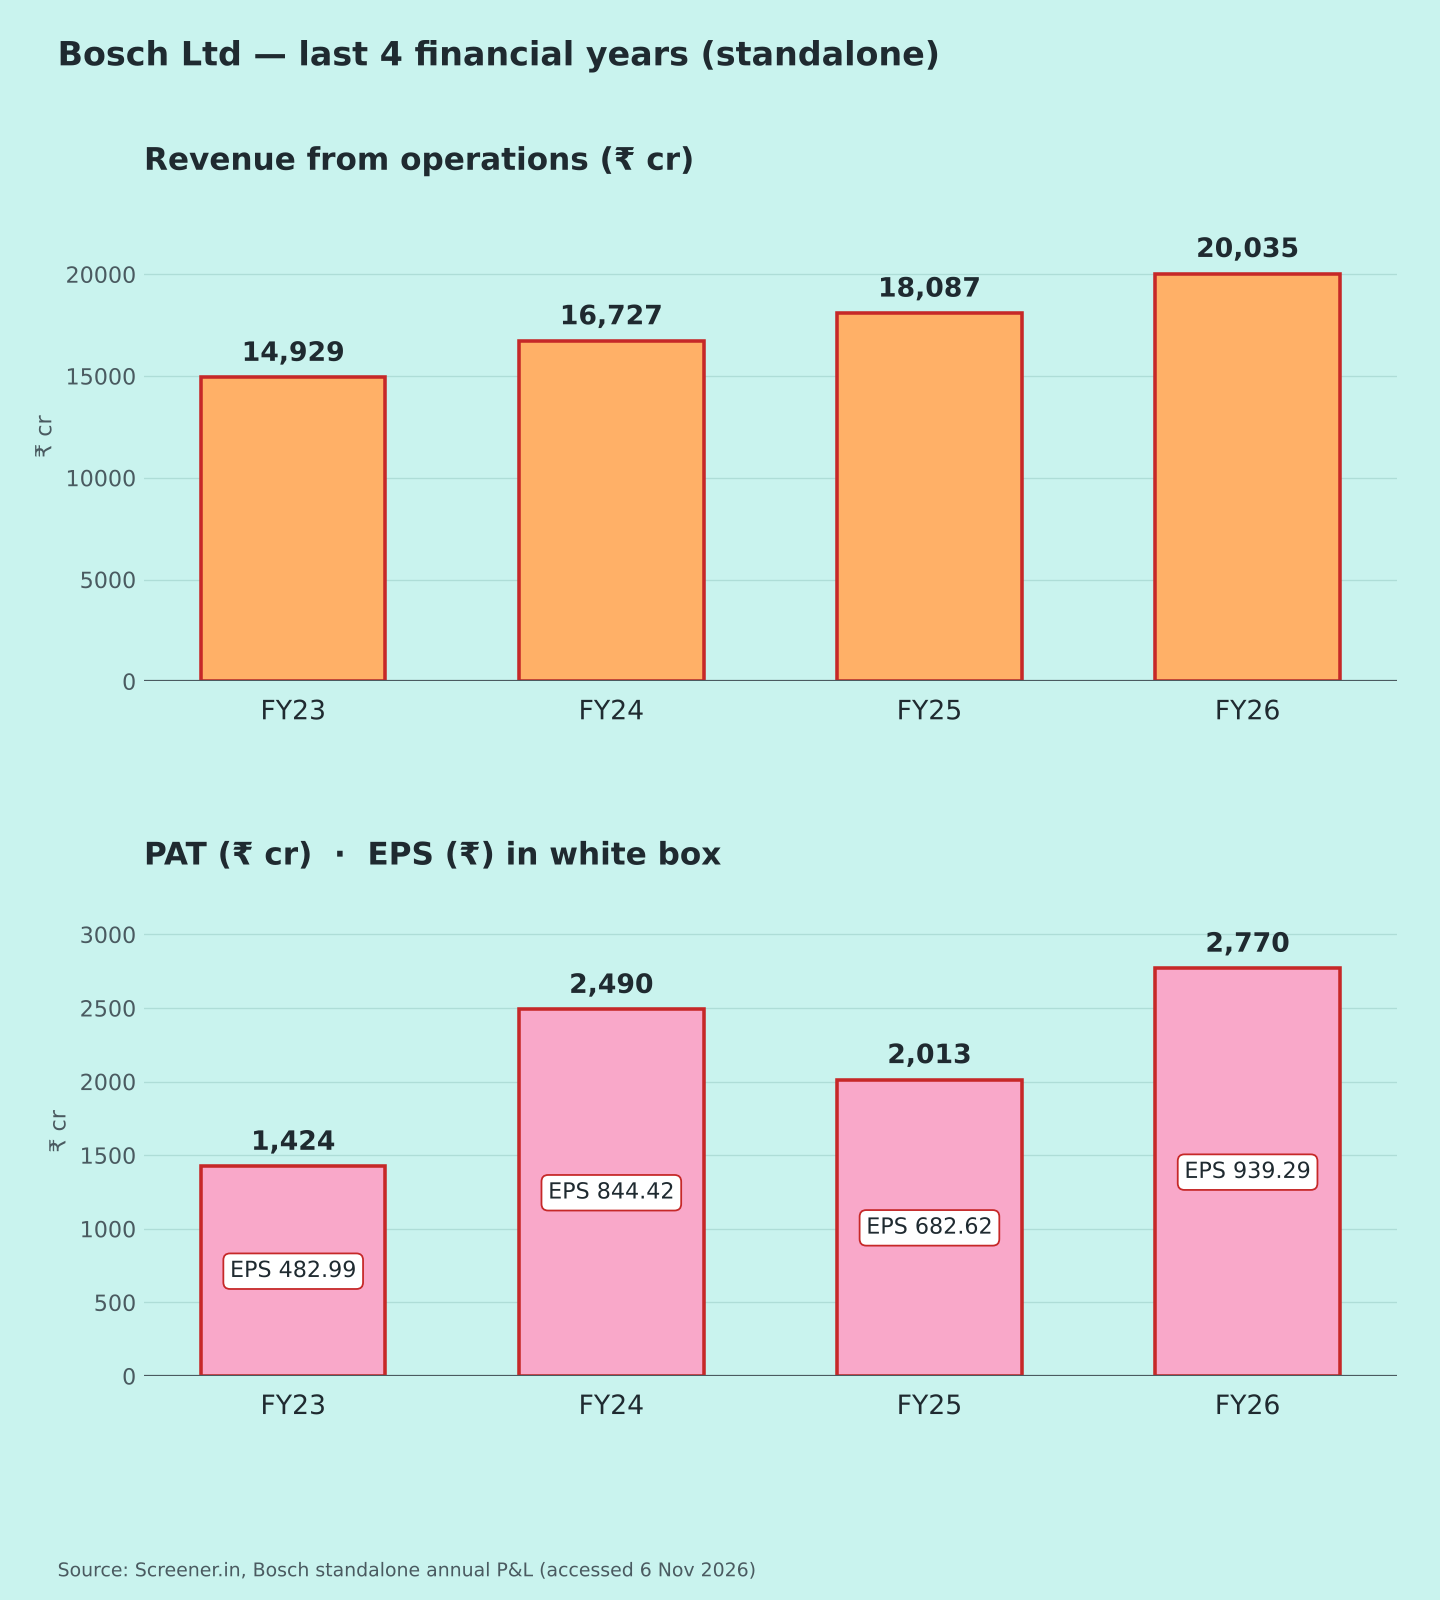
Standalone figures, ₹ crore, used throughout because the consolidated history isn't comparable. Bosch acquired Bosch Chassis Systems India (BCSI) on 1 Jul 2026 and restated prior consolidated periods [3]. PAT = total PAT. EBITDA is left out because Q2 depreciation and finance cost were not in coverage. EPS is derived.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 6,164.1 | +28.6% | +5.5% |
| Other income | 89 | −57.6% | −60.6% |
| PBT before exceptional | 778 | +6.6% | −17.1% |
| PAT | 674.6 | +21.7% | −3.9% |
| PAT excl. one-off (≈) | ≈582 | ≈+5% | ≈−17% |
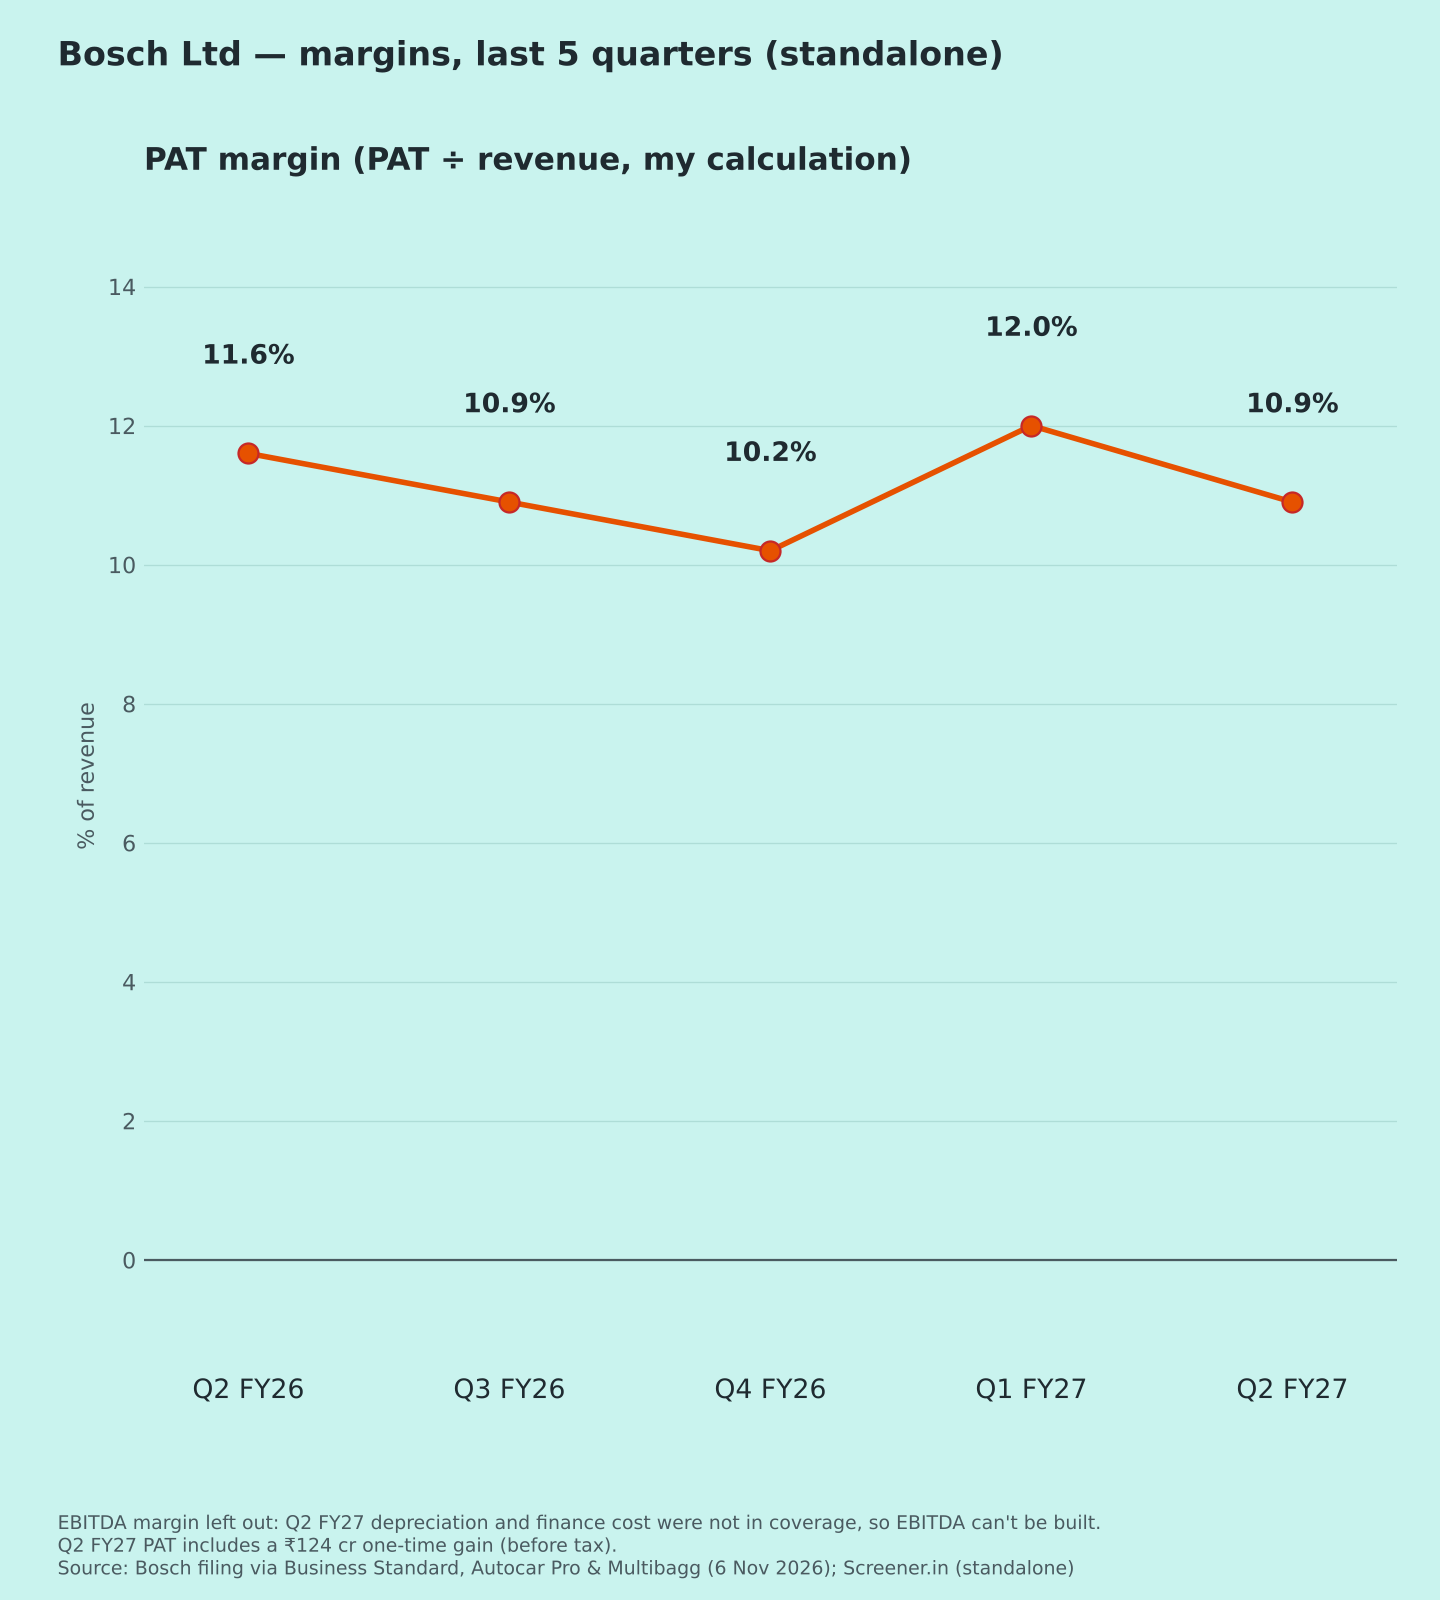
| PAT margin | 10.9% | 11.6% | 12.0% |
| EPS (₹, ≈ derived) | ≈228.8 | 187.91 → ≈228.8 | 237.93 → ≈228.8 |
| Other income / PBT | 9.9% | 28.8% | 24.1% |
Margin and ratio rows show year-ago and last-quarter values. ≈ derived: PAT excl. one-off = PAT − ₹124 cr gain × (1 − 25% tax); EPS = PAT ÷ ~2.95 cr shares, before the proposed split and bonus. % changes and ratios are my calculations. Sources: [1][2][4]
Source notes: Consolidated PAT is ₹840 cr [2][3]. Whalesbook gives ₹839.4 cr [5]. Standalone ₹674.60 cr plus BCSI's ₹164.8 cr equals ₹839.4 cr (my calculation).
Quality of earnings
- One-time gain: PAT includes a ₹124 cr exceptional gain [1]. It is the reversal of a service-award provision; the benefit will be discontinued for managerial staff from Jan 2027 [2]. Excluding it, PAT rose only ~5% (my calculation).
- Other income fell sharply to ₹89 cr from ₹210 cr. My view: cash spent on the ₹9,024 cr BCSI purchase [3] likely cut treasury income.
- Core profit rose strongly: PBT excluding other income and the one-off was ₹689 cr vs ₹520 cr, up ~32% (my calculation). Operations are doing well; lower treasury income hides it.
Margins (Chart 3)
PAT margin: 11.6% → 10.9% → 10.2% → 12.0% → 10.9% (my calculation). PBT excluding other income was ~11.2% of revenue vs ~10.8% a year ago (my calculation).
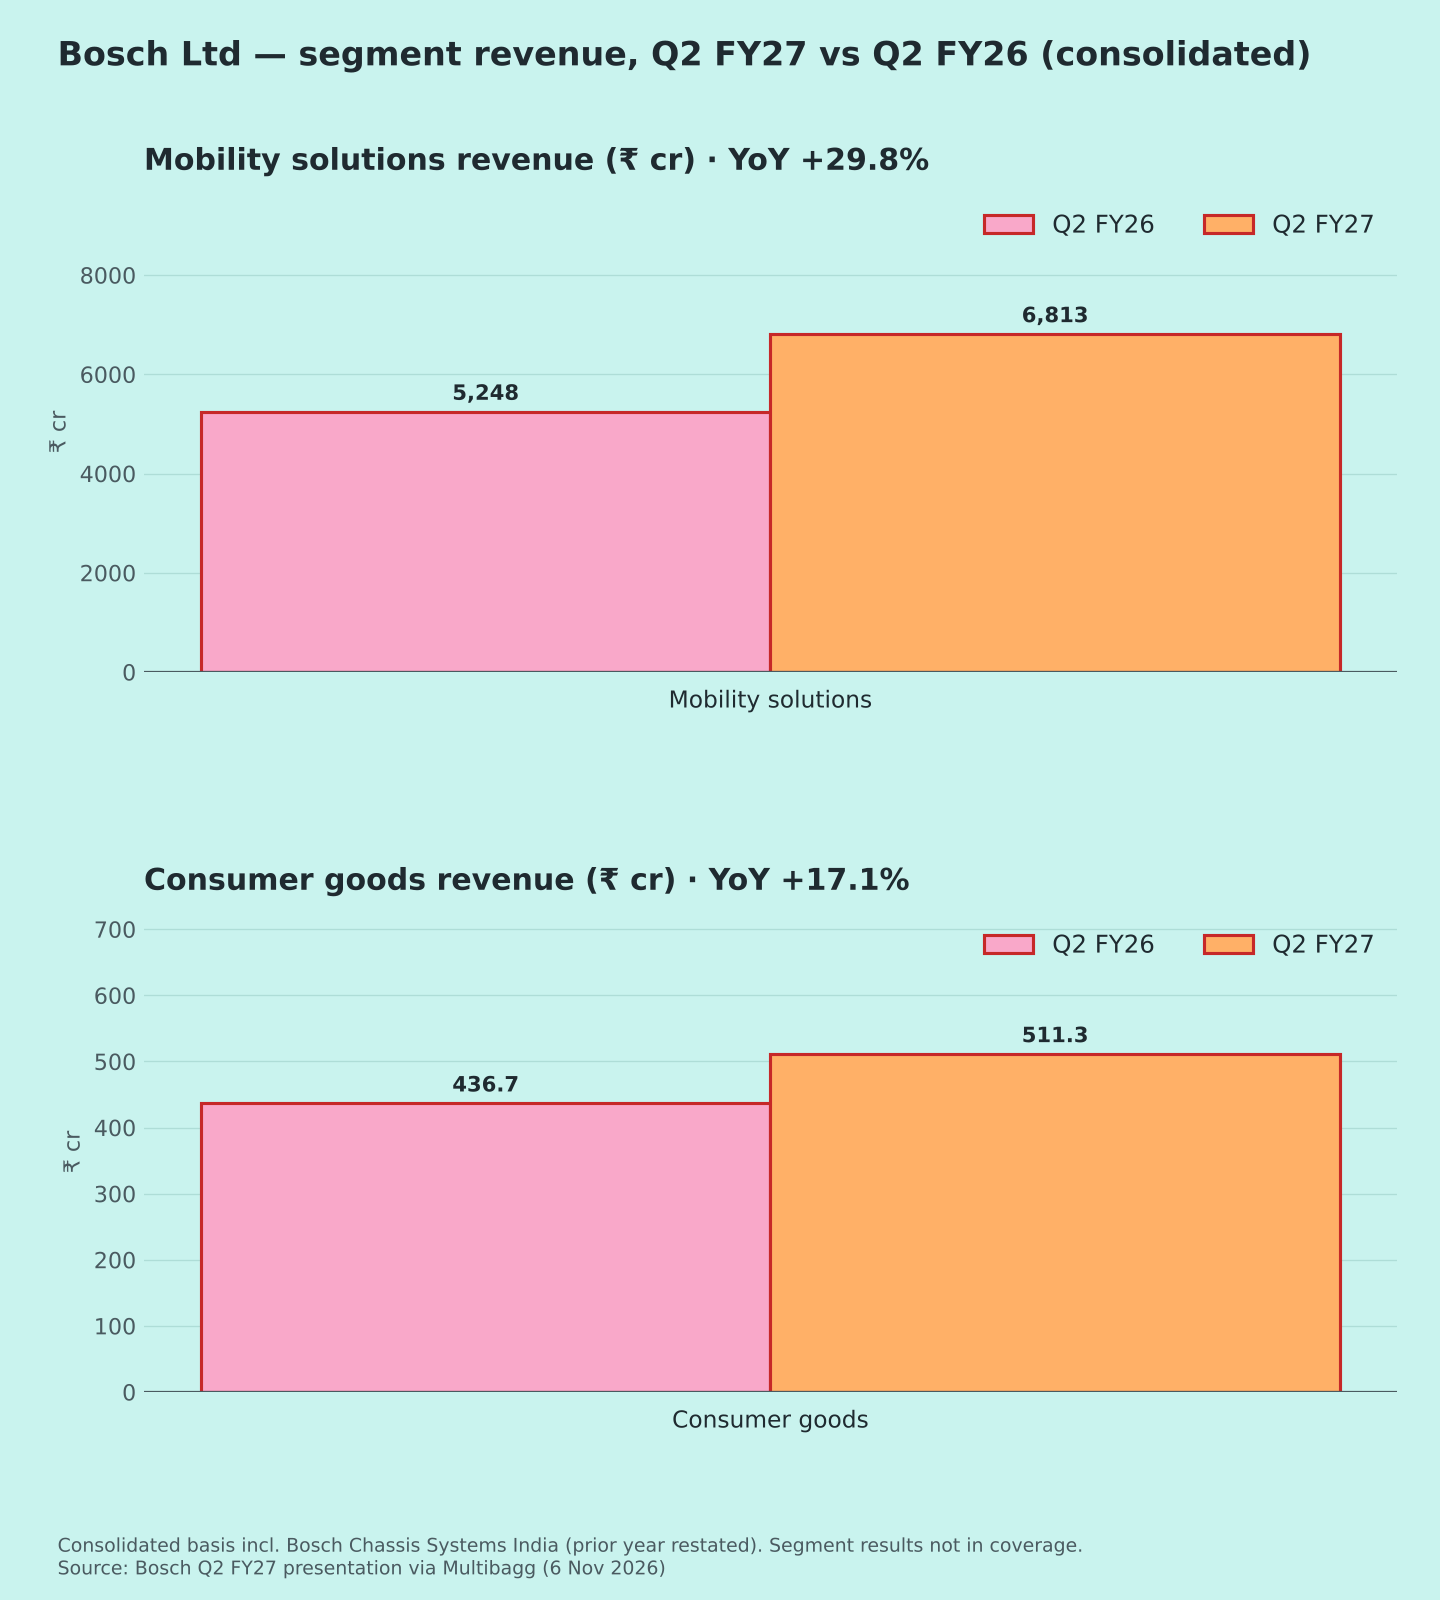
Segments (consolidated, Chart 4) [3]
- Mobility solutions: ₹6,813 cr, +29.8%. Power Solutions +36.4%, Vehicle Motion +34.9%, two-wheeler +17.7%, aftermarket +13.2%.
- Consumer goods: ₹511.3 cr, +17.1%.
- Industry backdrop in Q2: production of heavy trucks +37%, light commercial vehicles +32%, tractors +8%, two-wheelers +16% [3].
Outlook and corporate action
Management cited "steady demand across all vehicle segments" and festive momentum [2]. The company's own Q3 forecast is vehicle production (excluding two-wheelers) of 2.3 mn, down 19% QoQ [3]. No FY27 guidance was given [3].
The board approved a 1:5 stock split and a 3:1 bonus, so one share becomes 20, subject to shareholder approval [1][2]. The record date is not yet announced, and per-share figures will be restated.
Positives
- Revenue +28.6%, with core profit up ~32% (my calculation) [1]
- Broad growth across vehicle segments [3]
Concerns
- Headline PAT is flattered by a one-off gain [1]
- Lower treasury income after the acquisition (my view)
- Production is forecast to dip in Q3 [3]
Things to track in Q3 FY27
- Revenue and margins as production dips
- BCSI's contribution to consolidated profit
- Split/bonus record date
- Other income trend
Not a buy/sell recommendation. I am not a SEBI-registered analyst. Facts are sourced; opinions are labelled.
Sources [1] Business Standard – Bosch results, split & bonus · [2] Autocar Pro – Q2 results · [3] Multibagg – Q2 profit, segments, BCSI, outlook · [4] Screener.in – standalone · [5] Whalesbook – Q2 profit · [6] Autocar Pro – split & bonus
Charts: (1) 5 quarters standalone revenue & PAT with EPS [1][4]; (2) FY23–FY26 [4]; (3) PAT margin [1][4]; (4) headline [1][4]; (5) consolidated segment revenue [3].