Swiggy (SWIGGY): Q2 FY27 Results Analysis
(Quarter ended 30 Sep 2026)
All figures consolidated, ₹ crore unless stated. Results filed after market hours on 22 Oct 2026 [1][2]. EBITDA here excludes other income. YoY/QoQ %, margins and ratios are my calculations from reported numbers.
| Metric | Q2 FY27 | Q2 FY26 | Q1 FY27 |
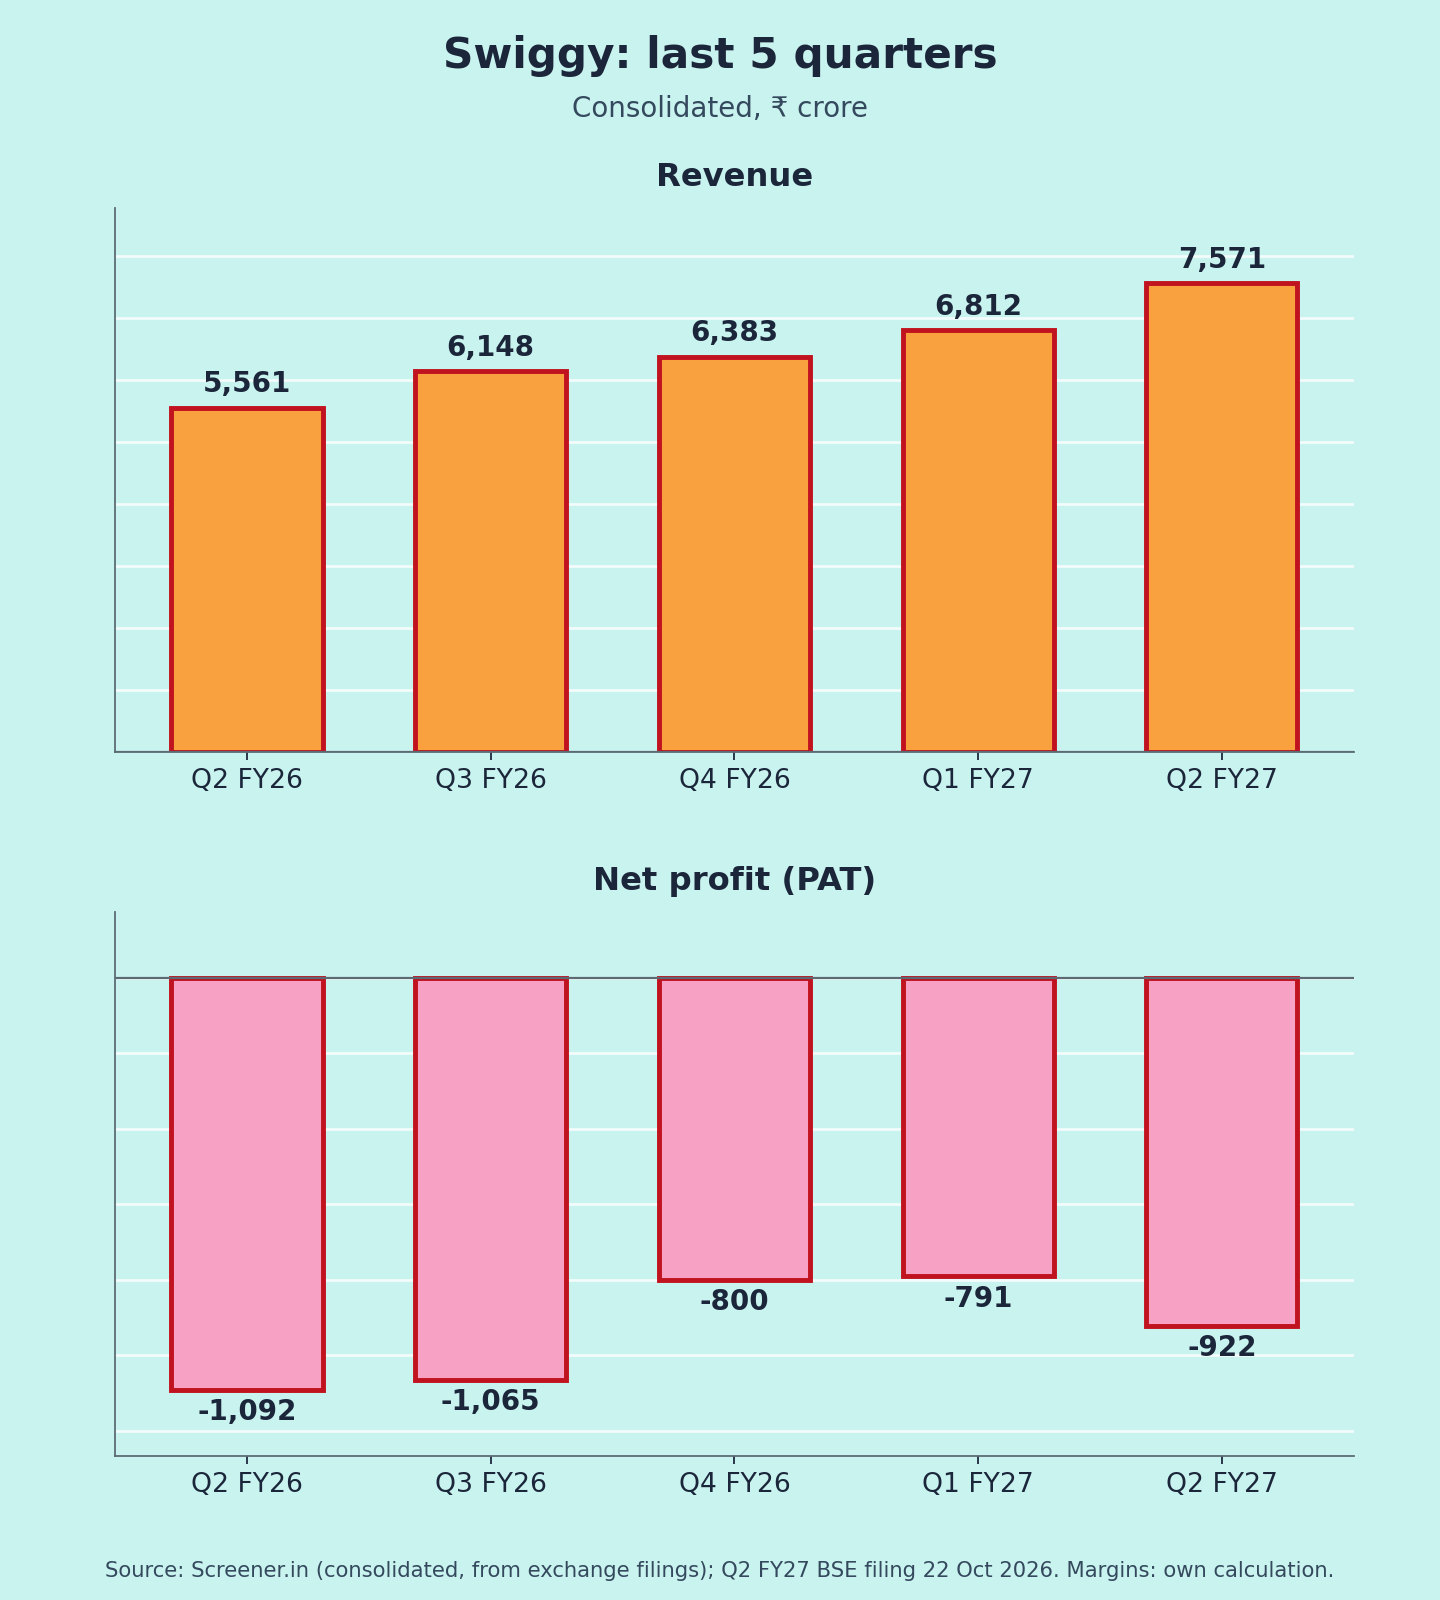
| Revenue from ops | 7,571 (+36.1% YoY, +11.1% QoQ) | 5,561 | 6,812 |
| EBITDA (ex-OI) | (772) | (799) | (651) |
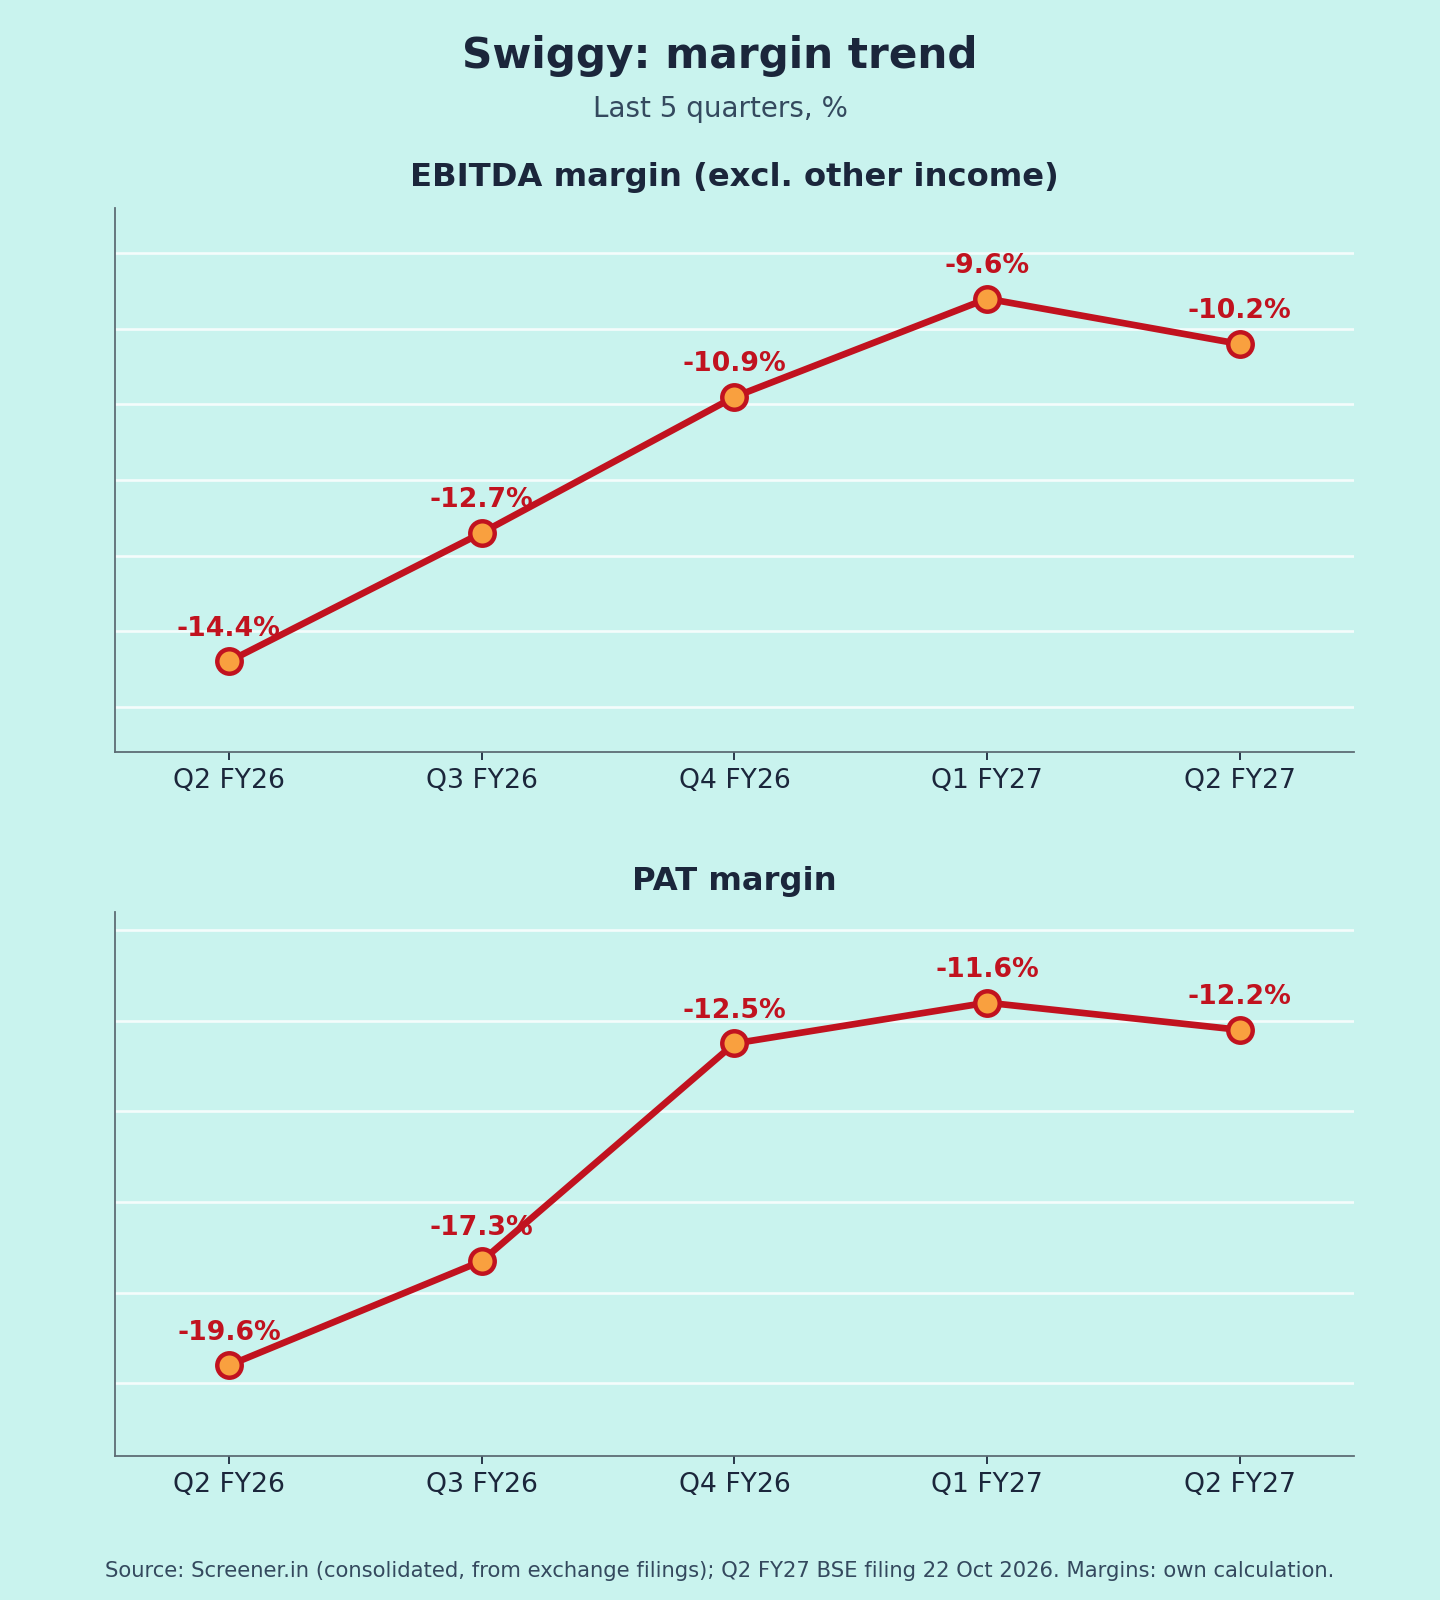
| EBITDA margin | −10.2% | −14.4% | −9.6% |
| Adjusted EBITDA (company) | (760) | (695) | (651) |
| Net loss | (922) | (1,092) | (791) |
| PAT margin | −12.2% | −19.6% | −11.6% |
| Other income | 212 | 59 | 211 |
Sources: [1][2][3]. Other income/PBT is not meaningful because the company is loss-making.
Quality of earnings
The loss narrowed 16% YoY but widened 17% QoQ [2]. Other income has jumped to ₹212 cr from ₹59 cr a year ago, as fund-raise money earns interest [1]. Excluding it, the pre-tax loss was ~₹1,134 cr vs ~₹1,151 cr a year ago (my calculation), so the core loss is roughly flat YoY. No tax is paid and no exceptional item is reported.
Two businesses, two stories [3]:
- Food delivery: record adjusted EBITDA of ₹341 cr (3.4% of GOV); GOV +17.7%; take rate 26.1%.
- Instamart (quick commerce): GOV +31.4% to ₹9,230 cr, but adjusted EBITDA loss widened to ₹895 cr (−9.7% of GOV); contribution margin −1.0%.
Margins (Chart 3)
EBITDA margin: −14.4% → −12.7% → −10.9% → −9.6% → −10.2% [1]. Four quarters of improvement reversed in Q2, as management chose to spend on Instamart growth (69 net new dark stores, pricing such as the ₹9 store) [3].
Guidance: what changed
- Instamart contribution margin: hit breakeven in May 2026, as guided a year earlier [5]. In Q2 it slipped back to −1.0%; management now guides a 0 to −100 bps band for Q3 [3]. Effectively, breakeven was traded for growth.
- Losses: management says adjusted EBITDA losses "likely peaked" in Q2, with ~100 bps margin improvement in Q3 [3].
- Food delivery: 18–20% GOV growth and the 5% long-term margin target are unchanged [3][5].
- Inventory model (IOCC): transition from mid-Q3, over 2–3 quarters; expected to add ~80 bps to Instamart contribution margin [3].
- Lynks sale: B2B distribution arm sold to Udaan's parent for ₹500 cr; deconsolidated from Q3 [3].
- Competition: management expects it to stay intense through the festive quarter [3].
Market reaction (interpretation)
Before the results, the stock fell 5.5% to ₹211.40, a new low and ~46% below the IPO price [6][2]. FIIs cut their stake to 8.86% from 13.96% in the quarter [1]. The post-results reaction will show on 23 Oct.
Positives
- Food delivery margin at a record 3.4% of GOV [3]
- Instamart orders +29% and GOV growth re-accelerating [3]
- Cash of ₹13,662 cr [3]
Concerns
- Instamart losses rising again; competition not easing [3]
- Core loss (ex-other income) not improving YoY (my calculation)
- Profitability now depends on a delayed Instamart turnaround (my view)
Things to track in Q3 FY27
- Instamart contribution margin within 0 to −100 bps, and adjusted EBITDA margin improving ~100 bps
- Progress of the IOCC/inventory transition
- Food delivery GOV growth vs the 18–20% guide
- Cash burn vs the ₹13,662 cr cash balance
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Screener.in – consolidated · [2] Trendlyne – filings & price, 22 Oct · [3] Multibagg – Q2 FY27 shareholder letter summary · [4] InvestyWise (mislabelled Q1 data) · [5] Inc42 – Q1 FY27 · [6] Business Standard, 22 Oct · [7] Business Standard – Q2 FY27
Charts:
(1) last 5 quarters revenue & PAT [1];
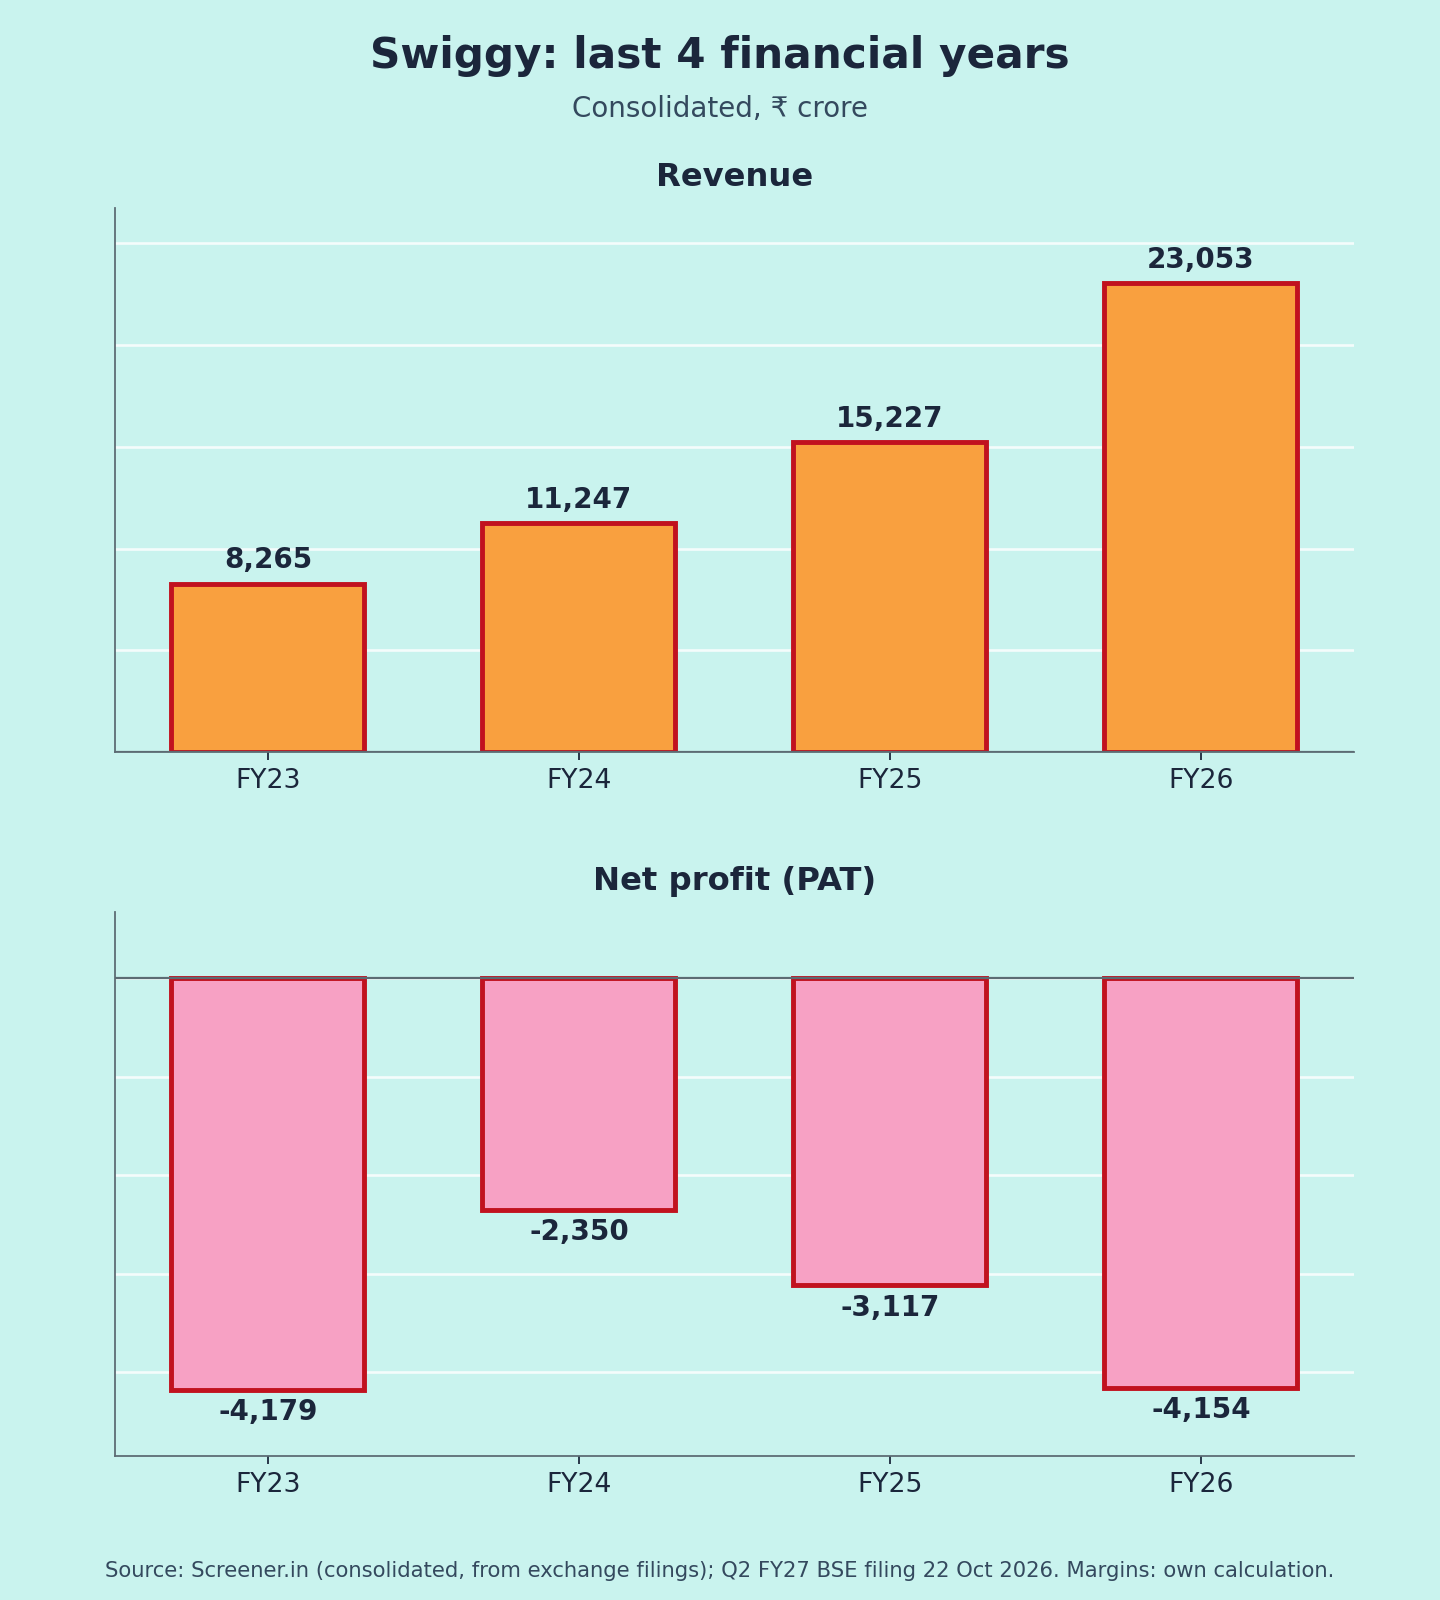
(2) FY23–FY26 revenue & PAT [1];
(3) EBITDA and PAT margin (own calc. from [1]).