Sterlite Technologies (STLTECH): Q2 FY27 results analysis
(quarter ended 30 Sep 2026)
All figures consolidated, ₹ crore unless stated. Results released during market hours on 23 Oct 2026 [3]. YoY/QoQ % and margins are my calculations from reported numbers.
| Metric | Q2 FY27 | YoY | QoQ |
| Revenue from ops | 2,529 | +144.6% | +32.4% |
| EBITDA (reported) | 846 | +500% | +113% |
| EBITDA excl. tariff refund | 685 | +386% | +72.5% |
| EBITDA margin (reported) | 33.5% | 13.6% | 20.8% |
| EBITDA margin excl. refund | 27.1% | 13.6% | 20.8% |
| PAT | 517 | n.m. (₹4 cr base) | +162% |
| PAT margin | 20.4% | 0.4% | 10.3% |
| Other income / PBT | n.a.* | 200% | 4.7% |
For margin and ratio rows, the YoY and QoQ columns show the prior-period value. *Q2 PBT wasn't in the coverage I found. Other income was about ₹34 cr (total income minus revenue [3]), small next to PAT.
Sources: [1][2][3][7][13]
Quality of earnings
Two one-offs pull in opposite directions:
- Boost: a one-time ₹161 cr US tariff refund, included in EBITDA [2].
- Drag: a ₹49 cr impairment and ₹22 cr of extra depreciation at the Speedon Networks subsidiary [2].
The net effect is roughly +₹90 cr pre-tax (my calculation). So underlying profit is lower than the headline ₹517 cr.
Finance cost rose 15% YoY despite lower debt, because of prepayment penalties on loans repaid early [2].
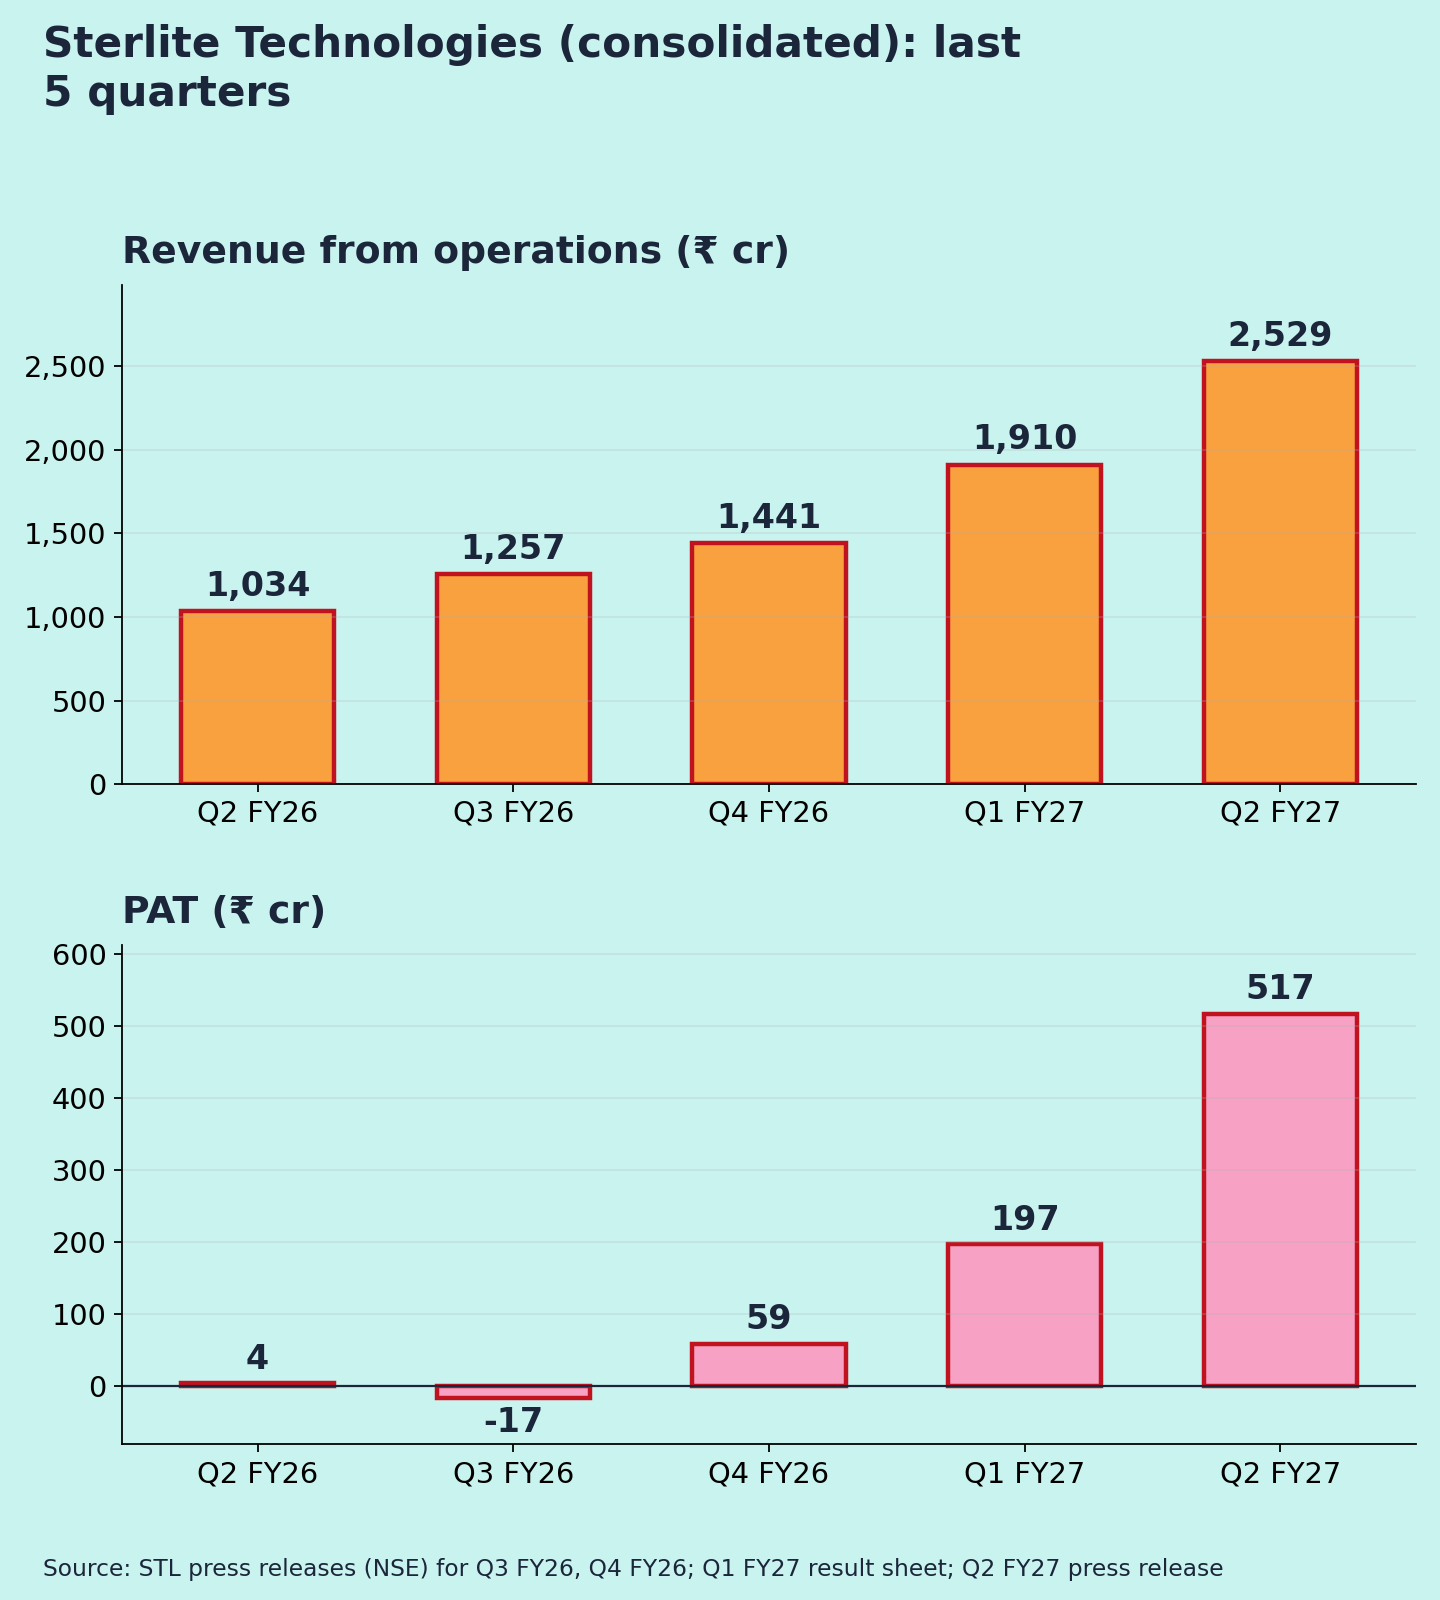
Base effect: YoY growth is flattered by a very weak base. Q2 FY26 PAT was just ₹4 cr, and Q3 FY26 was hit by US tariffs (~760 bps, per Arihant [12]). The QoQ read is cleaner: revenue +32%, and operational margin +624 bps [2].
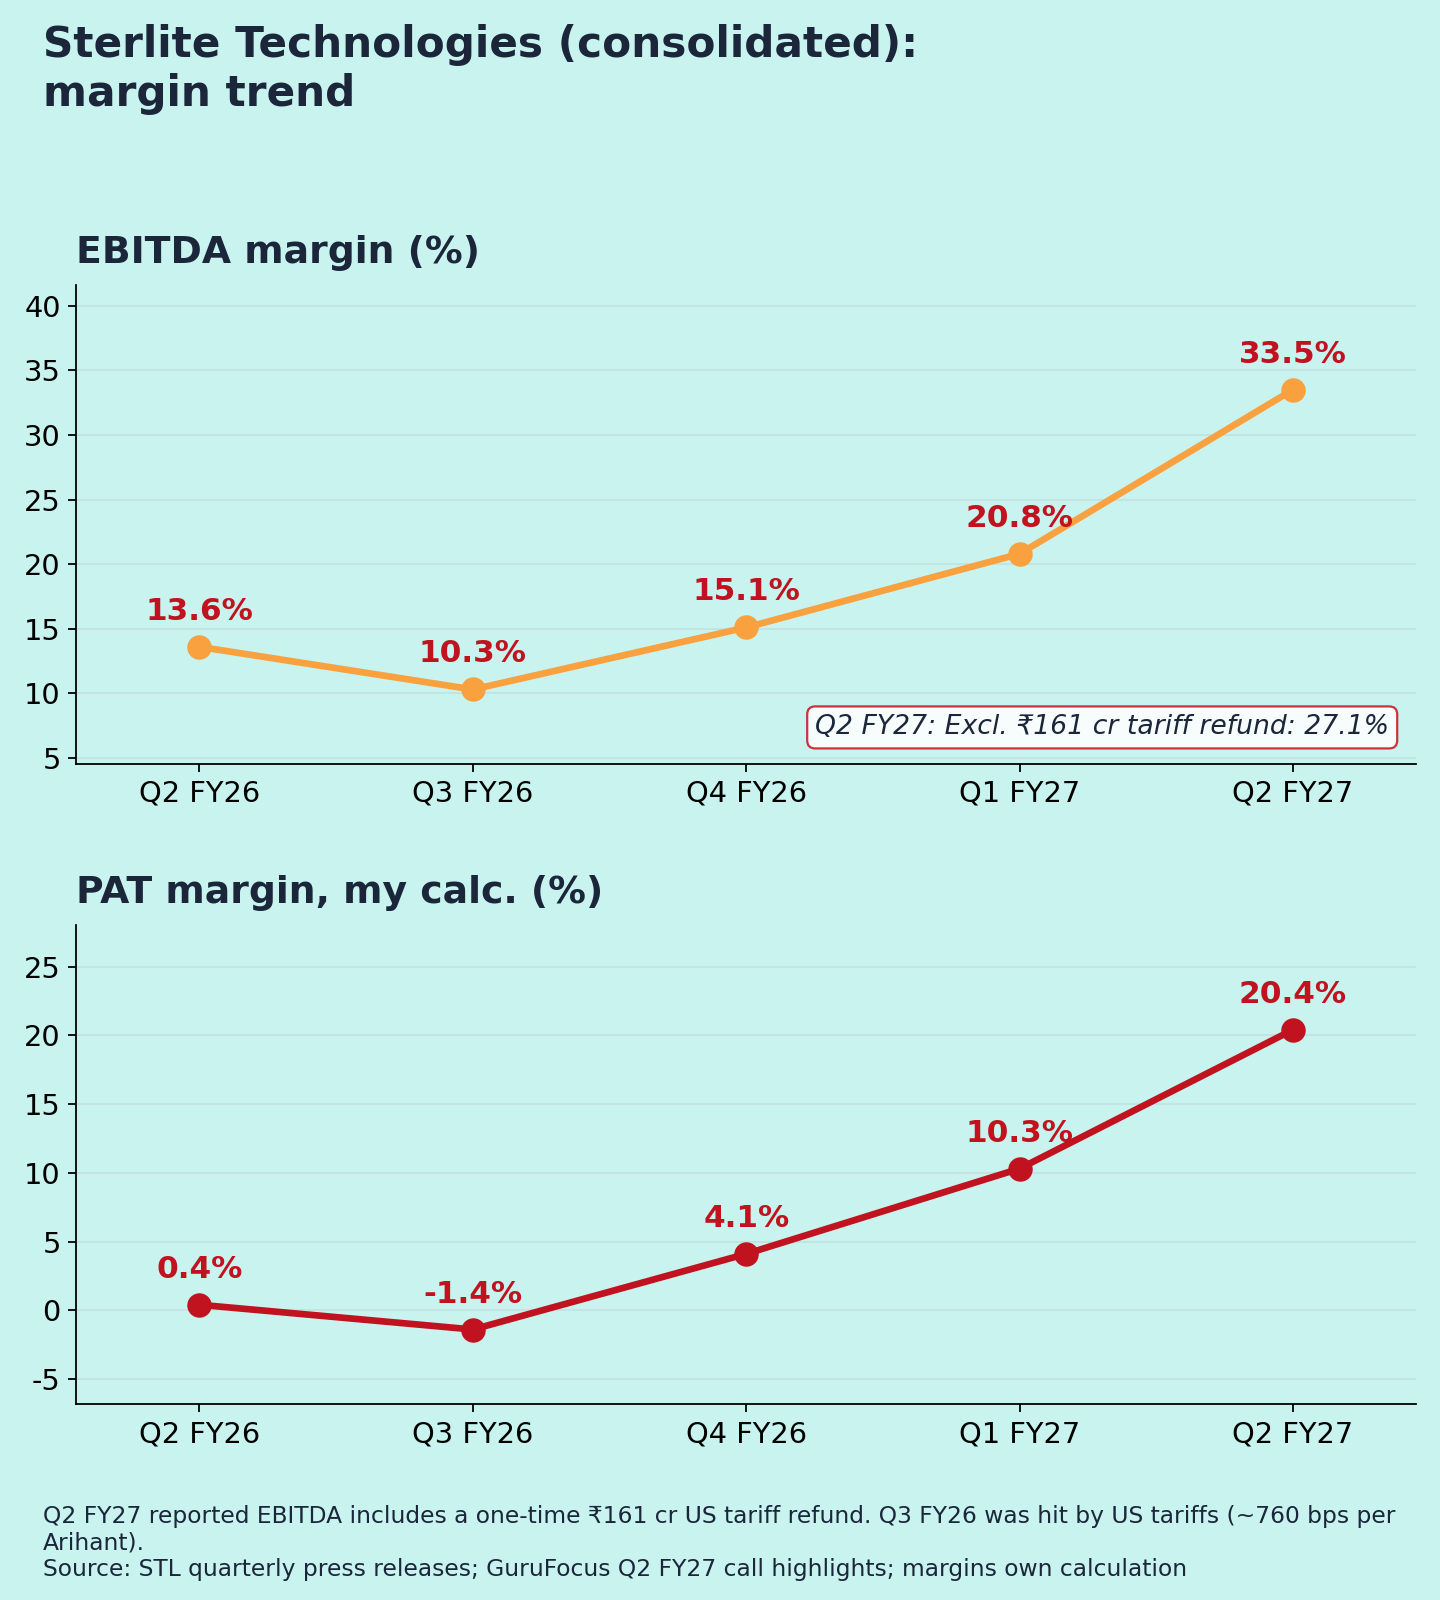
Margins (Chart 3)
Reported EBITDA margin over five quarters: 13.6% → 10.3% → 15.1% → 20.8% → 33.5% (27.1% excluding the refund) [1][5][6][8].
Management credits the mix shift to data-centre products. These were 33% of H1 revenue, with ~50% targeted for FY27 [2]. The connectivity attach rate hit a record 24% [2].
Guidance: what changed
- FY27 margin: an analyst on the call cited earlier guidance of ~23%; H1 is already 24.4%. The CFO aims to stay at or above the Q2 level [2].
- FY29 targets: revenue target of ₹20,000 cr unchanged. EBITDA margin target raised to ~30% from 27% [2].
- Order book: ₹35,274 cr, 4.6x the start-of-year level. About ₹3,021 cr is scheduled for Q3 [2]. H1 orders of ₹32,000 cr include two hyperscaler deals worth $1.2 bn and $1.11 bn [2].
- Capex: about ₹1,000 cr a year through FY29 for 50% more capacity [2].
- Balance sheet: net cash ₹703 cr (₹483 cr in Q1); CRISIL upgraded the rating to AA [2].
Positives
- Record order book gives multi-year visibility [2]
- Net-cash balance sheet [2]
- Mix shift to higher-margin data-centre products [2]
Concerns
- One-offs cloud the true run-rate [2]
- Growth depends on hyperscaler AI capex [2]
- Payable days have fallen sharply, which pressures working capital [2]
- Data-centre project delays (land, power, water) could slow execution [2]
Things to track in Q3 FY27
- Q3 revenue vs the ~₹3,021 cr scheduled for execution
- EBITDA margin without one-offs: can it hold near 27%?
- Data-centre share moving toward 50% of revenue
- Capex pace and net cash
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] STL press release via Business Standard/ANI, 23 Oct 2026 · [2] GuruFocus – Q2 FY27 call highlights · [3] Angel One, 23 Oct · [4] Multibagg – Q2 FY27 · [5] NSE – Q3 FY26 release · [6] NSE – Q4 FY26 outcome · [7] STL – Q1 FY27 result sheet · [8] Free Press Journal – Q1 FY27 · [9] 5paisa – quarterly PAT · [10] Stockanalysis – annual · [11] Outlook Business – FY26 · [12] Arihant – Q3 FY26 update · [13] Arihant – Q2 FY26 update
Charts:
(1) last 5 quarters revenue & PAT;
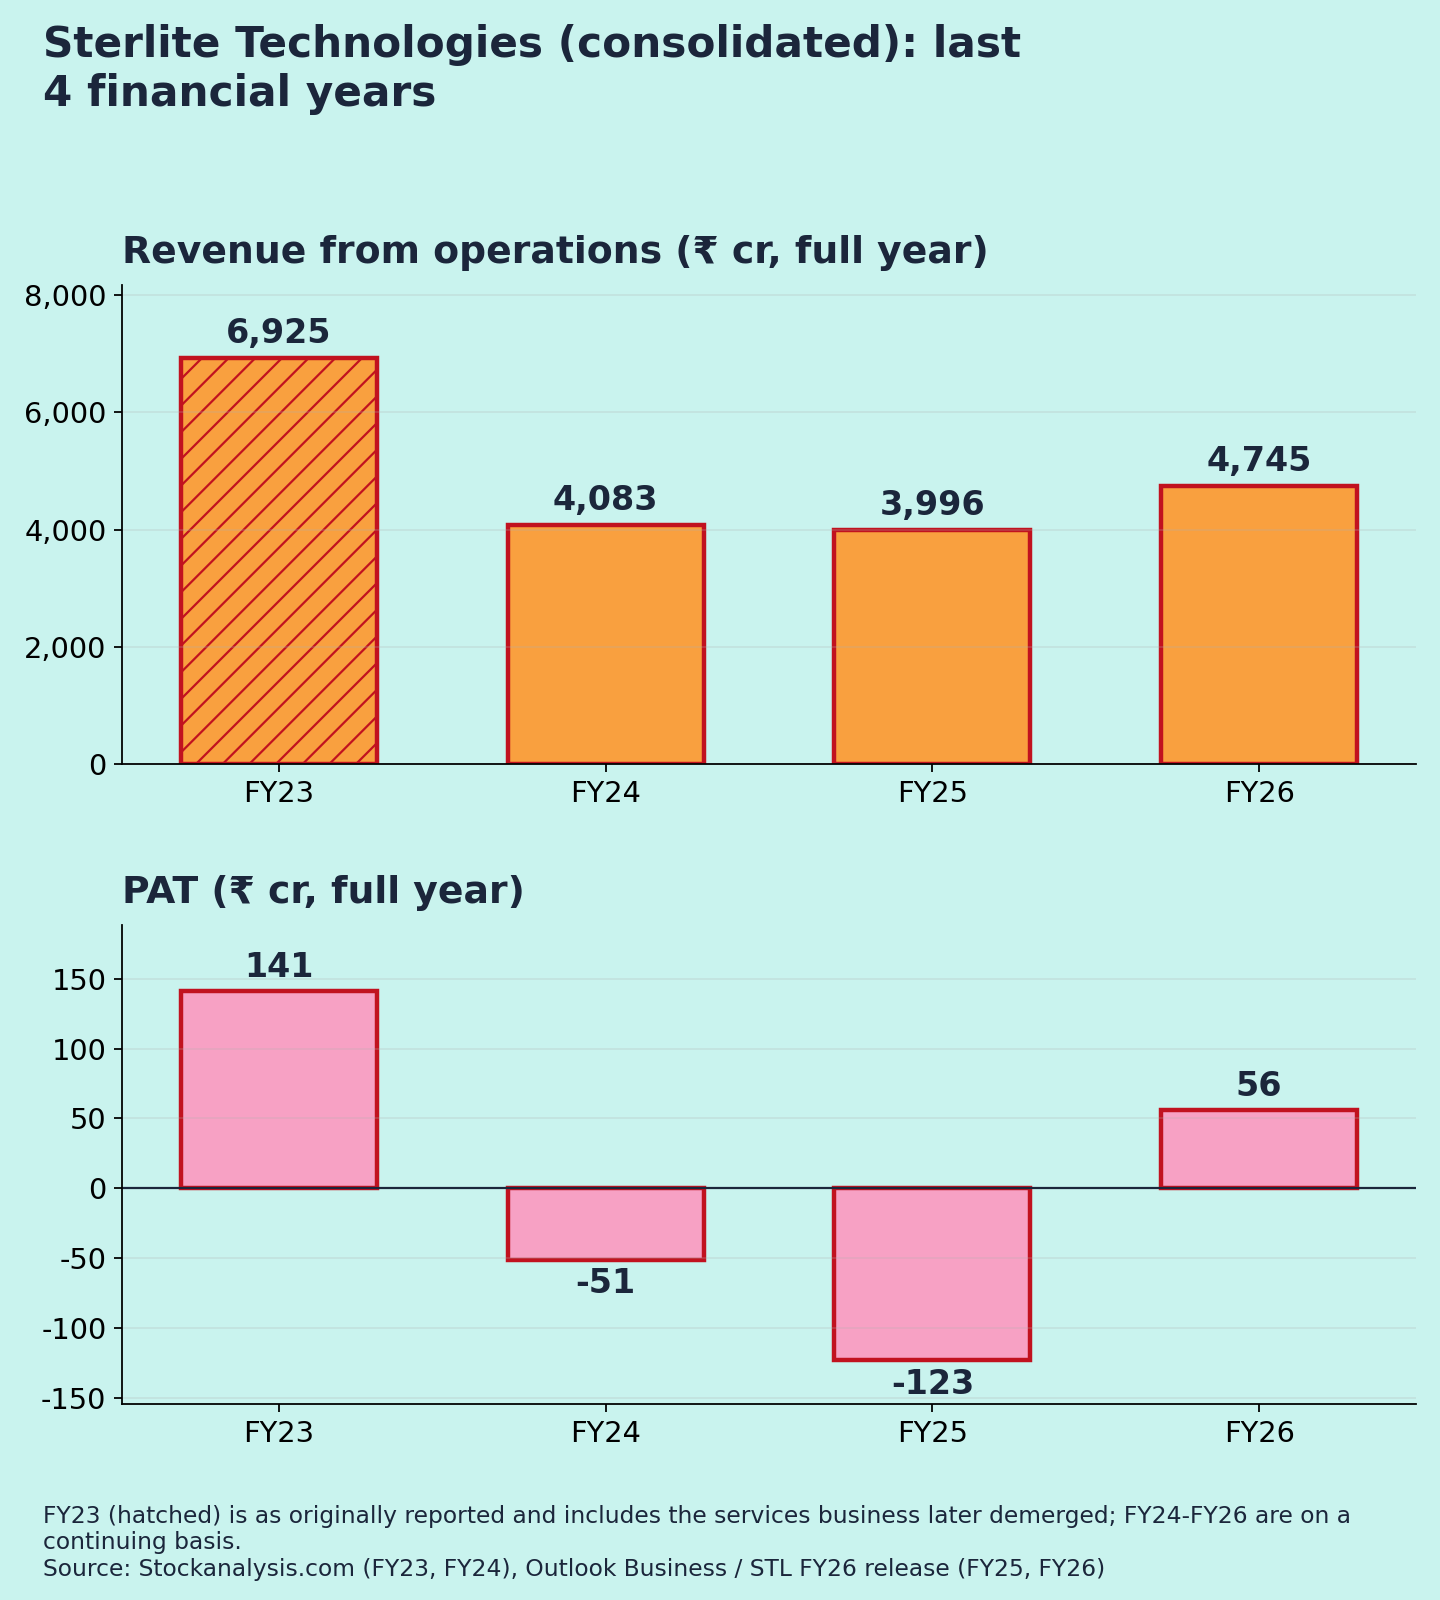
(2) FY23–FY26 revenue & PAT. FY23 is as reported and includes the services business later demerged, so it isn't comparable with FY24–FY26.
(3) EBITDA and PAT margin (own calc.).