Info Edge / Naukri (NAUKRI): Q2 FY27 results analysis
(Quarter ended 30 Sep 2026)
Figures are standalone, ₹ crore unless stated. That is the basis on which the company reports billings and operating margins, and it excludes the investment-fund subsidiaries. Results released on 28 Oct 2026. YoY/QoQ % and margins are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
| Billings | 822.3 | +12.8% | +11.6% |
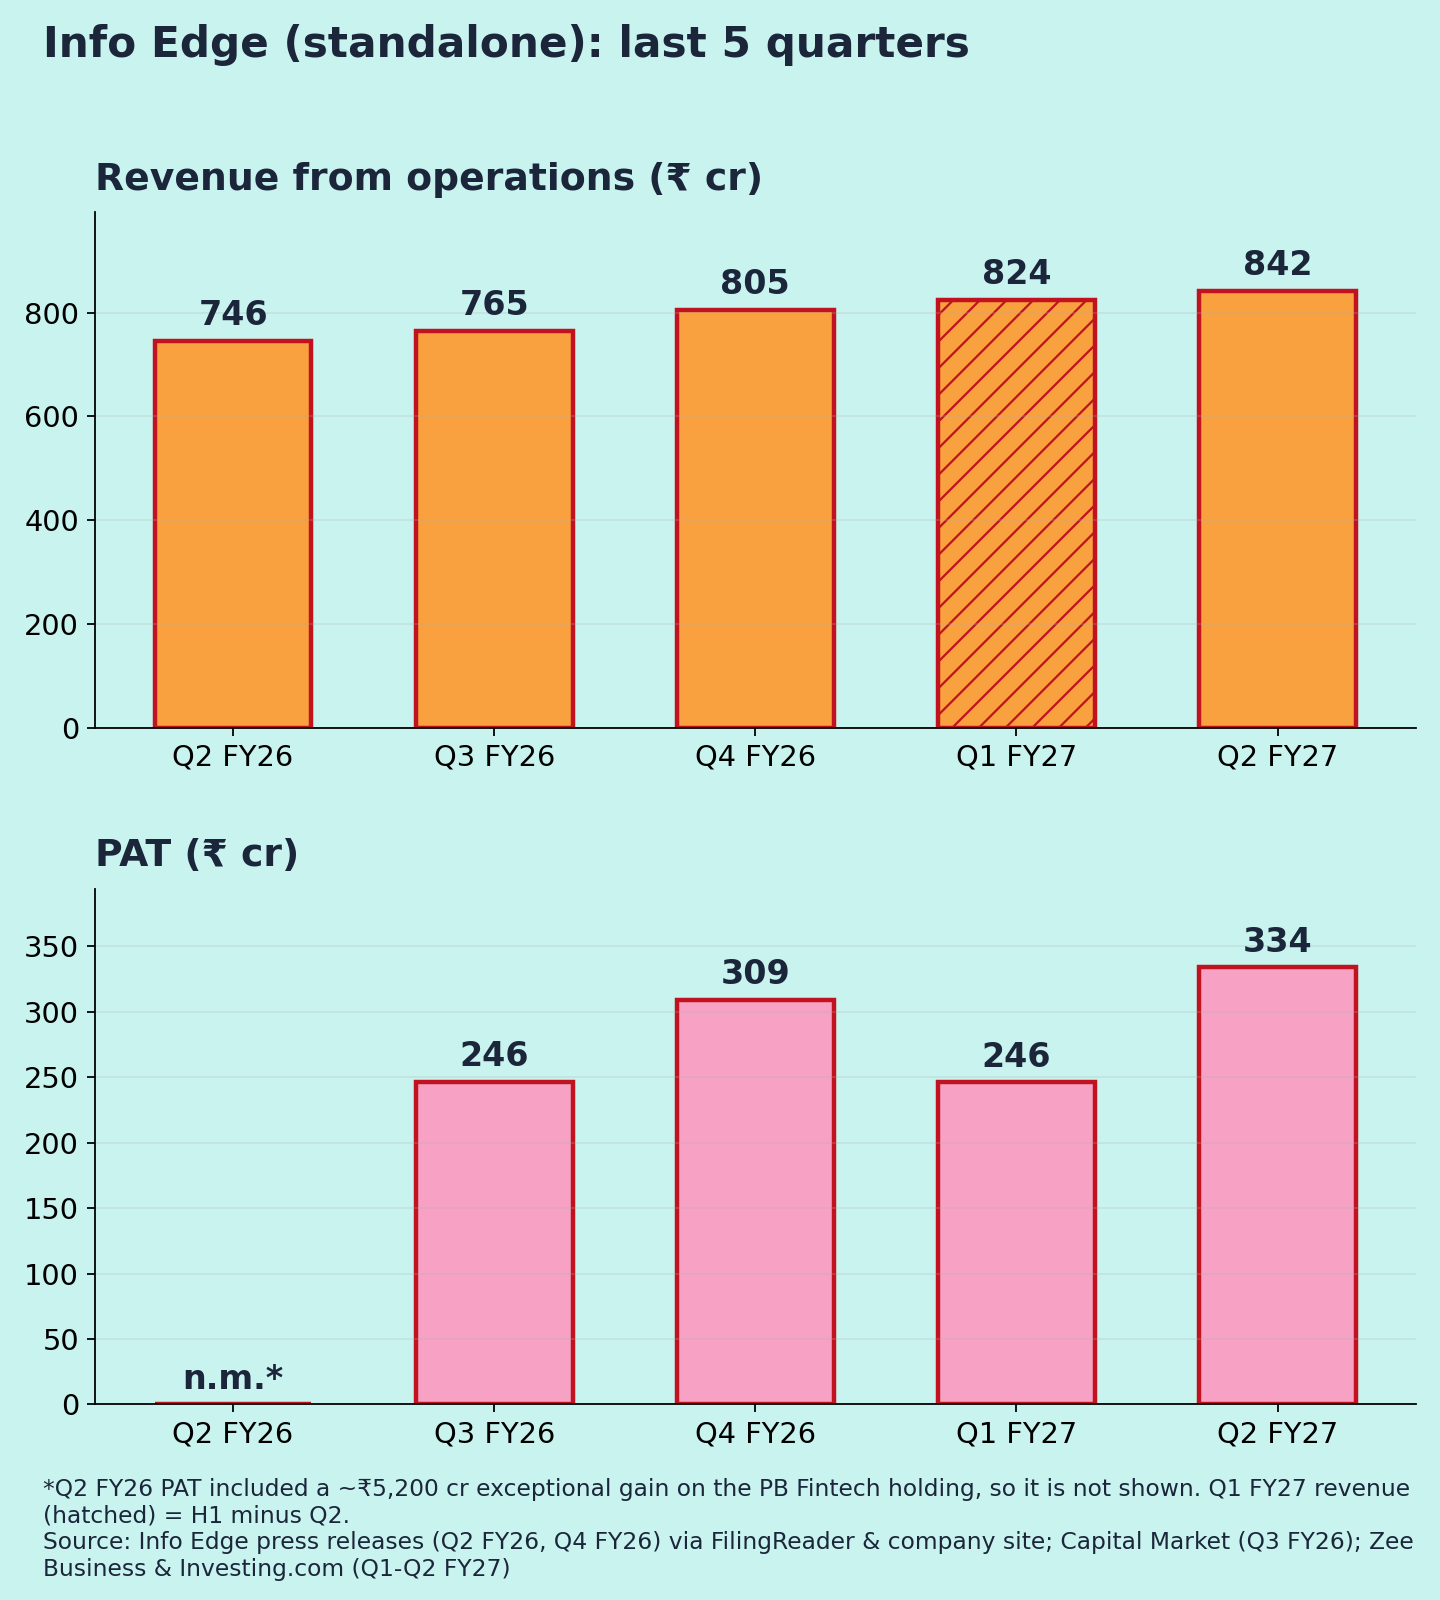
| Revenue from ops | 841.7 | +12.8% | +2.1% |
| Operating profit (company) | 347.3 | +29.8% | +4.1% |
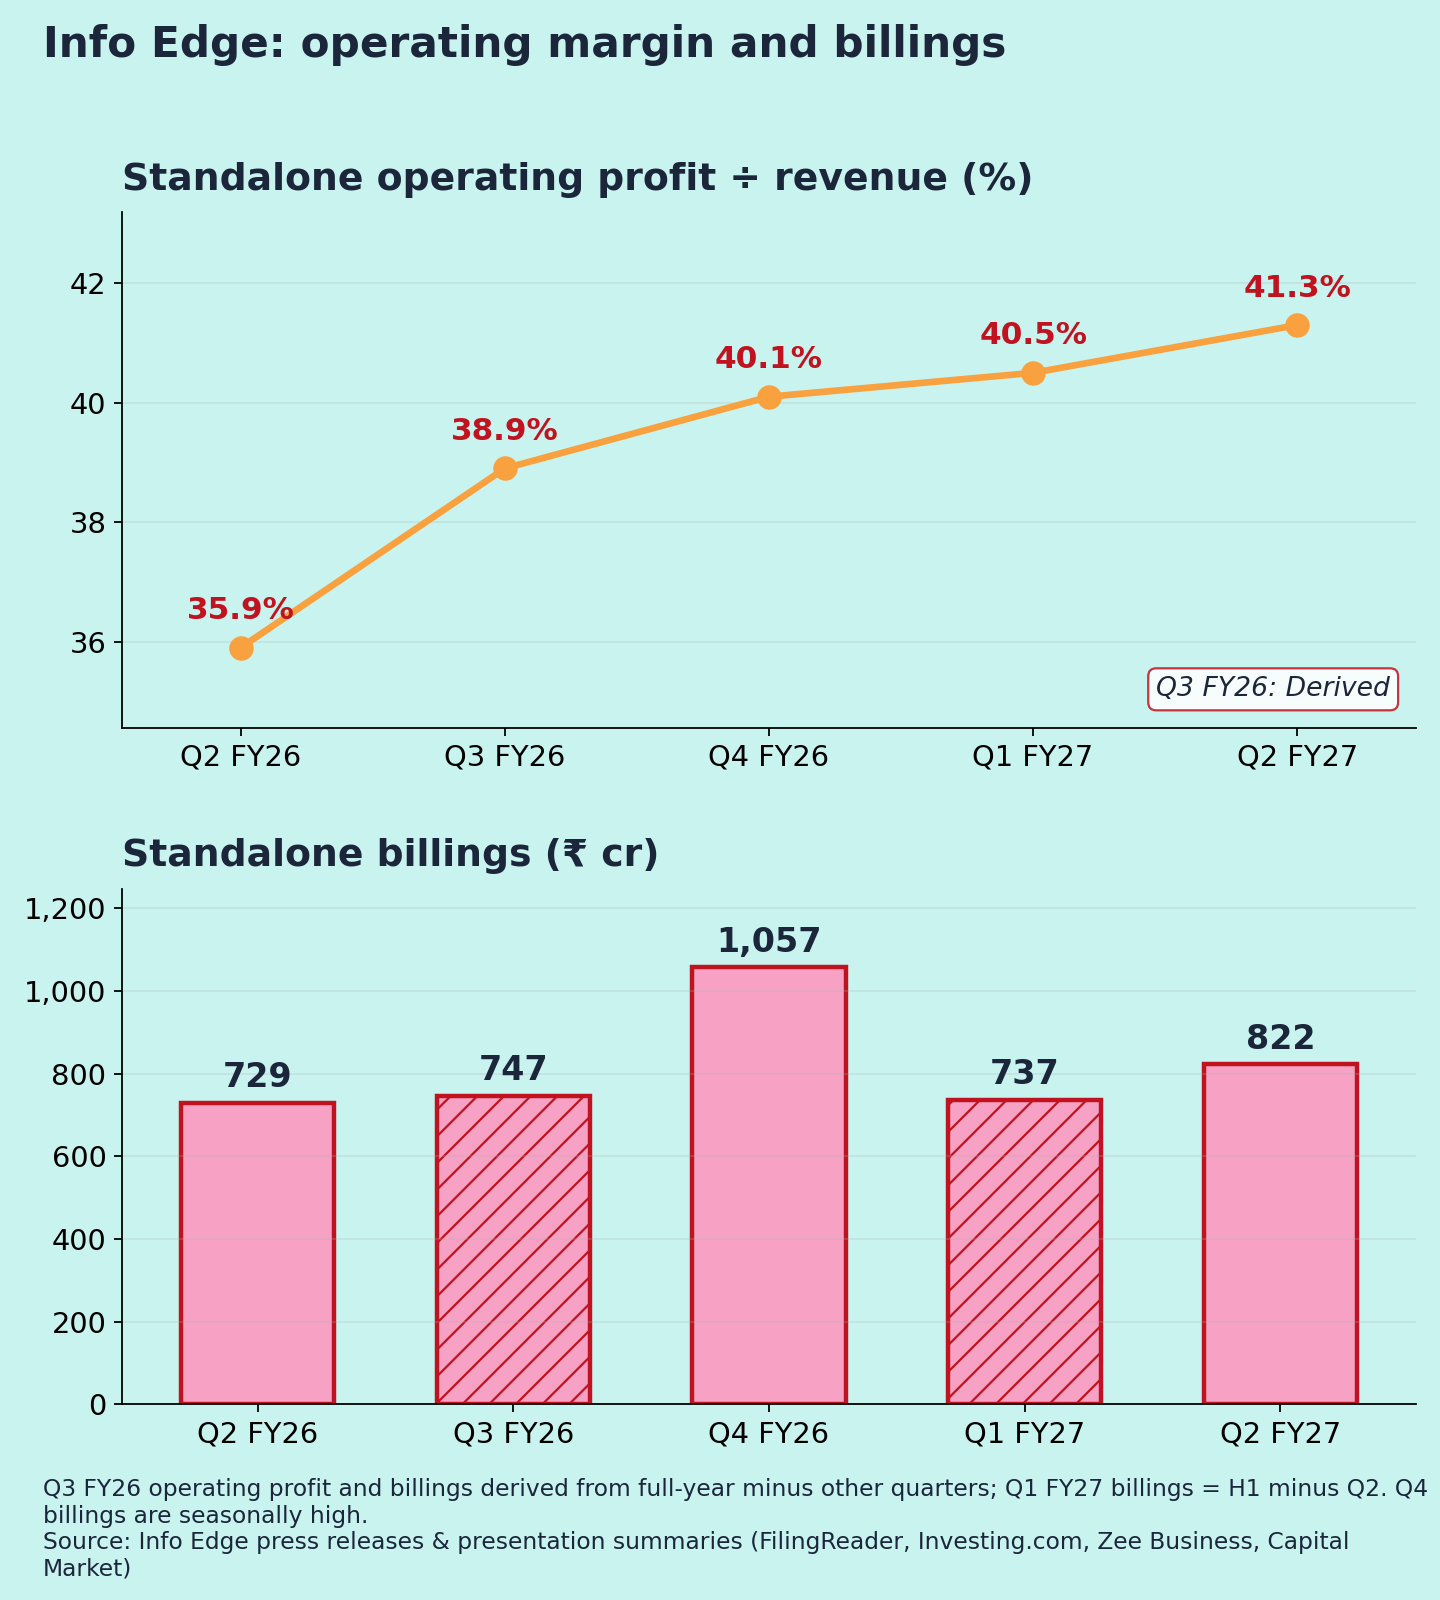
| Operating margin | 41.3% | 35.9% | 40.5% |
| PAT | 334 | n.m.* | +36% |
| Recruitment billings | 613.8 | +12.6% | – |
For margin rows, the YoY and QoQ columns show the prior-period value. *Q2 FY26 standalone PAT included a ~₹5,200 cr exceptional gain on the PB Fintech holding [13], so YoY isn't meaningful.
Consolidated, for reference: PAT was ₹649.8 cr (+87%). The owners' share was ₹479.7 cr (+51.6%), and ₹170 cr went to minority investors in subsidiaries [4]. Consolidated other income was ₹428 cr against ₹162 cr a year ago, about 57% of PBT (my calculation). Headlines quoting "+87%" mostly reflect investment gains, not Naukri's business.
Quality of earnings
The operating business improved steadily:
- Operating profit: +30% on revenue +13%, so margins expanded.
- Billings mix: billings excluding Shiksha grew 14.4%. 99acres billings grew 21.2%. The B2C candidate-services business grew 37%.
- Cash: cash from operations rose 27.4% to ₹373 cr [5].
Standalone PAT (+36% QoQ) is also helped by treasury income on the company's large cash pile.
Base effect: Q2 FY26 standalone margin (35.9%) was the low point of the series [7]. The margin gain is real, but it started from a soft base.
Margins (Chart 3)
Operating margin over five quarters: 35.9% → ~38.9% → 40.1% → 40.5% → 41.3%. That is four straight quarters of expansion. Management credits operating leverage in recruitment and narrower losses in non-recruitment businesses. 99acres turned EBITDA-positive in Q4 FY26.
Management commentary / guidance
- Guidance: Info Edge gives no numeric guidance.
- Recruitment: billings grew 15% in H1, and AI products are now contributing to recruitment revenue [2].
- FY27 outlook: after Q4 FY26's soft billings, management had said it expected "an improved growth trajectory in FY27" [10]. H1 billings growth of 13.5% vs FY26's 10.3% supports that (my calculation from [2][10]).
- Dividend: interim ₹3 per share; record date 6 Nov [2].
Positives
- Operating margin at a five-quarter high of 41.3%
- Recruitment billings back to mid-teens growth in H1
- 99acres and B2C growing faster than the core
Concerns
- Headline consolidated profit swings with investment gains (my view)
- GCC and IT hiring were soft in FY26
- Shiksha is dragging overall billings growth
- A leadership transition, if confirmed, adds uncertainty
Things to track in Q3 FY27
- Recruitment billings growth: can it stay at 12–15%?
- Operating margin holding above 40%
- 99acres profitability
- Official clarity on the leadership change
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Entrackr, 28 Oct 2026 · [2] Zee Business – billings, dividend · [3] InCred Money – Q2 FY27 · [4] Inc42 / WealthLens on X – consolidated PAT split · [5] Investing.com – Q2 FY27 slides · [6] VIE Stories – Q2 FY27 · [7] FilingReader – Q2 FY26 · [8] Info Edge – Q4 FY26 press release · [9] HDFC Sky – HSIE Q4 FY26 · [10] Muthoot/Capital Market – Q4 FY26 billings · [11] Business Standard – FY24 billings · [12] Trendlyne – FY25 revenue · [13] FilingReader – Q2 FY26 exceptional gain
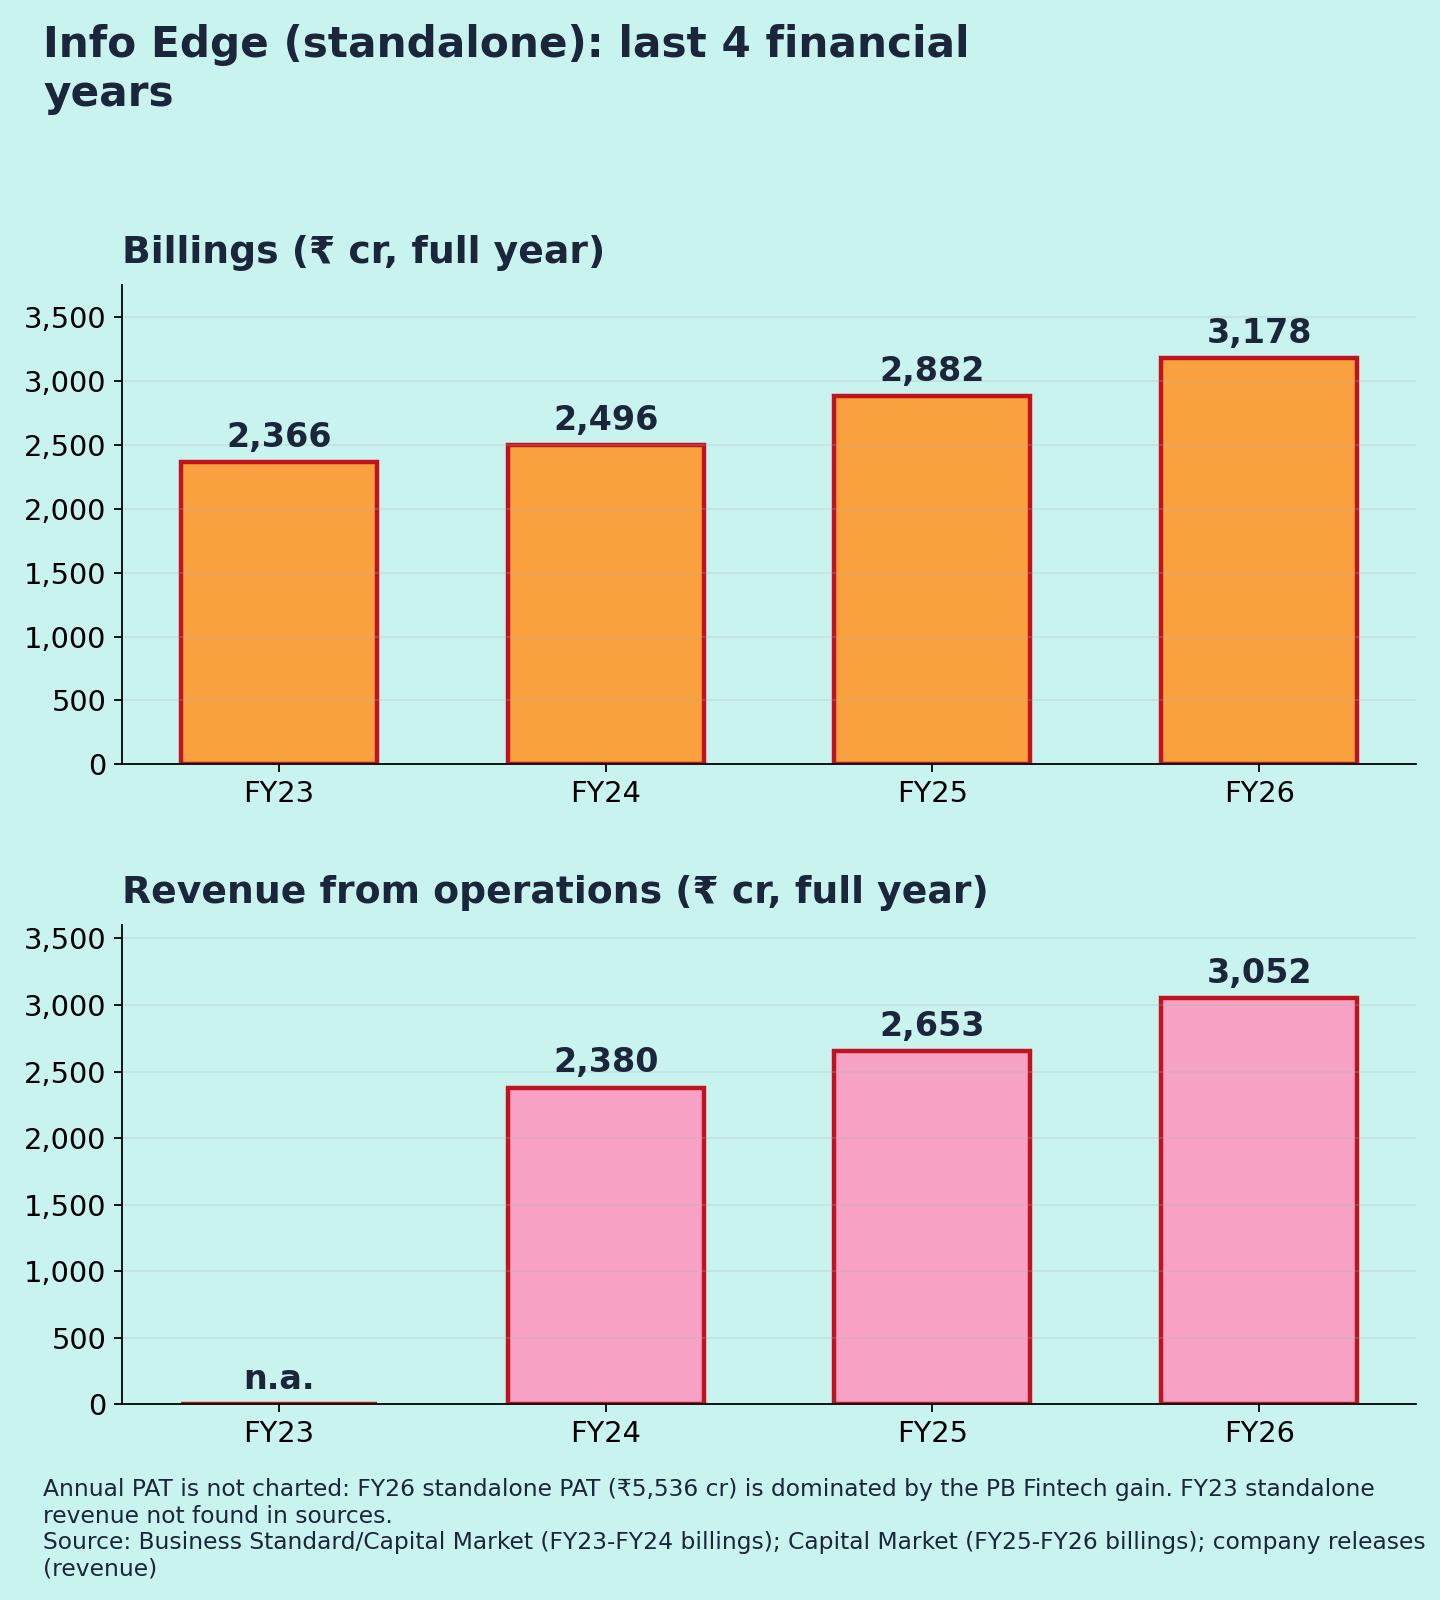
Charts: (1) last 5 quarters standalone revenue & PAT [2][7][8][10]; (2) FY23–FY26 standalone billings & revenue [8][10][11][12]; (3) operating margin and billings [5][7][8] (Q3 FY26 and Q1 FY27 derived).