Hindustan Petroleum (HINDPETRO): Q2 FY27 results analysis
(quarter ended 30 Sep 2026)
All figures standalone, ₹ crore unless stated (the investor handout, EBITDA and GRM are on this basis). Results released during market hours on 22 Oct 2026 [1]. EBITDA is the company's figure (includes other income). YoY/QoQ %, margins and ratios are my calculations.
| Metric | Q2 FY27 | YoY | QoQ |
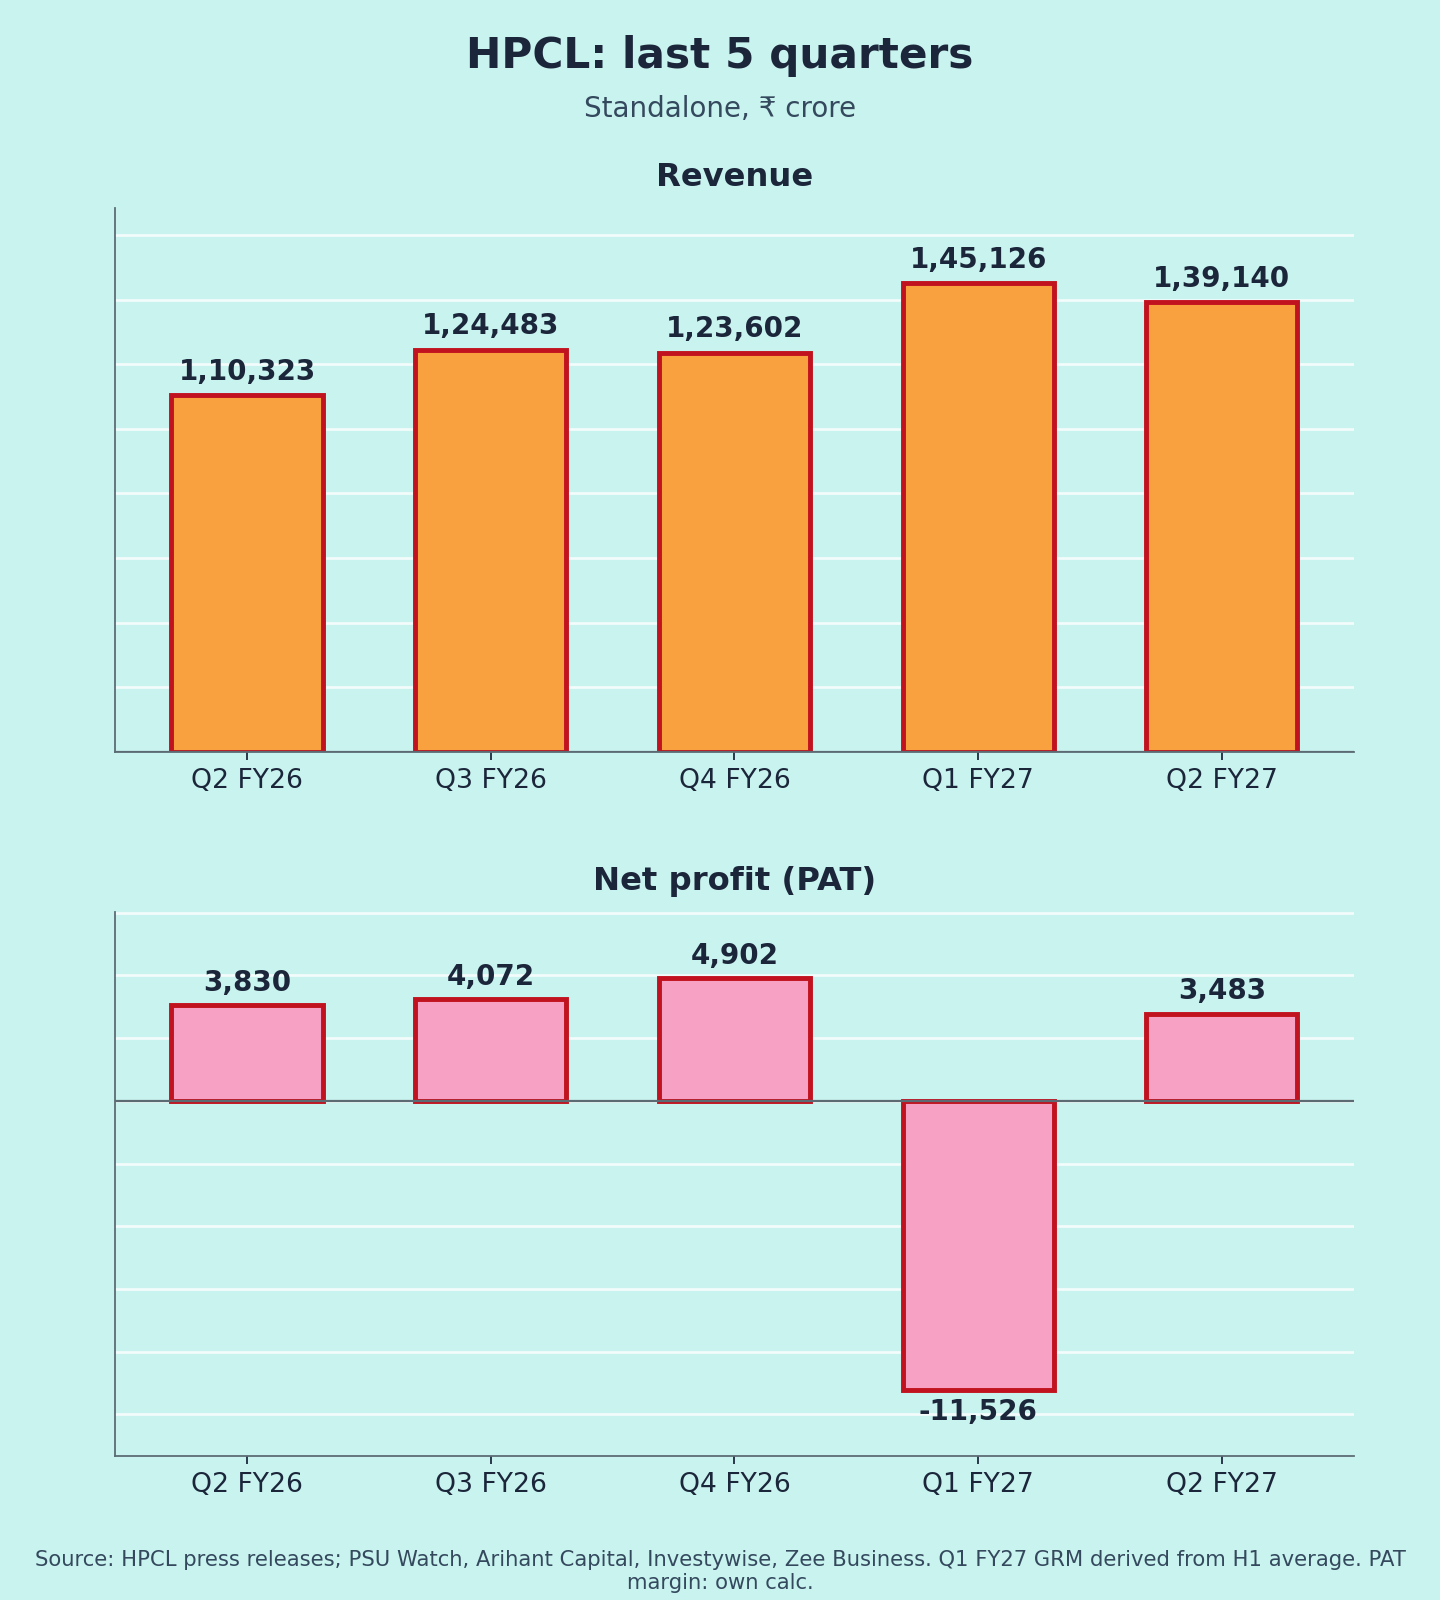
| Revenue from ops | 1,39,140 | +26.1% | −4.1% |
| EBITDA (company) | 9,822 | ~7,437* | (14,860)** |
| EBITDA margin | 7.1% | 6.7% | n.m. |
| PBT | 6,768 | +32.2% | vs (17,446) |
| PAT | 3,483 | −9.1% | vs (11,526) |
| PAT margin | 2.5% | 3.5% | n.m. |
| Other income / PBT | 11.0% | 10.7% | n.m. |
| GRM (US$/bbl) | 32.15 | 8.80 | 23.8** |
Sources: [1][2][3]. *Q2 FY26 EBITDA rebuilt from PBT + interest + D&A (my estimate). **Derived from H1 figures (my calculation).
Source notes:
- Consolidated PAT is ₹3,625 cr (−6.1%) [4]; standalone is ₹3,483 cr.
Quality of earnings
PBT rose 32%, but PAT fell 9% because tax jumped to ₹3,285 cr from ₹1,288 cr, all of it deferred tax [1]. That is the reversal of Q1's ₹5,920 cr deferred-tax credit, so tax is a non-cash drag, not a business problem (my reading).
Refining did the heavy lifting: GRM of $32.15/bbl vs $8.80 a year ago, with refineries at 100% utilisation [1]. Marketing margins on some products stayed suppressed [1].
Two items to note:
- Sales include ₹3,960 cr of government LPG compensation for H1 (six instalments) [1].
- A further ₹18,049 cr of LPG under-recovery is not booked as income or receivable [1].
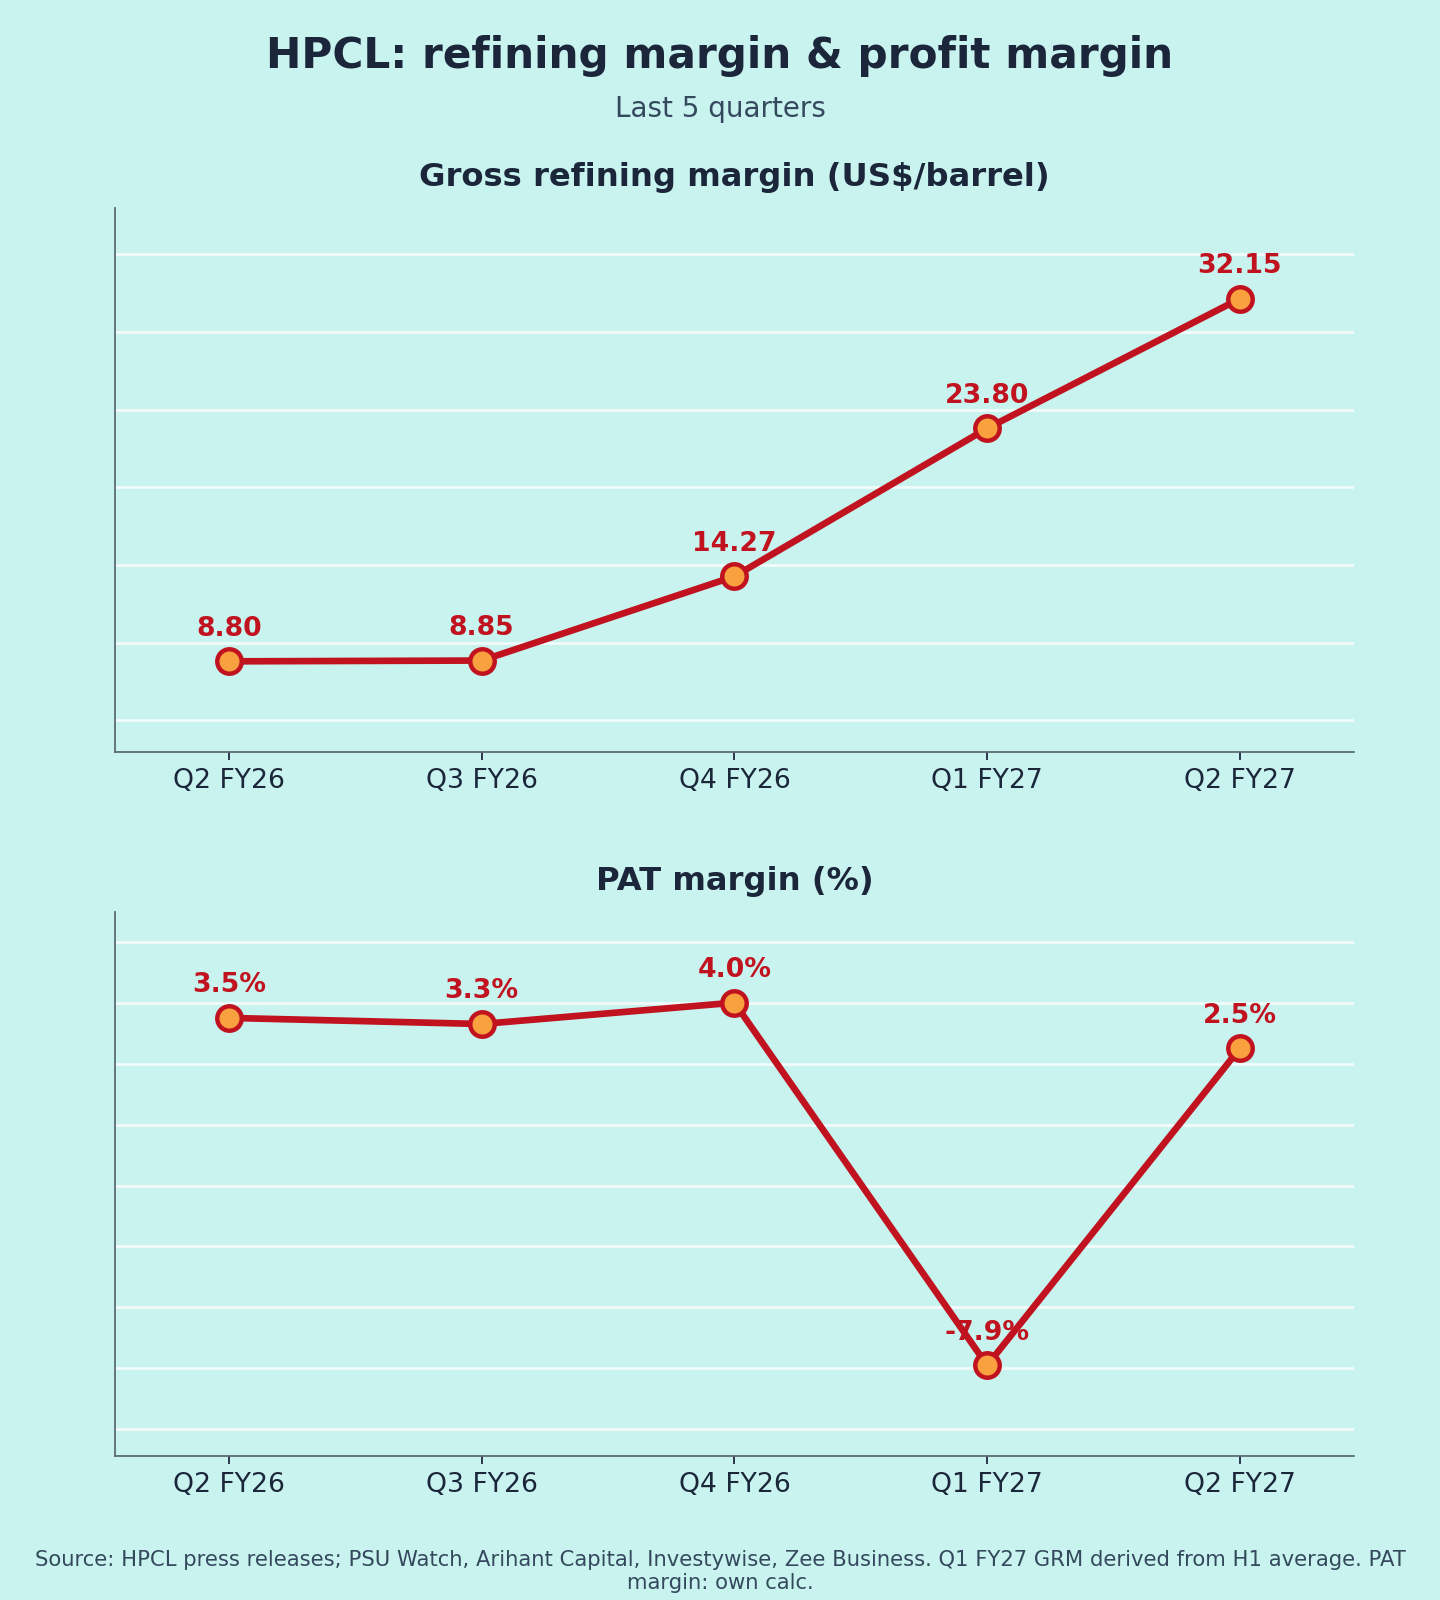
Margins (Chart 3)
GRM over five quarters: 8.80 → 8.85 → 14.27 → 23.8 → 32.15 $/bbl [1][7][8]. PAT margin swung from +4.0% (Q4 FY26) to −7.9% (Q1 FY27) and back to 2.5%. The West Asia crisis drove both extremes: product cracks rose, but retail fuel prices were held (interpretation).
Guidance and projects: what changed
No numeric guidance yet; the analyst call is on 23 Oct [6].
- Rajasthan refinery (HRRL): commercial operation began 22 June 2026 [9], after missed targets of Oct 2022, Dec 2025 and Jan 2026, and an April fire [10]. Cost was revised to ₹79,459 cr from ₹43,129 cr [10].
- HRRL petrochemicals: targeted for Q4 calendar 2026 [11].
- HRRL debt: ₹51,970 cr refinanced at lower cost; rating upgraded to AA+ [1].
Positives
- Record GRM and full refinery utilisation [1]
- Petrol + diesel volumes +10% YoY [1]
- HRRL finally commercial [9]
Concerns
- Standalone debt ₹65,458 cr (+37.5% since March); D/E 1.38 [1]
- Operating cash flow −₹7,832 cr in H1 [1]
- ₹18,049 cr unrecognised LPG buffer; compensation depends on policy [1]
- Earnings hinge on crude and cracks, which are hard to forecast (my view)
Things to track in Q3 FY27
- GRM vs the $32 peak, and marketing margins on petrol/diesel/LPG
- Any new government LPG compensation
- Debt reduction from the Q1 peak of ₹72,597 cr
- HRRL petrochemical start-up and its first profit contribution
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] PSU Watch – Q2 FY27 detailed results · [2] Indian Masterminds – results & price · [3] Arihant Capital – Q3 FY26 · [4] Free Press Journal – consolidated · [5] Zee Business · [6] Zee Business preview / NiftyTrader · [7] HPCL – FY26 press release · [8] InvestyWise – Q3 FY26 · [9] Reuters brief via Stockopedia · [10] The Week – HRRL cost · [11] Argus · [12] HPCL – FY24 · [13] Bigul – FY23
Charts:
(1) last 5 quarters revenue & PAT [1][3][7][8];
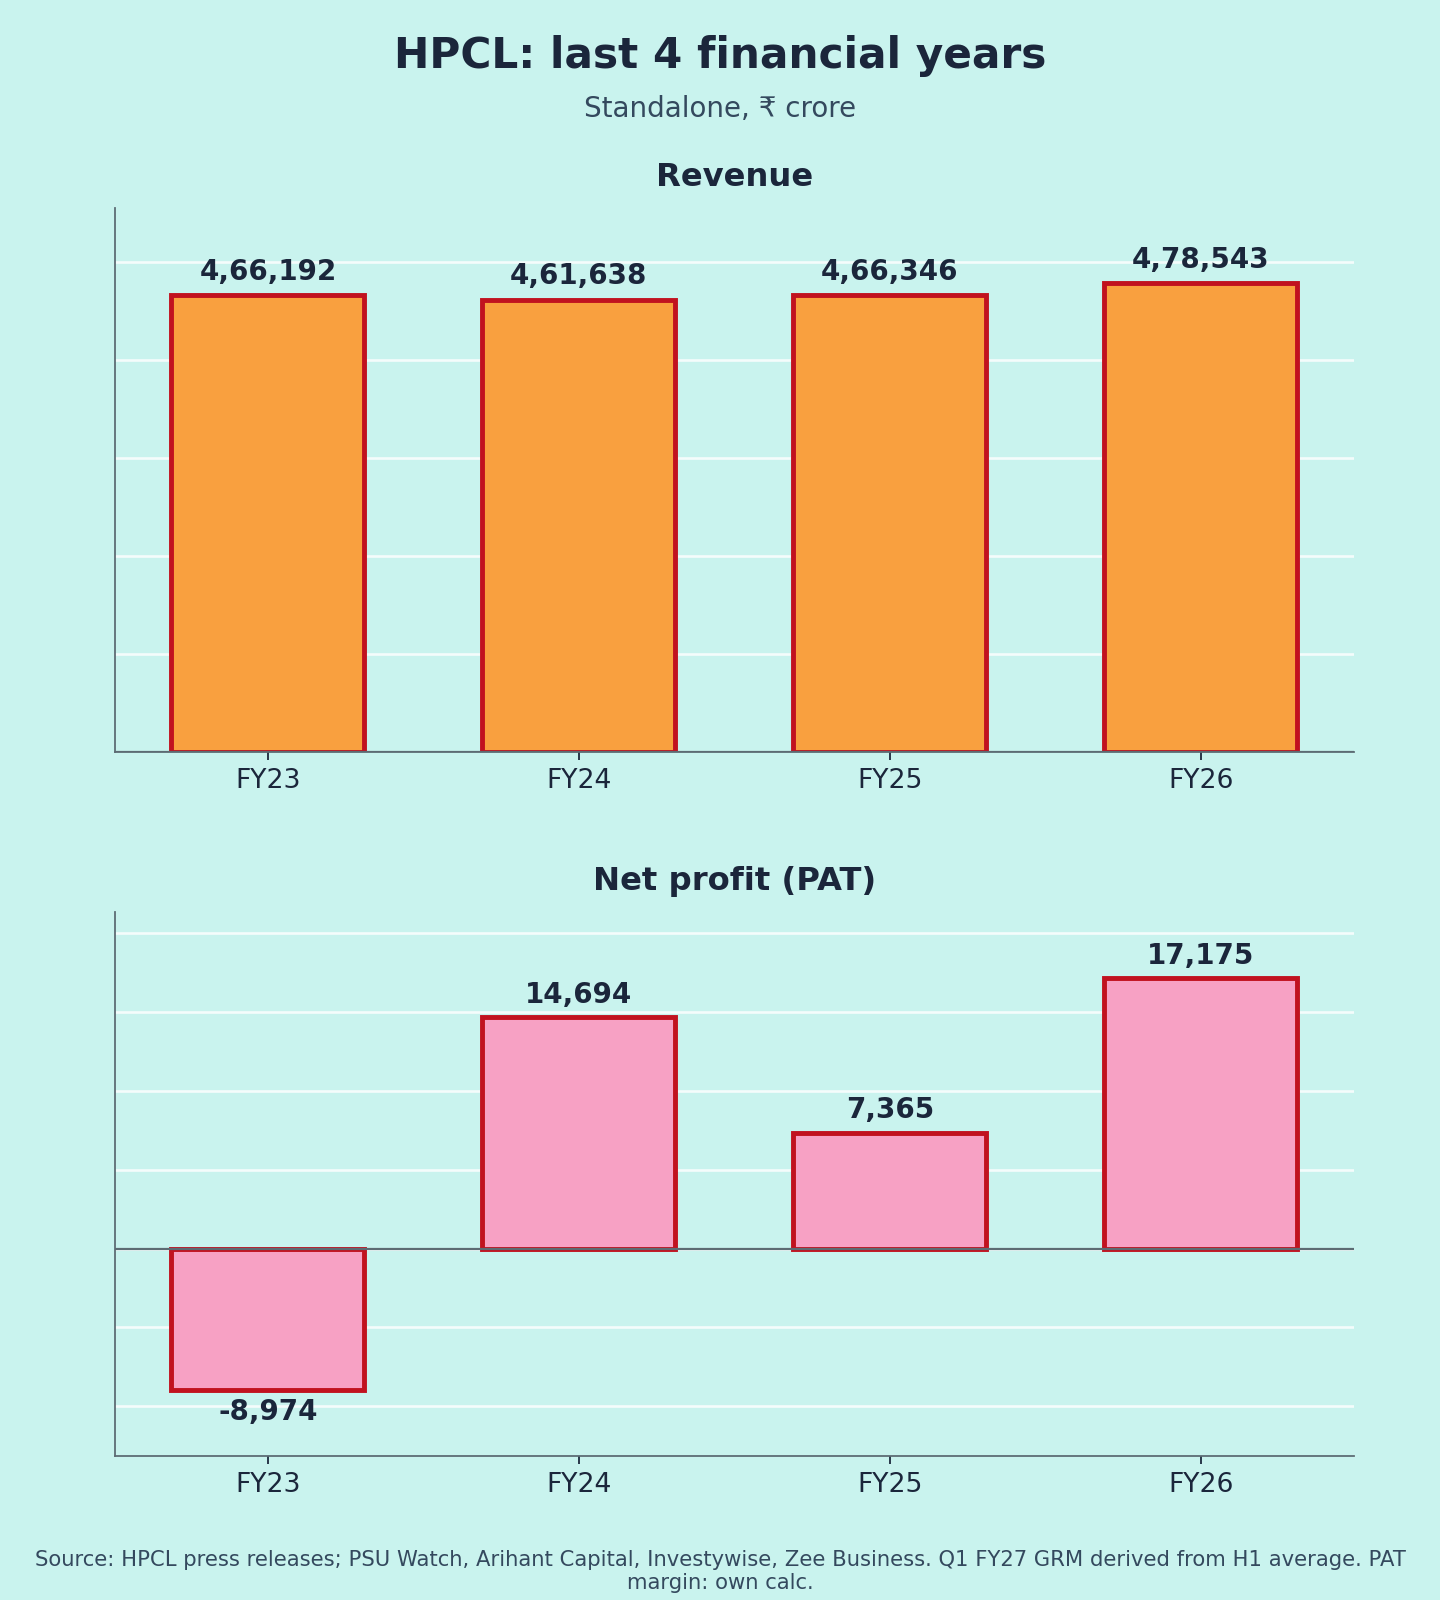
(2) FY23–FY26 revenue & PAT [7][12][13];
(3) GRM and PAT margin [1][7][8] (PAT margin own calc.).