Colgate-Palmolive (India) (COLPAL): Q2 FY27 results analysis
(quarter ended 30 Sep 2026)
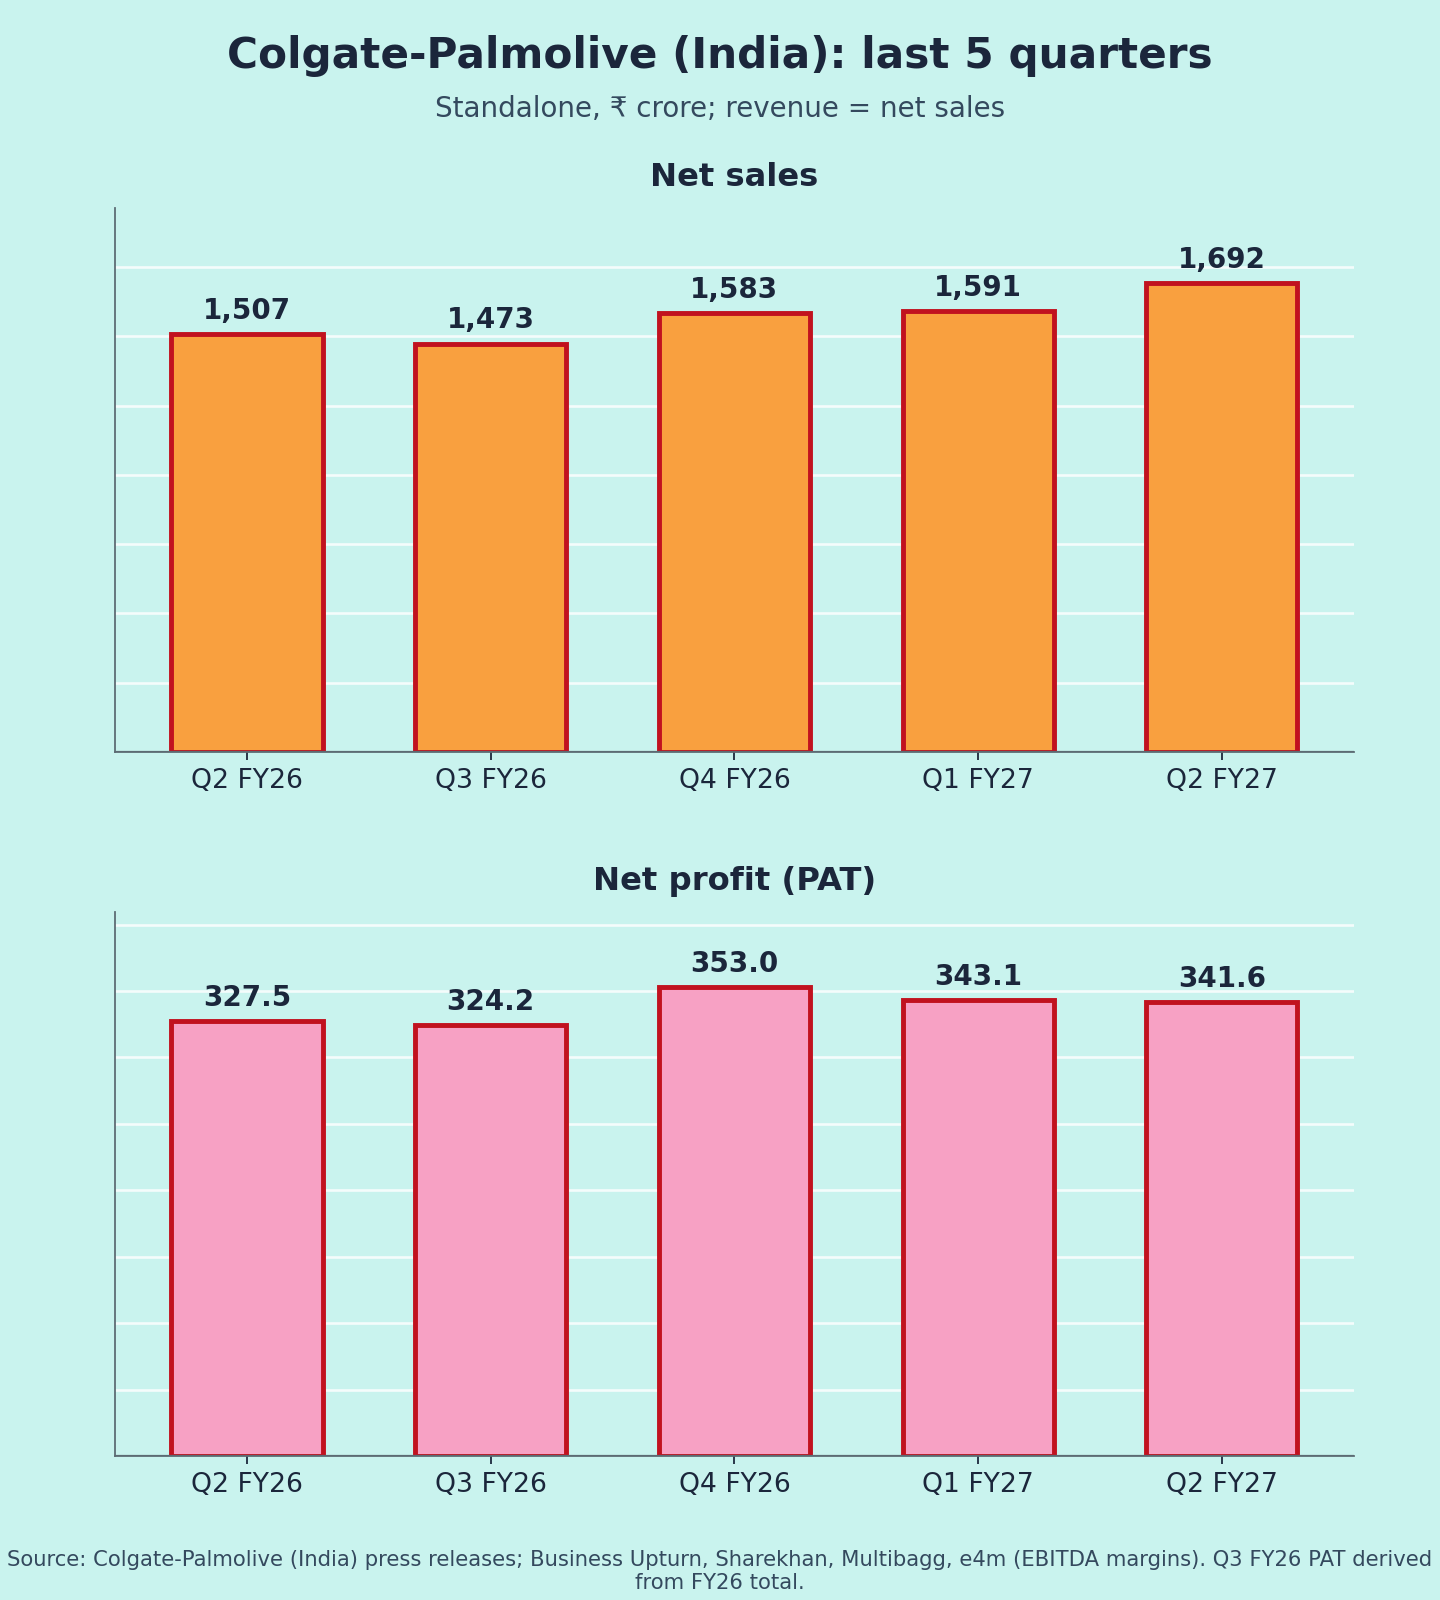
Standalone figures (the company's reporting basis), ₹ crore unless stated. Results released on 22 Oct 2026 [1][2]. "Revenue" here is net sales, as in the company's releases. YoY/QoQ %, margins and ratios are my calculations unless noted.
| Metric | Q2 FY27 | YoY | QoQ |
| Net sales | 1,692 | +12.2% | +6.3% |
| EBITDA (ex-OI, est.) | ~474 | +1.7% | – |
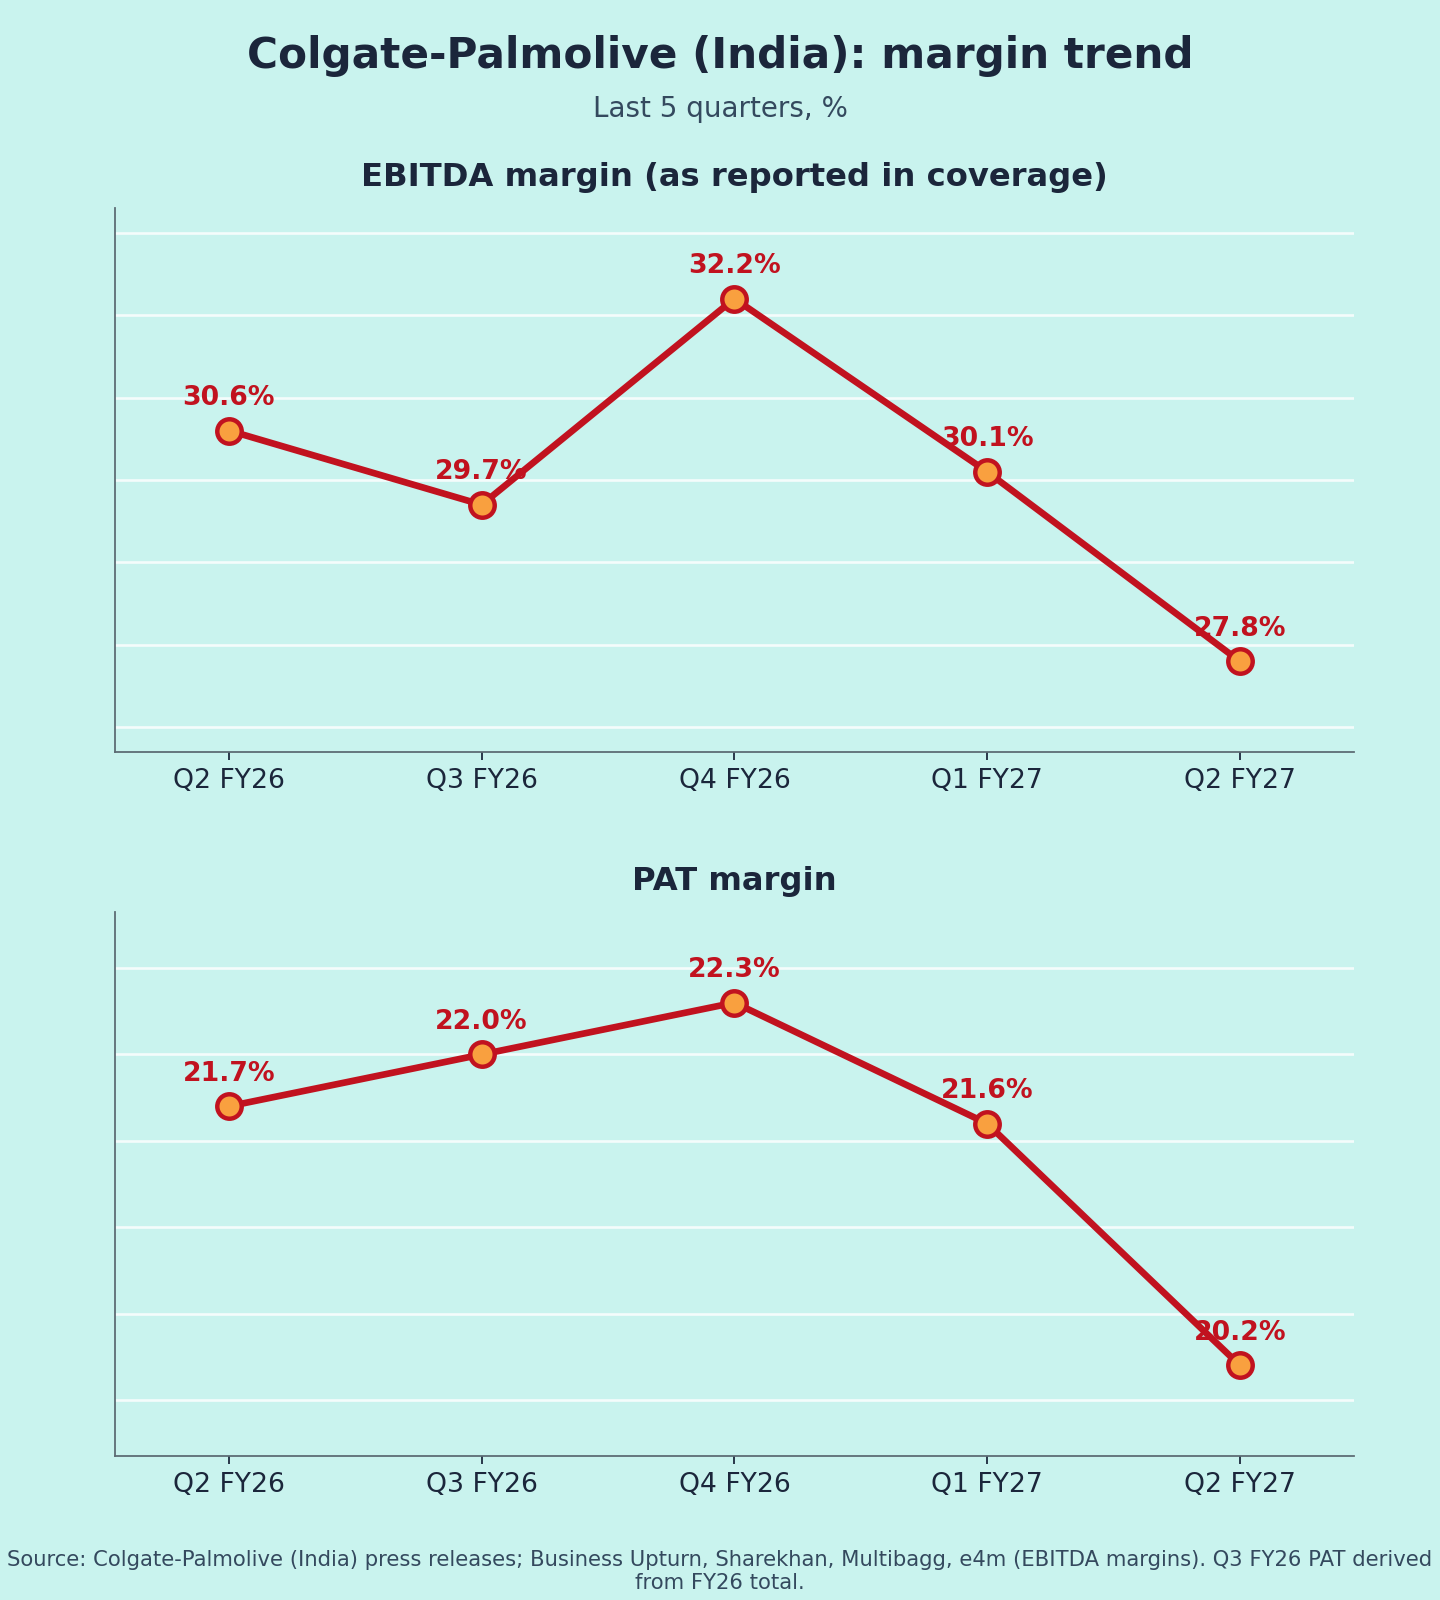
| EBITDA margin | 27.8% | 30.6% | 30.1% |
| PBT (pre-exceptional) | 460 | +4.1% | −1.1% |
| PAT | 341.6 | +4.3% | −0.4% |
| PAT margin | 20.2% | 21.7% | 21.6% |
| Other income / PBT (est.) | ~4.7% | ~3.4% | – |
Sources: [1][2][3][4]. EBITDA margins as reported in coverage; denominators may differ slightly.
Source note: revenue from operations (incl. other operating income) is ₹1,705.8 cr (+12.3%) [2]. Net sales are ₹1,692 cr (+12.2%) [1].
Quality of earnings
Weak base. Q2 FY26 revenue had fallen 6.3% during the GST-cut transition [5]. So the 12% growth is flattered. Still, Q1 FY27 also grew ~12%, on a normal base [6].
Spending absorbed the growth. Gross margin rose 40 bps to 69.6% [1]. But advertising jumped 40% to ₹315 cr, about 18.6% of sales (my calculation) [1]. EBITDA grew just 1.7% [3].
Other income rose ~44% and helped PBT growth reach 4% [3].
One-offs: excluding one-offs and exceptional items, PAT grew 5.5% [1].
Profit came in below estimates (₹342 cr vs ₹364 cr est.) [4].
Margins (Chart 3)
EBITDA margin: 30.6% → 29.7% → 32.2% → 30.1% → 27.8% [3][6][7][8]. Q2 is the lowest of the five. The cause is deliberate brand investment, not input costs, since gross margin improved (interpretation).
Management commentary: what changed
There is no numeric guidance. Changes vs earlier quarters:
- Leadership: Manish Anandani now speaks as MD & CEO [2]; the Q1 release was by Prabha Narasimhan [6].
- Growth vs margin: in Q1 and Q4, management said it would reinvest gross-margin gains into ads and premiumisation [6][9]. Q2 shows that strategy clearly, with ad spend up 40% vs +33% in Q1 [1][6].
- Commodities: management continues to flag commodity volatility, managed via cost savings and calibrated pricing [1].
- Dividend: interim dividend of ₹24/share; record date 2 Nov [4][10].
Positives
- Second straight quarter of double-digit sales growth [2]
- Gross margin expanding (69.6%) [1]
- Premium portfolio growing fast [9]
Concerns
- EBITDA nearly flat despite 12% sales growth [3]
- Growth partly from a weak base [5]
- Margin now depends on ads paying off (my view)
- Leadership transition [2]
Things to track in Q3 FY27
- Sales growth on a normal base (Q3 FY26 grew only 1.4%)
- Ad spend as % of sales vs EBITDA margin
- Volume growth in toothpaste
- New CEO's first stated priorities
Not a buy/sell recommendation. Facts are sourced; opinions are labelled.
Sources [1] Storyboard18 – Q2 FY27 · [2] Business Standard, 22 Oct · [3] Business Upturn · [4] Zee Business · [5] Business Standard – Q2 FY26 · [6] Colgate India – Q1 FY27 release / Multibagg – Q1 · [7] Sharekhan – Q3 FY26 · [8] e4m – Q2 FY26 · [9] Colgate India – Q4 FY26 release · [10] Lapaas Voice · [11] Colgate India – FY24 release · [12] Colgate India – FY25 release
Charts: (1) last 5 quarters net sales & PAT [1][6][9][13];
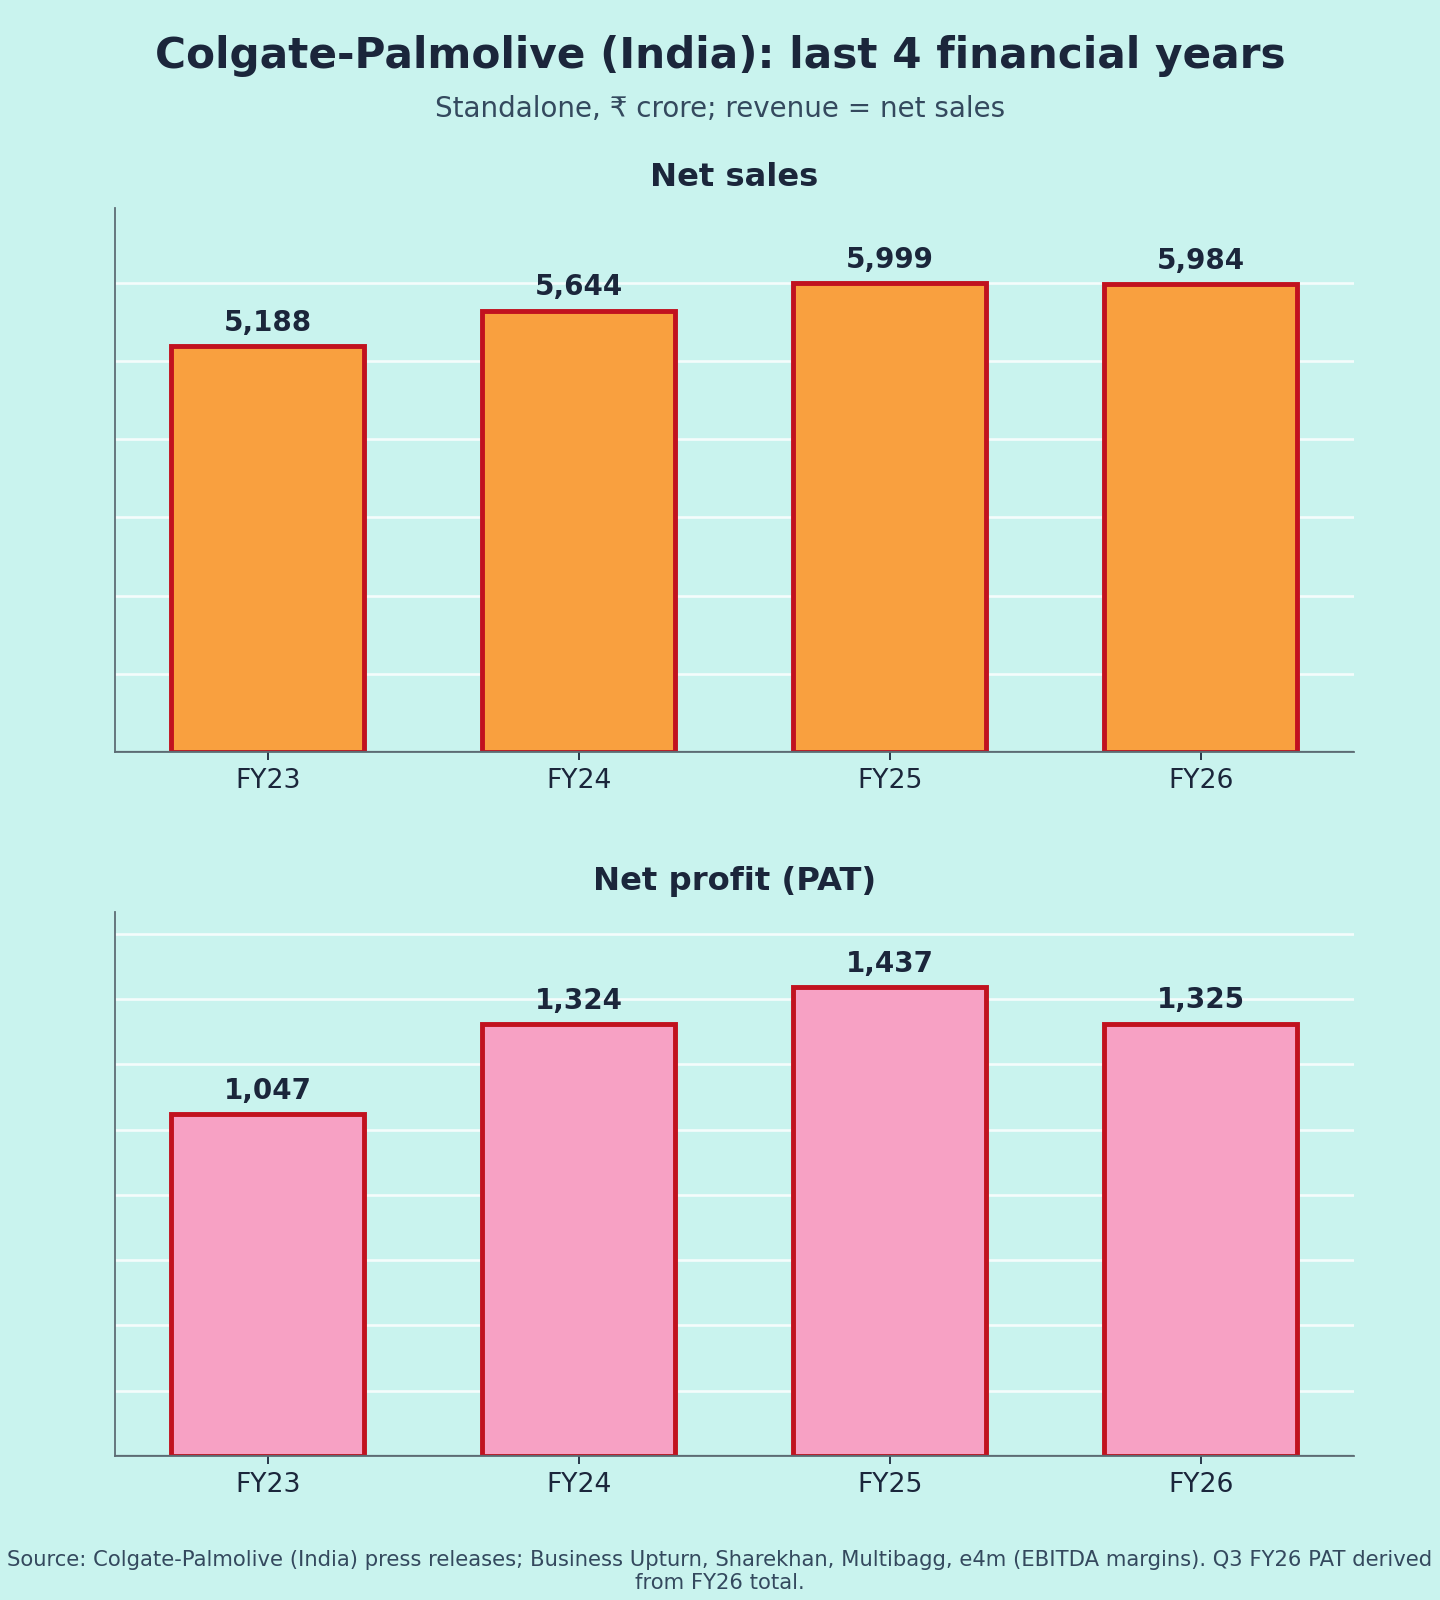
(2) FY23–FY26 net sales & PAT [9][11][12] (Q3 FY26 PAT derived from the FY26 total);
(3) EBITDA and PAT margin [3][6][7][8] (PAT margin own calc.). [13] Colgate India – Q3 FY26 release